
Navigating Election Volatility: Keeping Politics Out of Your Investments

Dovetailing from my most recent blog post, The Post-Midterm Rally: 19 for 19, But This Time Has Real Headwinds, I want to explore the psychological side of the political cycle. In that post, we looked at the incredible historical streak of market rebounds after midterm elections, alongside the unique economic challenges we are facing today. But while history is on our side, getting through the election season itself is often easier said than done, especially with the 2026 midterm elections fast approaching. The news cycle is becoming increasingly loud, polarized, and—for many people—a bit stressful. Every day brings a new round of polls, debates, and dramatic predictions about what the future holds depending on which party gains control.

When the political temperature rises, it is entirely natural to feel a sense of urgency. However, as an investor, one of the most critical challenges you will face over the coming months is a simple one: keeping your political beliefs separate from your investment strategy.

To help you keep a steady hand through this election cycle, let’s explore why elections cause so much noise, what history actually tells us about markets and politics, and some practical strategies for staying on track.

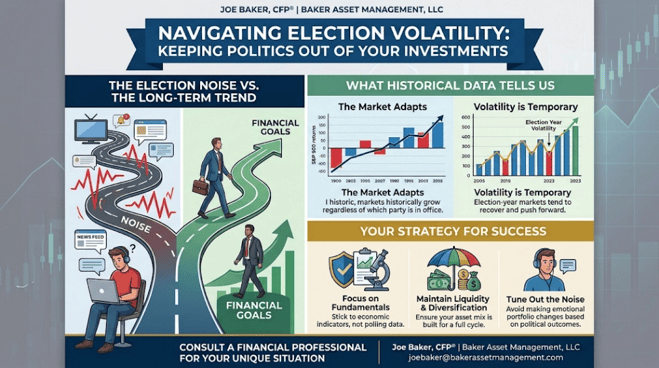
1. The Election Noise vs. The Long-Term Trend

It is easy to fall into the trap of thinking that a specific election outcome will either “save” or “ruining” the economy. The media often amplifies this narrative, framing every legislative shift as a make-or-break moment for your portfolio.

But there is a vast difference between the chaotic “noise” of an election season and the long-term trend of the stock market.

While elections can introduce short-term volatility as the market tries to predict future policies, the long-term trajectory of the S&P 500 is driven by far more powerful forces:

  • Corporate Earnings: The profitability and innovation of American businesses.
  • Economic Fundamentals: Interest rates, consumer spending, inflation, and employment data.
  • Global Progress: Advancements in technology and productivity.

A political party winning or losing an election doesn’t rewrite the fundamental rules of the global economy. Good businesses continue to find ways to generate profit, innovate, and provide value to their shareholders regardless of who holds the gavel in Washington.

2. What Historical Data Tells Us

When we look back at decades of market history, several clear patterns emerge that should reassure anxious investors:

The Market Adapts (Regardless of the Party in Power)

A common misconception is that the stock market only performs well when one specific party is in office. But history tells a very different story.

The S&P 500 has historically grown under all combinations of government—whether we have a Democratic president, a Republican president, a divided Congress, or single-party control. Since World War II, the market’s long-term upward trend has remained remarkably consistent, adapting to different administrations and regulatory environments.

Volatility Is Temporary

Midterm election years (like 2026) are historically known for higher-than-average market volatility, particularly in the months leading up to November. The uncertainty of who will hold power can cause the market to fluctuate.

However, once the results are in—regardless of which party wins—the uncertainty resolves itself. Historically, the market tends to experience a post-election “certainty bounce,” often rallying in the months following a midterm election as businesses and investors adjust to the known landscape.

3. Your Strategy for Success

How do you navigate this polarized environment without letting it affect your hard-earned savings? Here are three strategies to focus on:

Focus on Fundamentals

When evaluating your portfolio, rely on economic indicators, corporate earnings, and interest rates—not polling data. Let the math, not your political opinions, guide your asset allocation.

Maintain Liquidity and Diversification

If you know you will need cash in the near term, ensure you have an adequate liquidity buffer (such as high-yield savings or short-term CDs) so you are never forced to sell stocks during a temporary, election-induced dip. Make sure your portfolio is diversified across different asset classes to smooth out any bumps.

Tune Out the Noise

The single best thing you can do for your portfolio (and your peace of mind) during an election year is to limit your consumption of sensationalized news. Avoid making emotional, impulse changes to your investment plan based on political headlines or debate outcomes.

The Bottom Line

An election is a major event for our country, but it is just one of many events that the stock market encounters and adapts to over time. Your investment plan should be built to withstand a full market cycle—which includes several election cycles.

Please comment or send an email if you have any questions.

Joe Baker, CFP®

Baker Asset Management, LLC

joebaker@bakerassetmanagement.com
A Comprehensive Guide: Are Your Social Security Benefits Taxable?

You may have paid Social Security taxes throughout your working years, so it is natural to wonder whether those benefits can be taxed again in retirement. The answer is that, for many people, some portion of Social Security benefits can be subject to federal income tax.

It is one of the most common questions pre-retirees and new retirees ask. The rules are not always intuitive, and misunderstanding them can lead to an unexpected tax bill that affects your retirement income plan.

That is why this guide is designed to help you understand when Social Security benefits may be taxable, how the calculation works, and what it can mean for your broader financial strategy.

The Key Concept: “Combined Income”

The IRS uses a specific formula to calculate your income for Social Security tax purposes. Your Social Security number (SSN) does not determine your taxability; rather, it’s about your total financial picture.

To understand if your benefits are taxable, you must first determine your Combined Income, also known as Modified Adjusted Gross Income (MAGI).

The Combined Income Formula:

Combined Income = Adjusted Gross Income (AGI) + Nontaxable Interest + 50% of Your Social Security Benefits

Think of it as adding all your taxable income (like wages, pensions, and capital gains) plus your tax-exempt interest income (e.g., from municipal bonds), and then adding exactly half of your total Social Security benefits.

Navigating Federal Income Brackets

Once you have your Combined Income, the IRS uses three income thresholds to calculate the percentage of your benefits that are taxable at the federal level. The limits are different for individuals and married couples filing jointly:

If You File as “Single,” “Head of Household,” or “Qualifying Widow(er)”:

  • Under $25,000: 0% of your benefits are taxable. (Congratulations, you might get all your Social Security tax-free!)
  • $25,000 to $34,000: Up to 50% of your benefits may be subject to tax.
  • Over $34,000: Up to 85% of your benefits may be taxable.

If You File as “Married Filing Jointly”:

  • Under $32,000: 0% of your benefits are taxable.
  • $32,000 to $44,000: Up to 50% of your benefits may be subject to tax.
  • Over $44,000: Up to 85% of your benefits may be taxable.

Note on “Up to”: The 50% and 85% are maximums. The calculation is dynamic. For illustrative examples of precise tax situations, you would need to run detailed scenarios, but these brackets give you the essential ranges.

Don’t Forget About State Taxes

While federal rules apply across the entire country, state-level rules vary significantly.

  • Across the United States: The vast majority of states (42 states plus Washington, D.C.) exempt Social Security benefits from state income taxes entirely. However, a small handful of states—including Colorado, Connecticut, Minnesota, Montana, New Mexico, Rhode Island, Utah, and Vermont—still tax a portion of Social Security income based on state-specific thresholds.

If you are considering moving or splitting time between states in retirement, factoring state-level taxation into your plan is just as vital as federal planning.

What This Means for Your Financial Strategy

Understanding these rules is about more than just a tax form. It affects everything from your monthly cash flow to your overall retirement strategy.

1. Unexpected Taxes

A larger-than-expected tax bill can reduce the cash flow you thought you had available for spending.

2. Withdrawal Strategy

Where you draw income from matters. Pulling too much from taxable accounts or traditional retirement accounts can increase your provisional income and make more of your Social Security benefits taxable.

3. RMDs

Required minimum distributions can create a ripple effect. If RMDs raise your income enough, they can increase the taxable portion of your Social Security benefits as well.

4. Coordination Matters

Planning withdrawals from Traditional IRAs, Roth IRAs, brokerage accounts, and other sources together can help create a more tax-efficient retirement plan.

Taking the Next Step

These rules are manageable once you understand the framework, but they can still be complicated when you apply them to your own numbers. Your situation may also change over time as income, investment returns, tax law, and retirement needs change.

If you are making retirement income decisions, it is wise to consult a qualified financial professional or tax professional. They can help you run scenarios using your actual figures and build a withdrawal strategy that fits your goals.

The bottom line: Social Security benefits are not always tax-free in retirement, and the amount subject to tax depends on your overall income picture. With the right planning, you can better understand the rules and make smarter decisions about your retirement cash flow.

Please comment or send an email if you have any questions.

Joe Baker, CFP®

Baker Asset Management, LLC

joebaker@bakerassetmanagement.com
Economic Headwinds: The Unnecessary Strain on U.S. Businesses and Consumers

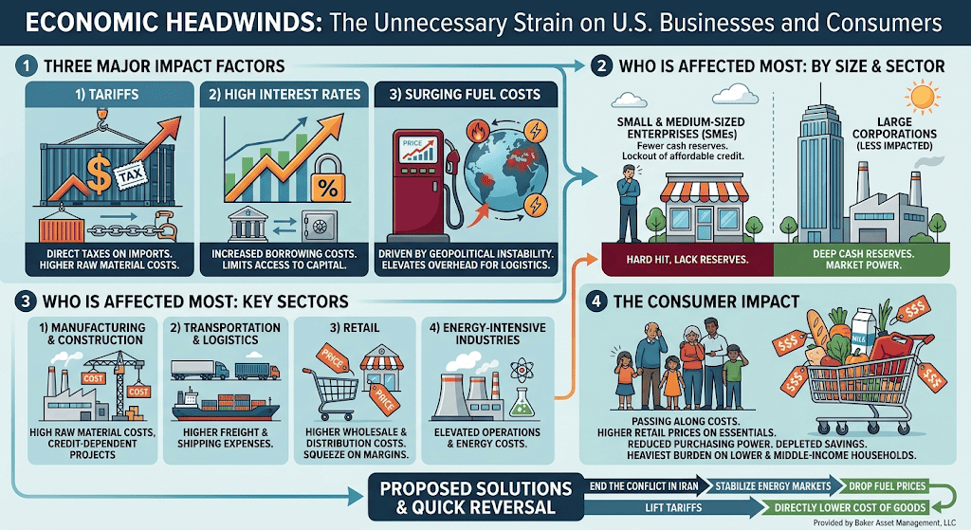
The U.S. economy has shown remarkable resilience, largely buoyed by a historic surge in productivity and investment driven by the artificial intelligence revolution. However, that underlying momentum is now in serious jeopardy due to three major self-inflicted pressures: high interest rates, trade tariffs, and surging inflation driven by skyrocketing fuel costs. These conditions create an unnecessary drag on economic expansion, but they could be reversed quickly by ending the conflict in Iran to stabilize global energy markets and removing trade tariffs.

Here is a breakdown of how these factors are impacting the market and who is bearing the brunt of the burden:

The Core Economic Pressures

  • Tariffs: Tariffs act as a direct tax on imported goods, raising the cost of raw materials and inventory. Businesses are forced to either absorb these losses or pass them on to consumers, driving inflation higher.
  • Surging Fuel Costs: Geopolitical conflict—specifically the war in Iran—has pushed fuel and energy prices up rapidly. This disproportionately increases overhead for any business reliant on physical operations, shipping, or manufacturing.
  • High Interest Rates: Elevated borrowing costs mean that securing capital for business expansion, equipment upgrades, or day-to-day cash flow management is now prohibitively expensive.

Who is Affected the Most?

  • By Business Size: Small and medium-sized enterprises (SMEs) bear the heaviest load. Unlike massive multinational corporations, SMEs lack the deep cash reserves and market power to absorb sustained cost increases, while high interest rates restrict their access to affordable working capital.

  • By Sector:
  • Manufacturing & Construction: Heavily reliant on raw materials subject to tariffs and credit-dependent for project financing.
  • Transportation & Logistics: Surging fuel costs act as an immediate hit to margins for any firm moving physical goods.
  • Retail: Retailers are squeezed on both ends—paying higher wholesale and transport costs while selling to consumers whose discretionary budgets are pinched by inflation.

  • By Consumer (Lower and Middle-Income Households): Ultimately, these corporate cost pressures spill over onto everyday households. As businesses pass along tariff taxes, elevated freight charges, and higher borrowing expenses, retail prices rise on essential goods like food, energy, and household staples. Lower and middle-income families—who spend a significantly larger portion of their take-home pay on basic necessities—bear the heaviest burden, facing reduced purchasing power and depleted savings as living costs climb.

The Solution

The clearest, most efficient path to economic relief requires straightforward policy changes. Ending the conflict in Iran would immediately ease energy market volatility and lower fuel prices at the pump, while lifting tariffs would directly reduce input costs for businesses and bring relief to consumer budgets across the board. By eliminating these primary drivers of inflation, the Federal Open Market Committee (FOMC) would have the leeway needed to lower interest rates without the risk of runaway prices, providing immediate relief to borrowing businesses and the broader economy.

Please comment or send an email if you have any questions.

Joe Baker, CFP®

Baker Asset Management, LLC

joebaker@bakerassetmanagement.com
To Keep or Shred? A Guide to Financial Record Keeping

Between physical filing cabinets and sprawling digital downloads, managing financial paperwork can quickly become overwhelming. Holding onto every piece of paper creates unnecessary clutter, while tossing the wrong document can lead to headaches at tax time—or worse, identity theft if improperly discarded.

Knowing what to keep, what to digitize, and what to run through the shredder keeps your financial life secure and organized.

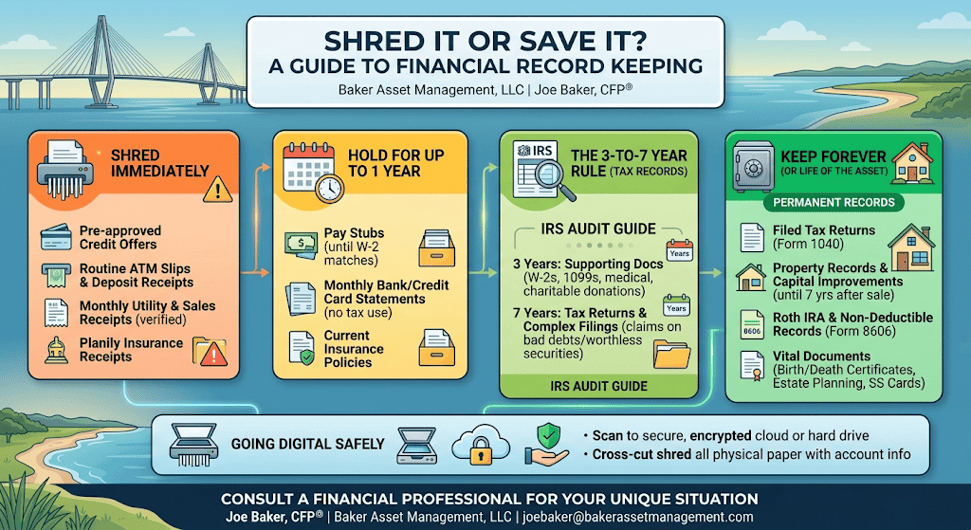
Shred Immediately

  • Pre-approved credit card offers and loan solicitations: Primary targets for identity thieves if left in the trash.
  • Routine ATM slips and deposit receipts: Shred as soon as you verify the transaction on your online bank statement.
  • Monthly utility and sales receipts: Toss after verifying payment, unless you need the receipt for a product warranty, insurance, or a home-office tax deduction.

Hold for Up to 1 Year

  • Pay stubs: Hold until you receive your annual W-2 to verify that earnings and withholdings match.
  • Monthly bank and credit card statements: Keep for up to a year to review annual spending patterns, unless they contain transactions needed for tax deductions.
  • Current insurance policies: Retain current declarations pages; shred expired policies once new coverage is active.

The 3-to-7 Year Rule (Tax Records)

  • Supporting tax documentation (3 Years): The IRS standard period of limitations for an audit is generally three years from the date you filed. Keep 1099s, W-2s, medical bills, and charitable donation receipts for at least this timeframe.
  • Tax returns and complex filings (7 Years): To be safe, retain supporting tax files for seven years. The IRS audit window extends to six years if income is underreported by more than 25%, and seven years for claims on bad debts or worthless securities.

Keep Forever (or Life of the Asset)

  • Filed tax returns (Form 1040): Keep actual tax returns permanently—either as PDFs or physical copies—for personal reference and Social Security verification.
  • Property records & capital improvements: Retain home closing documents, title deeds, and major renovation receipts until at least seven years after you sell the property to substantiate your tax cost basis.
  • Roth IRA & non-deductible IRA records: Keep Form 8606 and contribution records indefinitely to prove tax-free basis upon future withdrawals.
  • Vital personal documents: Birth/death certificates, marriage licenses, military discharge papers, estate planning documents (wills, trusts, powers of attorney), and Social Security cards should remain locked in a fireproof safe.

Going Digital Safely

When clearing out physical files, scanning documents to a secure, encrypted cloud storage service or encrypted hard drive is an effective way to stay organized. However, always use a cross-cut shredder for any physical paper containing account numbers, Social Security numbers, or personal identifying information.

Please comment or send an email if you have any questions.

Joe Baker, CFP®

Baker Asset Management, LLC

joebaker@bakerassetmanagement.com
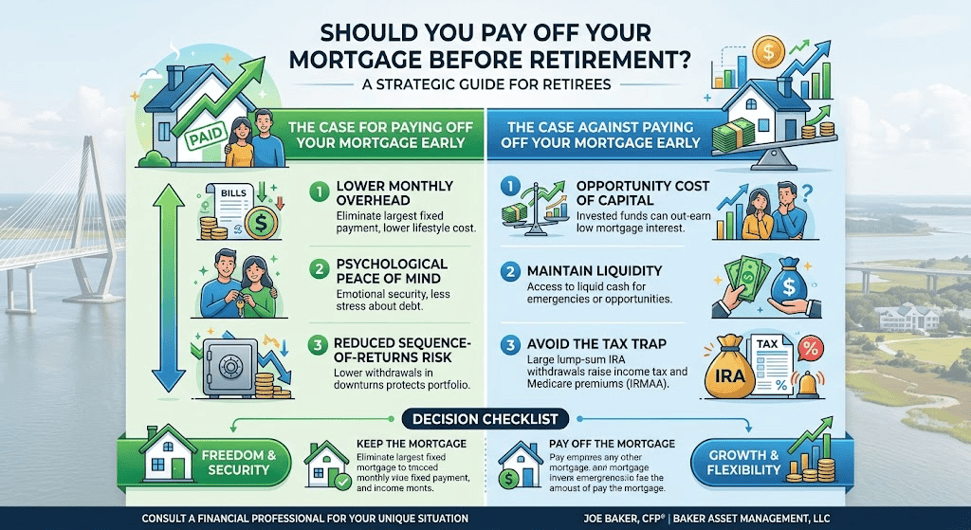
Should You Pay Off Your Mortgage Before You Retire?

For generations, the ultimate retirement milestone was the “mortgage-burning party”—that moment you paid off your final home loan statement and officially owned your piece of property free and clear.

Entering retirement completely debt-free sounds like a no-brainer. But as with most things in financial planning, the actual answer to “Should I pay off my mortgage before I retire?” isn’t always a simple yes or no.

While eliminating a monthly mortgage payment provides undeniable psychological comfort, writing a massive check to clear your home loan can sometimes work against your overall financial flexibility.

If you’re approaching retirement and weighing this decision, here are the core trade-offs to consider before making a move.

The Case FOR Paying Off Your Mortgage

1. Lower Monthly Overhead

Your mortgage is likely your single largest recurring monthly expense. Eliminating principal and interest payments drastically lowers the baseline income you need each month to maintain your lifestyle. Lower required income means smaller withdrawals from your portfolio.

2. Protection Against “Sequence-of-Returns” Risk

One of the biggest risks in early retirement is a major market downturn right after you stop working. If the market drops and you still have high fixed expenses (like a mortgage), you are forced to sell depreciated investments to pay your bills. By eliminating the mortgage, you lower your mandatory distributions, allowing your investment accounts more room to recover during lean market years.

3. Unbeatable Peace of Mind

The emotional benefit of owning your home outright cannot be overstated. For many retirees, knowing that their housing is secure—regardless of what happens to the stock market or the economy—is worth more than any theoretical mathematical gain.

The Case AGAINST Paying Off Your Mortgage

1. The Opportunity Cost of Capital

If you secured a low fixed mortgage rate in past years, the math may favor keeping the loan. If your mortgage rate is sitting at 3% or 4%, but your diversified investment portfolio or high-yield cash vehicles are earning a higher return, your money may work harder for you staying invested rather than locked up in home equity.

2. Illiquidity: You Can’t Eat Real Estate

Home equity is illiquid wealth. Money used to pay down a mortgage is tied up in bricks and mortar. If an unexpected medical emergency, home repair, or family need arises, accessing that home equity quickly isn’t easy—especially once you no longer have a earned income to qualify for a traditional home equity loan. Having liquid cash or accessible taxable investments provides a safety cushion that a paid-off house cannot.

3. The Tax Trap of Large Lump-Sum Withdrawals

If you don’t have enough liquid cash sitting in a bank account and need to withdraw funds from a Traditional IRA or 401(k) to pay off the mortgage balance, be extremely careful. That withdrawal counts as ordinary income. A single large distribution can instantly push you into a significantly higher tax bracket, trigger higher Medicare premium surcharges (IRMAA), and create a hefty tax bill that wipes out any savings on mortgage interest.

A Quick Checklist: Which Side Are You On?

It may make sense to KEEP your mortgage if:

  • You hold a very low fixed interest rate.
  • Paying it off would drain your liquid emergency reserves.
  • Clearing the balance requires pulling a large lump sum out of a taxable retirement account.

It may make sense to PAY OFF your mortgage if:

  • You have excess idle cash sitting in low-interest savings accounts that can cover the balance without tax consequences.
  • Carrying debt causes you significant stress or anxiety.
  • Eliminating the payment is essential for your retirement cash flow to balance out.

The Bottom Line

There is no one-size-fits-all answer. The choice between mathematical optimization and emotional peace of mind comes down to your personal risk tolerance, tax profile, and retirement cash flow goals.

Before making a large lump-sum payment on your mortgage, it’s always wise to run the numbers to see how it impacts your long-term retirement projections and tax liability.

Please comment or send an email if you have any questions.

Joe Baker, CFP®

Baker Asset Management, LLC

joebaker@bakerassetmanagement.com
The Best Way to Fund College….and Beyond

For years, one of the biggest hesitations I’ve heard from parents and grandparents about funding a 529 college savings plan was the fear of overfunding it. “What if they get a scholarship?” or “What if they don’t go to college? We’ll get hit with taxes and a 10% penalty if we pull the money out.”

Thanks to the SECURE 2.0 Act, that fear is largely gone.

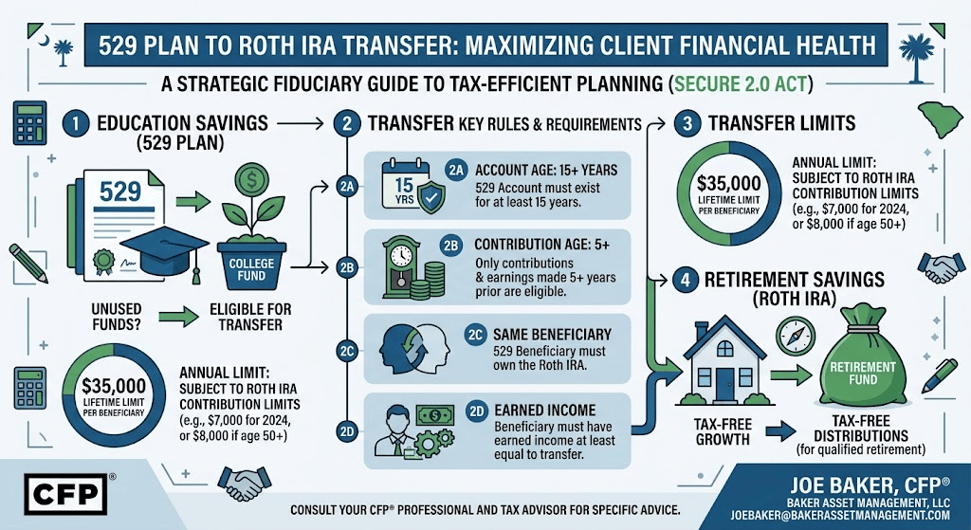
We now have a powerful new financial planning tool: the ability to roll over unused 529 plan funds directly into a Roth IRA for the beneficiary. This effectively turns an education savings account into a tax-free retirement springboard.

Here’s how it works and what you need to know.

The Mechanics of the 529-to-Roth Rollover

If your child or grandchild finishes their education and still has money left in their 529 plan, you can transfer those funds into a Roth IRA in their name. The money moves from a tax-free education account to a tax-free retirement account without incurring taxes or penalties.

This is massive. A young adult starting their career with a jump-started Roth IRA has decades of tax-free compounding ahead of them.

The Rules of the Game (And There Are Several)

As with anything tax-related, the IRS has strict rules you must follow to execute this strategy cleanly:

  1. The $35,000 Lifetime Limit: You can only transfer a maximum of $35,000 during the beneficiary’s lifetime. This isn’t an unlimited backdoor.
  2. Annual IRA Contribution Limits Apply: You cannot move the entire $35,000 at once. The transfers are subject to the annual IRA contribution limits. For 2026, that limit is $7,500. It will take nearly five years to transfer the full $35,000.
  3. Earned Income Requirement: The beneficiary must have earned income (W-2 wages or self-employment income) in the year of the transfer, and the transfer amount cannot exceed their earned income for that year.
  4. The 15-Year Rule: The 529 plan must have been open for at least 15 years.
  5. The 5-Year Rule: Contributions (and the earnings on those contributions) made to the 529 plan in the five years prior to the rollover cannot be transferred.
  6. Direct Transfer: The rollover must be moved directly from the 529 plan to the Roth IRA (a trustee-to-trustee transfer). Do not cash out the 529 and try to deposit it into the Roth yourself.

Why This is a Game Changer

This legislation effectively removes the risk of “over-saving” for college.

  • Bypassing High-Income Limits: Even if your young adult child earns too much to contribute directly to a Roth IRA, they can still receive these 529-to-Roth transfers.
  • Decades of Tax-Free Growth: If you fund a Roth IRA with $7,500 a year from ages 22 to 26 (using leftover 529 funds) and never add another dime, that $35,000 could grow to several hundred thousand dollars of tax-free money by the time they reach retirement age.

What You Should Do Now

If you have an existing 529 plan, track its age. If you’ve been putting off opening a 529 because of overfunding fears, start one now to get the 15-year clock ticking.

Before executing a transfer, you should run the numbers and ensure all IRS criteria are met to avoid unexpected tax hits or state-level recapture rules (some states may treat the rollover as a non-qualified withdrawal).

Please comment or send an email if you have any questions.

Joe Baker, CFP®

Baker Asset Management, LLC

joebaker@bakerassetmanagement.com
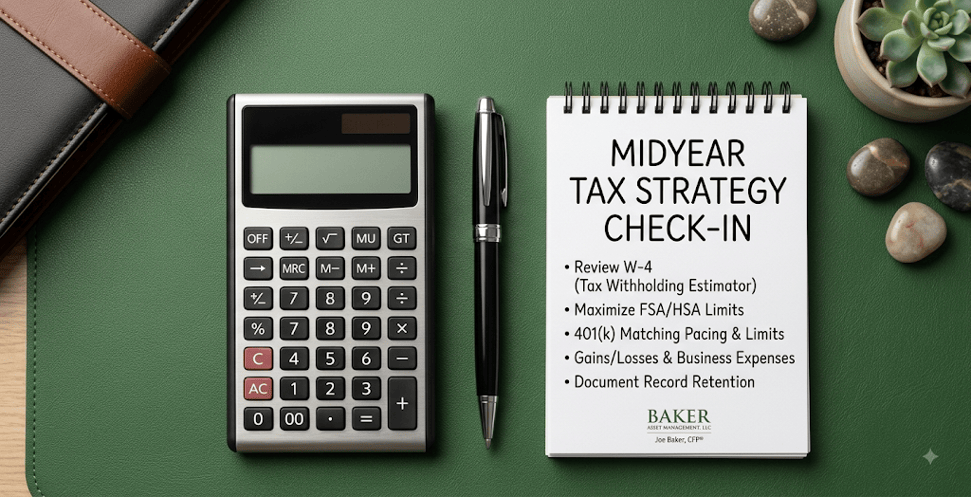
Midyear Tax Check-In: 5 Strategic Moves to Make Right Now

Summer is the ideal time to conduct a midyear financial check-up. Waiting until December leaves very little room to adjust strategy and waiting until tax filing season means it is already too late.

Taking a proactive approach now allows you to optimize your tax position, capture available incentives, and ensure your investment strategy directly aligns with your long-term goals.

Here are 5 key tax and financial check-ins to perform today while there is still time to take action.

1. Review Your Tax Withholdings (IRS Form W-4)

If you changed jobs, got married, welcomed a child, or experienced a significant shift in income this year, update your IRS Form W-4 with your employer.

  • Avoid large tax surprises: Underwithholding results in unexpected bills and potential penalties at year-end.
  • Stop giving the IRS an interest-free loan: A huge refund means you overpaid throughout the year. The IRS does not pay interest on your money. Redirecting that excess cash flow into high-yield savings or investment strategies allows your money to work for you.
  • Action item: Use the IRS Tax Withholding Estimator online or review your recent pay stubs to verify that your withholdings match your actual year-to-date income.

2. Maximize Pre-Tax Account Limits (FSAs & HSAs)

Review your current contribution levels and balances for employer-sponsored benefit accounts.

  • Flexible Spending Accounts (FSAs): Check your remaining balances for healthcare and dependent care FSAs. Because FSA funds operate on a “use-it-or-lose-it” basis (with limited rollover or grace period options), plan out your qualified medical, dental, or dependent care expenses now rather than rushing at year-end.
  • Health Savings Accounts (HSAs): Unlike FSAs, HSA balances roll over indefinitely. If you participate in a high-deductible health plan, aim to max out your HSA contributions to capture triple-tax benefits: tax-deductible contributions, tax-deferred growth, and tax-free withdrawals for qualified medical expenses.

3. Audit Your 401(k) Pacing and Matching

While IRA contributions can be made until the April tax filing deadline, 401(k) salary deferrals must be completed through payroll by December 31.

  • Employer Match Optimization: Ensure your contributions are paced evenly across all pay periods to capture your employer’s full match. Maxing out your 401(k) too early in the year can cause you to miss out on employer matching dollars in later paychecks unless your plan includes a “true-up” provision.
  • Catch-Up Contributions: If you are age 50 or older, review your payroll deductions to ensure you are utilizing catch-up contribution limits across your retirement accounts.

4. Strategize Capital Gains, Losses, and Business Expenses

Midyear provides enough year-to-date data to accurately project your marginal tax bracket.

  • Tax-Loss Harvesting: If you hold investments in taxable brokerage accounts, evaluate opportunities to offset realized capital gains with capital losses.
  • Roth Conversions: If your income is lower than usual this year, executing a partial Roth conversion can move funds into a tax-free growth bucket at a lower tax rate.
  • Business Owners & Side Hustles: Review business income and expenses. Ensure all legitimate deductions are tracked through dedicated business accounts. If operating as an S-Corporation, evaluate your expected annual income to ensure your mix of reasonable salary and distributions remains compliant and tax-efficient.

5. Streamline and Update Your Financial Records

Proactive tax planning relies entirely on clean, real-time financial data.

  • Maintain Clean Books: Reconcile your business and personal accounts monthly using software like Quicken or QuickBooks to spot errors and monitor cash flow.
  • Track Property Basis: Keep digital copies of closing documents and receipts for major home upgrades or rental property improvements. You will need these to calculate your cost basis accurately when selling.
  • Document Retention: Store tax records, receipts, and supporting documents in a secure, organized system. As a general rule, retain records supporting tax returns for at least 3 to 7 years.

Please comment or send an email if you have any questions.

Joe Baker, CFP®

Baker Asset Management, LLC

joebaker@bakerassetmanagement.com
HSAs vs. FSAs: Key Differences and Tax Strategies Every Saver Should Know

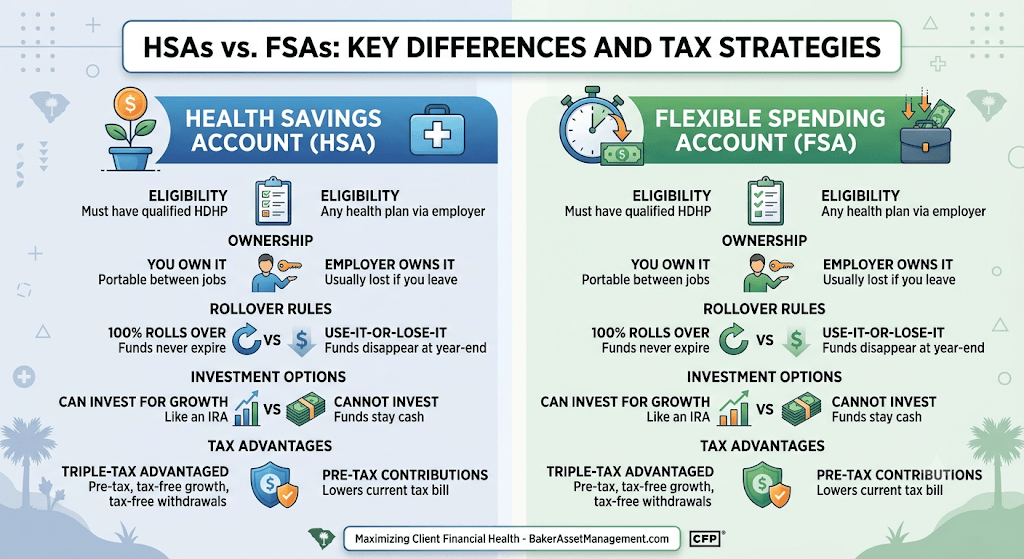
Back in May, I broke down the powerful wealth-building advantages of Health Savings Accounts (HSAs). While that post focused strictly on HSAs, today I want to compare them directly with Flexible Spending Accounts (FSAs). Both accounts allow you to pay for qualified medical expenses using tax-free dollars, but their underlying rules governing ownership, rollover capabilities, and investment growth potential make them vastly different financial tools.

Understanding how to leverage each account—and navigating the updated limits—can significantly lower your annual tax bill while building a dedicated reserve for future medical costs.

HSAs vs. FSAs At-a-Glance

While both accounts deliver immediate tax relief, their structure and long-term utility differ substantially:

FeatureHealth Savings Account (HSA)Flexible Spending Account (FSA)
Health Plan RequirementMust be enrolled in a qualified High Deductible Health Plan (HDHP).Available with most employer-sponsored health plans.
2026 Contribution Limit$4,400 (Self-Only) / $8,750 (Family)$3,400 per employee
Catch-Up Contribution (Age 55+)Additional $1,000 annuallyNot applicable
Account Ownership & PortabilityYou own it. Retained if you change jobs or retire.Employer owns it. Generally lost upon job departure.
Unused Funds Rule100% Roll-Over. Balances accumulate indefinitely.Use-It-or-Lose-It. Subject to carryover caps or grace periods.
Investment OptionsFunds can be invested in stocks, bonds, and mutual funds.Cash-only holding account (no investment component).

The Triple-Tax Advantage of the HSA: The Ultimate Stealth Wealth Tool

For taxpayers looking to maximize tax efficiency, an HSA is often superior to traditional retirement accounts due to its unique triple-tax advantage:

  1. Tax-Deductible / Pre-Tax Contributions: Contributions made via payroll deduction reduce your gross income (and bypass FICA taxes) or can be claimed as a deduction on your income tax return.
  2. Tax-Free Growth: Capital gains, dividends, and interest generated inside an HSA grow completely free of federal and state income taxes.
  3. Tax-Free Withdrawals: Distributions used for qualified medical expenses—ranging from doctor copays to dental care and prescription eyewear—are tax-free at any age.

Strategic Retirement Angle: Once you reach age 65, an HSA functions similarly to a Traditional IRA. You can withdraw funds for non-medical expenses subject to standard income tax without penalty. However, if used for medical expenses in retirement, distributions remain 100% tax-free.

Navigating the FSA “Use-It-or-Lose-It” Trap

Flexible Spending Accounts are valuable employer-provided benefits, but they carry strict timeline constraints. If you do not spend your allocated FSA dollars within the plan year, you risk forfeiting those funds back to your employer.

Employers typically choose one of two relief mechanisms allowed by the IRS:

  • The Carryover Provision: Employers may allow employees to carry over up to $680 of unused 2026 FSA funds into 2027.
  • The Grace Period Provision: Employers can grant up to 2.5 additional months (typically until March 15th) following the end of the plan year on December 31st to spend remaining funds.

Note: Employers are permitted to offer either the carryover option OR the grace period, but not both.

Actionable Tax Strategies for Individuals and Business Owners

1. The HSA “Shoebox Strategy” (Long-Term Compounding)

If your cash flow permits, pay current out-of-pocket medical expenses using external cash rather than tapping your HSA. Save and digitize every medical receipt. Because the IRS imposes no time limit on when you must reimburse yourself from an HSA, you can let your HSA balance compound tax-free in growth investments for 10 to 20 years, then reimburse yourself tax-free in retirement using your saved receipts.

2. Confirm HDHP Qualification Rules for 2026

To contribute to an HSA in 2026, your health insurance plan must meet specific minimum deductible thresholds:

  • Self-Only Minimum Deductible: $1,700 (Max Out-of-Pocket: $8,500)
  • Family Minimum Deductible: $3,400 (Max Out-of-Pocket: $17,000)

3. Utilize a Limited-Purpose FSA Alongside an HSA

If your employer offers a Limited-Purpose FSA (restricted strictly to vision and dental expenses), you can contribute to both an HSA and an FSA simultaneously. This preserves your full HSA balance for long-term investment while funding predictable vision and dental costs with pre-tax FSA dollars.

4. Maximize Contributions Before the Tax Filing Deadline

You have until the federal tax filing deadline (typically April 15th) of the following year to make prior-year HSA contributions.

The Bottom Line

While an FSA is a practical tool for funding immediate, predictable healthcare costs within a single calendar year, an HSA is a powerful wealth-building instrument that should be integrated directly into your long-term retirement and tax strategy.

Please comment or send an email if you have any questions.

Joe Baker, CFP®

Baker Asset Management, LLC

joebaker@bakerassetmanagement.com
What You Need to Know If You Inherit an IRA

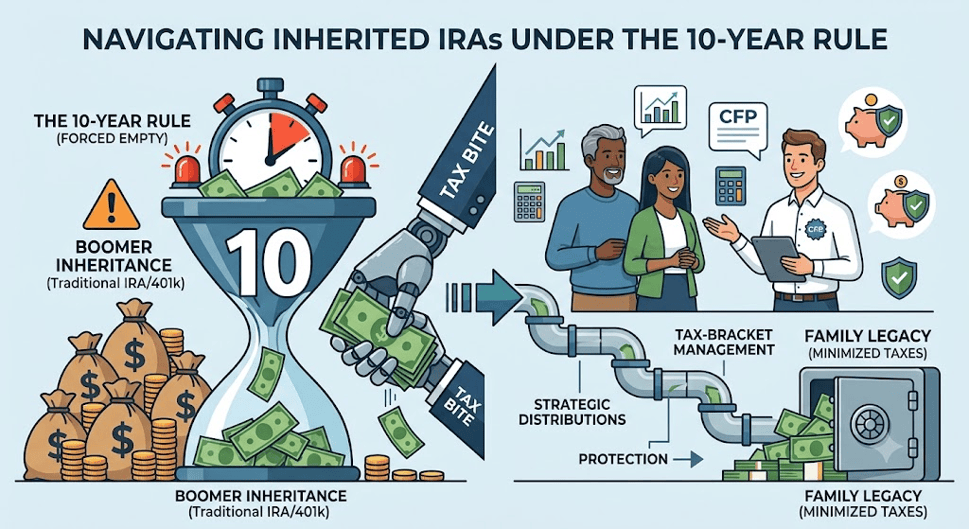
The Great Wealth Transfer is officially underway. Over the next two decades, Baby Boomers are projected to pass down tens of trillions of dollars to Gen X and Millennial heirs. A significant portion of this wealth is sitting inside tax-deferred retirement accounts—specifically Traditional IRAs and 401(k)s.

While receiving an inheritance can be life-changing, inheriting a retirement account comes with a maze of tax laws. Following the SECURE Act and finalized IRS regulations, the rules governing inherited IRAs have fundamentally changed. If you expect to leave or receive an inherited IRA, understanding these rules is critical to avoiding a massive tax bite.

The Death of the “Stretch IRA”

For decades, non-spouse beneficiaries (such as adult children or grandchildren) enjoyed a tax perk known as the Stretch IRA. Heirs could take small, required minimum distributions (RMDs) calculated over their own life expectancies. This allowed the remaining account balance to grow tax-deferred for 30, 40, or even 50 years.

Congress effectively eliminated the Stretch IRA for most non-spouse beneficiaries. Instead, most heirs are now subject to the 10-Year Rule, which requires the entire account balance to be depleted by December 31st of the 10th year following the original owner’s death.

How the 10-Year Rule Works (And the “RMD Catch”)

How you manage an inherited Traditional IRA over that 10-year window depends heavily on whether the original account owner had reached their Required Beginning Date for RMDs (currently age 73) before passing away:

Owner’s Status at PassingDistribution Requirement for Non-Spouse BeneficiaryTax Impact
Died BEFORE Age 73Flexible 10-Year Window: No mandatory annual withdrawals are required in years 1–9. The entire account must simply be emptied by the end of Year 10.Income tax is owed on withdrawals in the year they are taken.
Died ON or AFTER Age 73Mandatory Annual RMDs: You must take annual RMDs in years 1–9 based on your life expectancy and fully empty the account by Year 10.Income tax is owed on each annual distribution.
Inherited Roth IRA10-Year Draining Rule: Account must be emptied by Year 10, but no annual RMDs are required during years 1–9 regardless of the owner’s age.100% Tax-Free distributions (assuming the Roth account met the 5-year holding rule).

Note on Exceptions: Surviving spouses, minor children of the account owner, disabled or chronically ill individuals, and beneficiaries not more than 10 years younger than the deceased qualify as “Eligible Designated Beneficiaries” and may still use lifetime distribution rules under specific conditions.

The “Tax Bomb” Risk for Heirs

The biggest trap of the 10-Year Rule is the unexpected tax bump.

Gen Xers and Millennials inheriting IRAs are often in their peak earning years (ages 40 to 60). Adding $50,000 to $100,000+ per year in taxable IRA distributions on top of a high salary can push heirs into significantly higher federal and state tax brackets. Furthermore, waiting until Year 10 to withdraw a lump sum can result in a massive single-year tax liability.

Don’t Forget the State Tax Twist

While federal rules dictate when you must take distributions, state laws determine how much extra cut the government takes. State income taxes vary drastically across the country, making location a critical factor in your withdrawal strategy. For instance, heirs living in Texas pay 0% state income tax on inherited IRA distributions, leaving only federal tax to manage. In contrast, beneficiaries in California face steep top income tax rates (up to 13.3%), which can severely compound the tax hit on forced 10-year withdrawals. States like South Carolina (top rate around 6.2%) and New York fall in between—neither state charges a separate inheritance tax, but both tax traditional IRA distributions as ordinary state income (though both offer specific state tax exemptions for seniors that may apply under certain conditions). If you or your heirs reside in a high-tax state, tax-bracket management becomes doubly important.

Smart Strategies to Minimize the Tax Hit

  1. Stagger Withdrawals Intentionally: Rather than taking nothing for nine years and triggering a massive tax bill in Year 10, spread distributions evenly over the decade to keep yourself within lower tax brackets.
  2. Utilize Low-Income or Gap Years: If you plan to retire, take a sabbatical, or experience a lower-income year during the 10-year window, schedule larger inherited IRA withdrawals during those specific years.
  3. Proactive Planning for Account Owners (Lifetime Roth Conversions): If you are currently planning your estate, consider executing systematic Roth conversions during your lifetime. Paying the tax now at your current tax bracket allows your heirs to inherit tax-free growth and tax-free withdrawals.

The Bottom Line

Inheriting an IRA can provide a significant boost to your long-term financial security, but without a coordinated strategy, income taxes can erode a substantial portion of your family’s legacy.

Whether you are looking to update your current estate plan or have recently inherited an account, consulting with a financial advisor can help ensure you keep as much of that wealth as possible.

Please comment or send an email if you have any questions.

Joe Baker, CFP®

Baker Asset Management, LLC

joebaker@bakerassetmanagement.com
Updating Your Estate Plan: Why Naming a Trust as Your IRA Beneficiary Needs a Checkup

If you created a trust years ago to pass your IRA to children or grandchildren, the ground beneath your estate plan has fundamentally shifted.

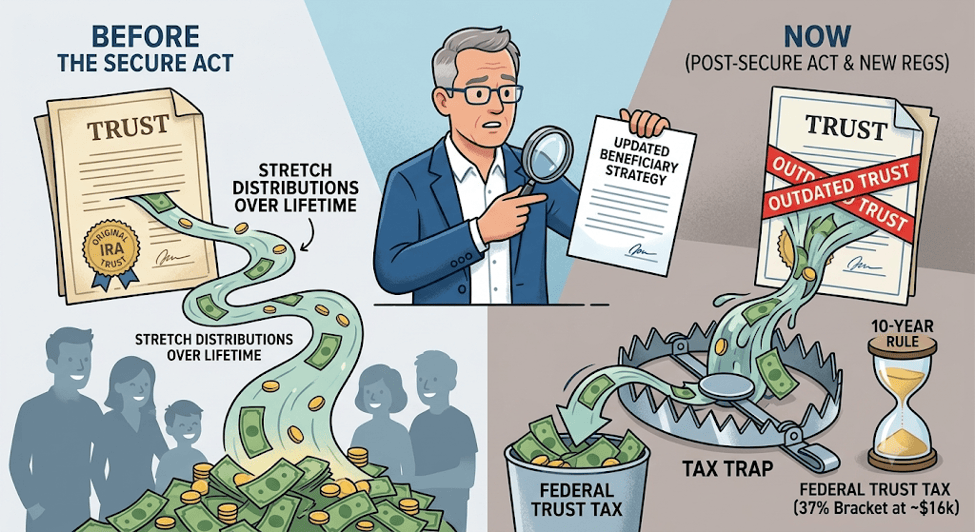
Under older tax law, naming a trust as your IRA beneficiary allowed your heirs to “stretch” distributions—and the tax burden—gradually over their lifetimes. Today, under the post-SECURE Act framework, those rules have been replaced with strict deadlines that could trigger unexpected tax bills if left unchecked.

The Problem: Compressed Trust Tax Brackets

Many older trusts were drafted as “accumulation trusts,” which allow the trustee to hold IRA distributions inside the trust for asset protection. While protection remains valuable, the tax cost has skyrocketed:

  • Individual Tax Brackets: An individual doesn’t reach the top 37% federal marginal tax bracket until their income exceeds $600,000 (or over $750,000 for married couples filing jointly).
  • Trust Tax Brackets: A trust hits the top 37% tax bracket at just over $16,000 of retained income.

If your inherited traditional IRA pushes hundreds of thousands of dollars into a trust over a short period, the IRS takes a significantly larger bite than if the funds were distributed directly or managed through an updated structure.

The 10-Year Rule Factor

Most non-spouse beneficiaries must now fully deplete an inherited IRA by December 31 of the 10th year following the owner’s death. Furthermore, if you pass away after reaching your Required Beginning Date (RBD), your beneficiaries are required to take annual distributions in years 1 through 9 before liquidating the balance in year 10.

Without proactive coordination, forcing large distributions into an outdated trust structure can needlessly drain family wealth.

Strategic Solutions to Consider

  1. Review Conduit vs. Accumulation Language: Ensure trust provisions match current legal definitions for “see-through” status while balancing creditor protection against tax drag.
  2. Lifetime Roth Conversions: Converting traditional IRA assets to a Roth IRA during your lifetime allows the account to pass tax-free to heirs. Inherited Roth IRAs are still subject to the 10-year rule, but distributions come out completely tax-free.
  3. Re-evaluate Direct Beneficiary Designations: For mature heirs who do not require legal protection, direct designations may be far more tax efficient.

If you haven’t reviewed your estate plan and beneficiary designations recently, now is the time to align them with current tax law and your overall financial goals.

Please comment or send an email if you have any questions.

Joe Baker, CFP®

Baker Asset Management, LLC

joebaker@bakerassetmanagement.com