
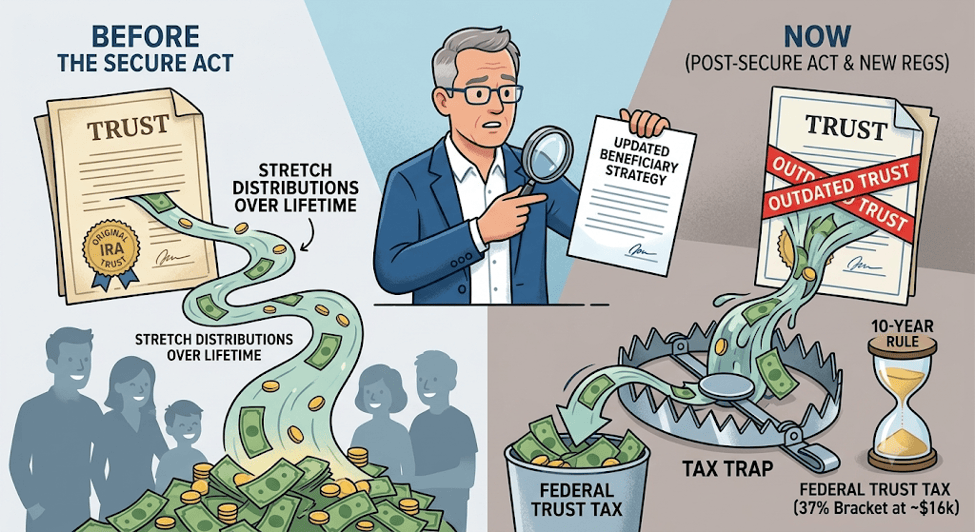
If you created a trust years ago to pass your IRA to children or grandchildren, the ground beneath your estate plan has fundamentally shifted.
Under older tax law, naming a trust as your IRA beneficiary allowed your heirs to “stretch” distributions—and the tax burden—gradually over their lifetimes. Today, under the post-SECURE Act framework, those rules have been replaced with strict deadlines that could trigger unexpected tax bills if left unchecked.
The Problem: Compressed Trust Tax Brackets
Many older trusts were drafted as “accumulation trusts,” which allow the trustee to hold IRA distributions inside the trust for asset protection. While protection remains valuable, the tax cost has skyrocketed:
- Individual Tax Brackets: An individual doesn’t reach the top 37% federal marginal tax bracket until their income exceeds $600,000 (or over $750,000 for married couples filing jointly).
- Trust Tax Brackets: A trust hits the top 37% tax bracket at just over $16,000 of retained income.
If your inherited traditional IRA pushes hundreds of thousands of dollars into a trust over a short period, the IRS takes a significantly larger bite than if the funds were distributed directly or managed through an updated structure.
The 10-Year Rule Factor
Most non-spouse beneficiaries must now fully deplete an inherited IRA by December 31 of the 10th year following the owner’s death. Furthermore, if you pass away after reaching your Required Beginning Date (RBD), your beneficiaries are required to take annual distributions in years 1 through 9 before liquidating the balance in year 10.
Without proactive coordination, forcing large distributions into an outdated trust structure can needlessly drain family wealth.
Strategic Solutions to Consider
- Review Conduit vs. Accumulation Language: Ensure trust provisions match current legal definitions for “see-through” status while balancing creditor protection against tax drag.
- Lifetime Roth Conversions: Converting traditional IRA assets to a Roth IRA during your lifetime allows the account to pass tax-free to heirs. Inherited Roth IRAs are still subject to the 10-year rule, but distributions come out completely tax-free.
- Re-evaluate Direct Beneficiary Designations: For mature heirs who do not require legal protection, direct designations may be far more tax efficient.
If you haven’t reviewed your estate plan and beneficiary designations recently, now is the time to align them with current tax law and your overall financial goals.
Please comment or send an email if you have any questions.
Joe Baker, CFP®
Baker Asset Management, LLC
joebaker@bakerassetmanagement.com

