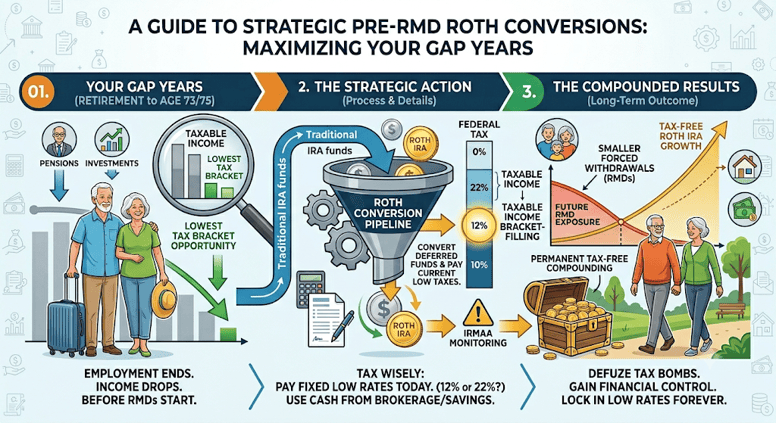
The Bottom Line: Waiting until age 73 or 75 to let the government dictate your retirement withdrawals is a costly tax mistake. By executing strategic Roth IRA conversions during your early retirement “gap years,” you can systematically minimize your Traditional IRA balance, shrink future Required Minimum Distributions (RMDs), and lock in historically low tax rates.
The Hidden Tax Trap of Retirement
Many retirees believe that once they stop working, their tax planning is finished. Unfortunately, a major tax trap awaits in your 70s: Required Minimum Distributions (RMDs). If you have spent decades building a substantial nest egg in a tax-deferred Traditional IRA or 401(k), the IRS will eventually force you to withdraw specific percentages annually, regardless of whether you need the cash. These forced distributions are taxed as ordinary income and can easily push you into a significantly higher marginal tax bracket, trigger higher Medicare premiums (IRMAA), and increase the taxation of your Social Security benefits.
The Window of Opportunity: Your “Gap Years”
The optimal time to defuse this tax bomb is during your “gap years”, the golden window after you retire but before your forced RMDs begin. During this period, your earned income drops off, frequently dropping you into the lowest tax brackets you will see for the rest of your life.
The core strategy is simple: Bracket Filling. You intentionally withdraw money from your Traditional IRA, convert it into a Roth IRA, and pay ordinary income tax on that amount today. The goal is to maximize the amount converted at the lowest current marginal rates (the 10% and 12% brackets, or up to the 22% bracket depending on your wealth targets), ensuring that the converted funds grow tax-free and can be withdrawn completely tax-free later in life.
2026 Federal Income Tax Brackets (Marginal Rates)
To implement this effectively, we must evaluate the current federal tax structure. Below are the key ordinary income brackets for the 2026 tax year:
- 10% Bracket: Single: $0 to $12,400 | Married Filing Jointly: $0 to $24,800
- 12% Bracket: Single: $12,401 to $50,400 | Married Filing Jointly: $24,801 to $100,800
- 22% Bracket: Single: $50,401 to $105,700 | Married Filing Jointly: $100,801 to $211,400
- 24% Bracket: Single: $105,701 to $201,775 | Married Filing Jointly: $211,401 to $403,550
Here’s a few examples to illustrate this strategy.
Scenario A: The Single Filer
Consider a retired single filer with a guaranteed taxable income of $35,000 from a pension and dividends. This lands them squarely within the 12% bracket ($12,401 to $50,400).
- The Opportunity: The top of the 12% bracket is $50,400.
- The Calculation: $50,400 − $35,000 = $15,400 of available “headroom.”
- The Action: Convert exactly $15,400 from their Traditional IRA to a Roth IRA.
- The Result: The entire $15,400 is taxed at a modest 12%. This fund is now insulated from future tax increases, and the Traditional IRA balance is reduced by $15,400, shrinking future RMD exposure.
Scenario B: Married Filing Jointly
Consider a retired couple filing jointly with a combined base taxable income of $70,000 from investments and social security. They are currently in the 12% bracket ($24,801 to $100,800).
- The Opportunity: The top of the 12% bracket is $100,800.
- The Calculation: $100,800 − $70,000 = $30,800 of available headroom.
- The Action: Convert exactly $30,800 from their Traditional IRA to their Roth IRA.
- The Result: They lock in a 12% federal tax rate on $30,800. If they waited until RMDs kicked in alongside Social Security, their forced distributions could easily push their taxable income past $100,800, forcing those same dollars to be taxed at 22% or higher.
Critical Guardrails
While the numbers are highly compelling, Roth conversions require precise execution. To ensure compliance and optimize the financial impact, keep these rules in mind:
- Pay Taxes from Cash, Not the IRA: To maximize the mathematics of a conversion, the income tax generated by the conversion should be paid using cash from non-retirement checking or brokerage accounts. Using IRA assets to pay the tax reduces the compounding power of your tax-free bucket.
- Watch the IRMAA Thresholds: Roth conversions increase your Adjusted Gross Income (AGI). If your AGI crosses specific thresholds, it can trigger Medicare Part B and Part D premium surcharges (IRMAA) two years later. Always analyze this boundary before converting assets.
- The 5-Year Rule: Converted earnings and principal must remain in the Roth IRA for at least five years (or until you reach age 59½) to be withdrawn tax-free. Because this strategy targets pre-RMD retirees, the time horizon aligns perfectly, but meticulous record-keeping is vital.
Summary & Next Steps
Roth conversions are not a one-time event; they are a multi-year, proactive tactical strategy. By intentionally paying tax at a known, lower rate today, you seize control of your lifetime tax liability and build a flexible, tax-free financial legacy. Every individual situation requires custom financial projection modeling to guarantee that a conversion does not inadvertently push you into an unfavorable tax cliff.
Please comment or send an email if you have any questions.
Joe Baker, CFP®
Baker Asset Management, LLC
joebaker@bakerassetmanagement.com