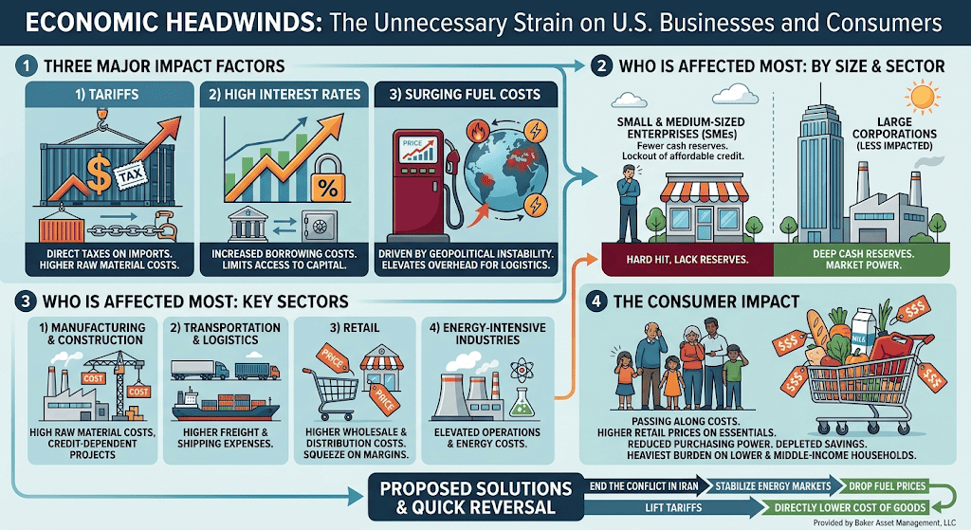
The U.S. economy has shown remarkable resilience, largely buoyed by a historic surge in productivity and investment driven by the artificial intelligence revolution. However, that underlying momentum is now in serious jeopardy due to three major self-inflicted pressures: high interest rates, trade tariffs, and surging inflation driven by skyrocketing fuel costs. These conditions create an unnecessary drag on economic expansion, but they could be reversed quickly by ending the conflict in Iran to stabilize global energy markets and removing trade tariffs.
Here is a breakdown of how these factors are impacting the market and who is bearing the brunt of the burden:
The Core Economic Pressures
Tariffs: Tariffs act as a direct tax on imported goods, raising the cost of raw materials and inventory. Businesses are forced to either absorb these losses or pass them on to consumers, driving inflation higher.
Surging Fuel Costs: Geopolitical conflict—specifically the war in Iran—has pushed fuel and energy prices up rapidly. This disproportionately increases overhead for any business reliant on physical operations, shipping, or manufacturing.
High Interest Rates: Elevated borrowing costs mean that securing capital for business expansion, equipment upgrades, or day-to-day cash flow management is now prohibitively expensive.
Who is Affected the Most?
By Business Size: Small and medium-sized enterprises (SMEs) bear the heaviest load. Unlike massive multinational corporations, SMEs lack the deep cash reserves and market power to absorb sustained cost increases, while high interest rates restrict their access to affordable working capital.
By Sector:
Manufacturing & Construction: Heavily reliant on raw materials subject to tariffs and credit-dependent for project financing.
Transportation & Logistics: Surging fuel costs act as an immediate hit to margins for any firm moving physical goods.
Retail: Retailers are squeezed on both ends—paying higher wholesale and transport costs while selling to consumers whose discretionary budgets are pinched by inflation.
By Consumer (Lower and Middle-Income Households): Ultimately, these corporate cost pressures spill over onto everyday households. As businesses pass along tariff taxes, elevated freight charges, and higher borrowing expenses, retail prices rise on essential goods like food, energy, and household staples. Lower and middle-income families—who spend a significantly larger portion of their take-home pay on basic necessities—bear the heaviest burden, facing reduced purchasing power and depleted savings as living costs climb.
The Solution
The clearest, most efficient path to economic relief requires straightforward policy changes. Ending the conflict in Iran would immediately ease energy market volatility and lower fuel prices at the pump, while lifting tariffs would directly reduce input costs for businesses and bring relief to consumer budgets across the board. By eliminating these primary drivers of inflation, the Federal Open Market Committee (FOMC) would have the leeway needed to lower interest rates without the risk of runaway prices, providing immediate relief to borrowing businesses and the broader economy.
Please comment or send an email if you have any questions.
The Federal Open Market Committee (FOMC) just cut its benchmark interest rate, known as the federal funds rate, by a quarter-point (0.25%), bringing the target range to between 4.00% and 4.25%.
This can be considered a continuation of an easing cycle (period of lowering interest rates) that started back in September of 2024 but had been paused at the beginning of this year due to the uncertainty of how the new administration’s trade and immigration policies were going to affect prices and unemployment.
Since then, the data has shown that inflation has picked up mainly due to tariffs but not as much as expected. Our businesses are not passing on the full cost of the tariffs to their customers….for now. However, the labor market has weakened significantly in that same time span. Typically, when inflation picks up, raising rates helps cool it down. When unemployment increases, lowering rates is the standard response to help support employment. This dilemma of rising inflation and rising unemployment, aka stagflation, put the FOMC in a quandary for most of 2025.
Ultimately, at their last meeting, the FOMC chose to prioritize the battle against rising unemployment and restarted their easing cycle by cutting rates.
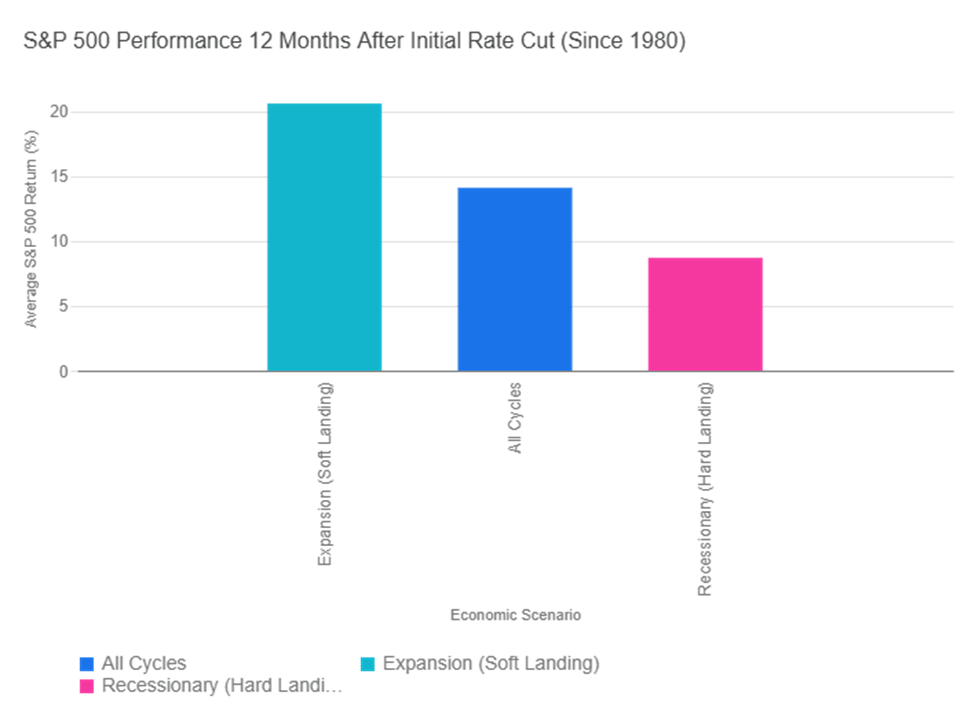
So, how will this affect the stock market? Historically, the market has performed well when interest rates are cut. The graph below illustrates the historical performance of the S&P 500 Index in the 12 months following the Federal Reserve’s first interest rate cut in a new cycle (since 1980). The returns vary significantly based on the underlying economic conditions, but they have always been good for stocks.
If we consider the start of the easing cycle to be September of 2024, we are now at a full year following the first rate cut. Interestingly enough, the S&P 500 has returned about 15.3% for that period, which coincides with its historical returns, as seen on the graph.
Does that mean we are due for a pullback? Not necessarily. If we continue on the trajectory of the soft landing that we were headed for at the beginning of this year, stock prices could continue to move higher. But, if inflation persists and unemployment continues to rise, we could be heading for a downturn.
The S&P 500 is also approaching a significant milestone: 3 years of consecutive double-digit returns. Stringing together three or more years of positive double-digit returns is rare but it happens.
Period (Start Year)
Length of Streak (Years)
Early 1930s (e.g., 1933–1936)
4
World War II / Post-War (e.g., 1942–1945)
4
Post-War Boom (e.g., 1949–1955)
7
Mid-1960s (e.g., 1963–1967)
5
1990s Tech Boom (1995–1999)
5
Post-Financial Crisis (e.g., 2012–2014)
3
Post-Pandemic Era (2019–2021)
3
We will see if stocks can make history as we head into the home stretch of 2025.
Please comment or send an email if you have any questions.
The Fed, specifically, the Federal Open Market Committee (FOMC), is not having their monthly meeting this August but many of the members are gathering this week in Jackson Hole, Wyoming with a bunch of financial big shots for their annual summer conference. The investment world will be tuning in to get any hints on what they plan to do with interest rates when they meet in September. So, I thought it would be a good time to review what happens when the Federal Reserve changes interest rates.
When the FOMC changes interest rates, they aren’t changing every rate out there. They are only changing the Federal Funds Rate (FFR). This is the rate that banks charge each other for overnight loans. Modifying this rate is one of the Fed’s tools that they use to maintain a healthy economy. They lower it if they feel the economy is slowing and raise it if the economy is heating up too quickly.
For example, if unemployment is trending up, the Fed would be more inclined to lower rates. If consumer prices (inflation) are going up at a higher rate than expected, they would consider raising rates to slow the increase.
Although you probably have never heard of the Fed Funds Rate, it does influence many of the interest rates that you are familiar with and interact with every day. The FFR is the base that the cost of money in the banking system is built upon. In fact, the prime rate, which almost all bank loans are based off of, is derived from the FFR and is typically 3% higher than the FFR.
Now, let’s take a look at the table below that shows what is expected with various rates and other economic factors when the FOMC changes the Fed Funds rate:
When FOMC raises the FFR, plan on:
When FOMC lowers the FFR, plan on:
Mortgage rates
Higher
Lower
Car loan rates
Higher
Lower
CD rates
Higher
Lower
Money market rates
Higher
Lower
Credit card rates
Higher
Lower
Business profits
Lower
Higher
Stock market
Lower
Higher
Consumer spending
Lower
Higher
Home sales
Lower
Higher
These expected changes don’t happen overnight. It takes time for the Fed’s actions to trickle down to other rates and markets. For instance, if the Fed raises the FFR, the stock market might not go down until rates are high enough in other investments, such as bonds or CDs, to justify the shift from stocks to those other investment options.
This should give you a better understanding of what is happening when you hear that the Fed is changing interest rates.
Please comment or send an email if you have any questions.
Stocks stayed in the green for the third month in a row, climbing a wall of worry built mainly from tariffs. The index reached a series of new all-time highs, driven by strong performances in Q2 by our home-grown big technology companies.
For the month of July, the S&P 500 rose a respectable 2.2%, even with a pretty big drop in the last days of the month. That beat the historical July average of 1.28% and now takes the index to a year-to-date return of 8.50%.
The usually quiet summer months for stocks are anything but this year. With most of the Q2 earnings posted already, the stock market is now going to be fixated on trade policy, the job market, inflation, and interest rates. Each of these four elements can provide a boost or a bust for stocks over the next month. If the new tariffs that were recently implemented stay in place, inflation is going to continue higher as it has over the past few months. Layoffs from both the public and private sectors are now showing up in the data as the effects of DOGE, trade, and immigration policies take hold. Companies are embracing AI to reduce payroll as well. The Federal Reserve is more likely to cut interest rates by their September meeting (no meeting in August) now with the recent poor jobs data most likely outweighing the rising inflation data.
The good news is, as I have said many times this year, the economy can get back on track if we get rid of the tariffs and instead negotiate trade deals with our allies that are beneficial to both parties. This would especially help our small businesses that can’t afford to pay these levies and still remain viable. It would also benefit those that are in the lower- and middle-income tiers that can’t afford the price increases that our companies will have to pass on to their customers due to the tariffs.
Historically, August has been a pretty boring month for stocks, with an average return of about 0.5%. I think this August could be a little more exciting, to say the least.
Take a look at the Outlook section below to see what events could move the markets over the short term.
Bond prices were flat to slightly lower during July as the economy began to show signs of slowing, increasing the potential for short-term interest rates to be lowered by the Federal Reserve. Although the Federal Reserve held rates unchanged after their July meeting, sentiment increased sharply for a cut by the time that they meet again in September due to the poor jobs report that came out just after the Fed concluded their meeting.
While there is a recovery in market sentiment after a temporary pause on new tariffs, concerns over the long-term impact of trade policies and geopolitical risks still persist. This kind of uncertainty can drive investors toward safer assets like bonds, particularly government bonds, increasing demand and pushing prices up. We will most likely see this price action continue if the most recent tariffs stay in place for any significant period of time.
The 10-year US Treasury note yield finished higher in July, settling at 4.36%, higher than the 4.23% yield that it was at the beginning of the month. The 30-year bond yield closed out the month at 4.89%, about 12 basis points higher than a month ago.
With all of the uncertainty in the bond market, it is prudent to invest in bonds that mature sooner rather than later. I like bonds with a 12-to-18-month maturity and plan on holding onto them until they do mature.
Savings rates didn’t move much in July. Money market rates and bank savings accounts are averaging only about 0.46% but the best rates can be found at credit unions and online banks with rates approaching 4.5%. It is worth it to do some research here. With rates staying above 4%, I think more money is going to be funneled into the safe havens of money markets and CDs as the stock market rebound is showing signs of fatigue. So, CDs and MMAs continue to be a great place toput your cash and your emergency fund, for now. Knowing this, it makes sense in most situations to put cash that you don’t immediately need into CDs with up to 2-year maturities. For emergency cash, stick to high yielding money market and savings accounts, of which the best are yielding about 4.4%. As always, keep the total under $250,000 per person at any one bank to ensure you are fully covered by the FDIC.
Mortgage rates mirrored other rate categories and had little movement this past month. The expectations were low for any changes in rates by the Federal Reserve, so this was expected. Higher housing inventory continued to put downward pressure on mortgage rates as well. Active listings rose for the 21st consecutive month, but overall inventory remains below pre-pandemic levels. It has become a buyers’ market in most parts of the country, but prices are still historically high and coupled with high mortgage rates, makes home purchases out of reach for many, especially first-time home buyers.
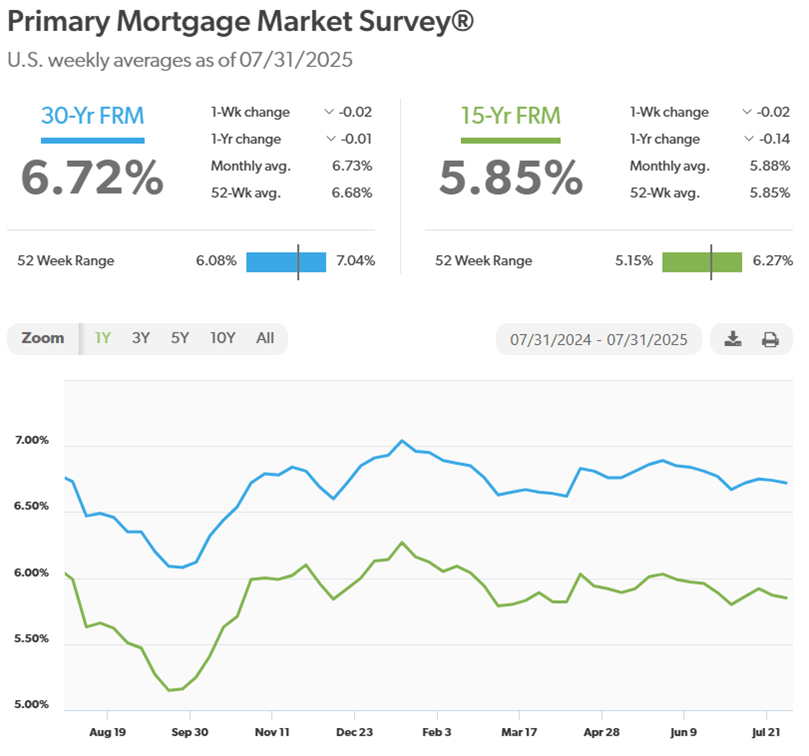
The 30-year fixed rate finished the month at 6.72%, still within the narrow range of 6.5% and 7% that it has been in since October of last year. The trade and immigration policies are causing higher raw materials and labor costs for homebuilders and are starting to show up in new home prices now, making it even harder to afford a new home.
Here is a look at the one-year chart of the 15- and 30-year mortgage rates from Freddie Mac.
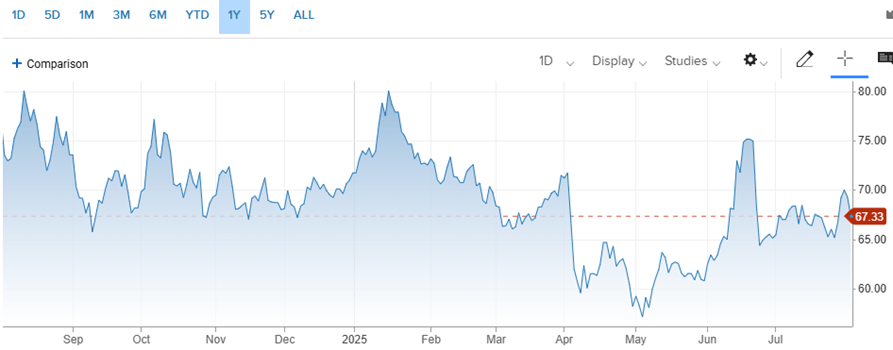
Oil prices were much calmer in July than they were in June of this year. That is, until the last week when oil prices surged due to renewed geopolitical risk causing a disruption in the global oil supply. Specifically, when the U.S. issued a deadline to Russia to end the war in Ukraine, threatening additional sanctions and tariffs on countries that continue to buy Russian oil. This, coupled with the seasonally strong summer demand could keep prices elevated at least through the end of August.
For the month, the price for a barrel of oil closed at $69.26, up from $65.11 at the beginning of July. For the year, it’s down about 3.40%. We certainly don’t want to see oil prices going higher now because that will raise the input costs for companies even higher as the tariffs take hold.
Here’s a look at the one-year chart for U.S. oil:
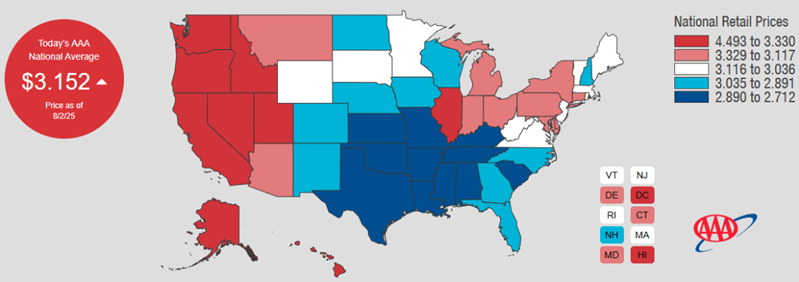
Gasoline prices dipped slightly in July. Regular unleaded gasoline is now averaging $3.15 per gallon, down four cents from last month. However, gas prices could be heading higher in the near future for reasons stated above in the oil prices section. Mississippi has the cheapest gas currently, checking in at $2.71 a gallon. California has the most expensive gasoline at $4.49 per gallon. FYI, a year ago, we were paying $3.48.
Check out the prices at the pump in your area: AAA Gas Prices.
Outlook
Events on the horizon that could move the markets in the near term:
Fed & Inflation: The Federal Reserve had started leaning towards cutting rates even before the bad jobs report came out this past Friday. Cracks have begun to appear in our resilient labor market as layoffs from DOGE and the private sector are reflected in the latest data. Also, inflation is picking up as U.S. companies begin to raise prices to offset the tariffs they are paying on imported goods and raw materials. Higher unemployment and higher prices, aka stagflation, is a tough scenario for the Fed to fight at the same time. Right now, it looks like they need to focus on the labor side of the equation, which would mean to cut rates. However, they have to tread carefully because lower rates combined with tariffs could lead to runaway inflation, which would be devastating to the economy. The ideal situation would be if we cut rates and removed the tariffs. That would help our economy recover and spur growth. I’m still hopeful.
Trump Administration Policies: The trade war is back on the front burner as tariffs are assessed on almost everything that our companies import for the products that they produce. As a reminder, the tariffs that we have been talking about this year are fees that U.S. companies pay our government. I like to think of these tariffs simply as an increase in the corporate tax for our companies. It basically increases the cost of doing business. So, in order for companies to keep the same profit margins pre-tariff, or in the case of many small businesses, to remain profitable at all, they have to either raise the prices that they charge their customers, lower expenses in other areas of their business, or a combination of both. Regardless of which avenue a company chooses, our economy will suffer, especially our small businesses and our lower income population that is already living paycheck to paycheck. As I said last month and will keep saying, the government needs to scuttle this absurd tariff strategy and go back to the drawing board to put together a plan that is realistic and can meet their objectives without damaging so many industries and so many lives. It’s not too late to save our small businesses, keep inflation in check, and get our economy back on track.
The economic stars were aligning beautifully at the beginning of the year for the Federal Reserve to start to gradually lower interest rates in 2025. Then, in February our economy, and much of the world’s economies, were upended with a shock and awe tariff policy by the Trump administration. This, coupled with changing global perceptions of U.S. governance and institutions has forced the Fed to rethink its interest rate strategy. Subsequently, the odds of any rate cuts this year have dropped significantly since the end of 2024.
Here are the main suspects that may keep interest rate higher for the foreseeable future:
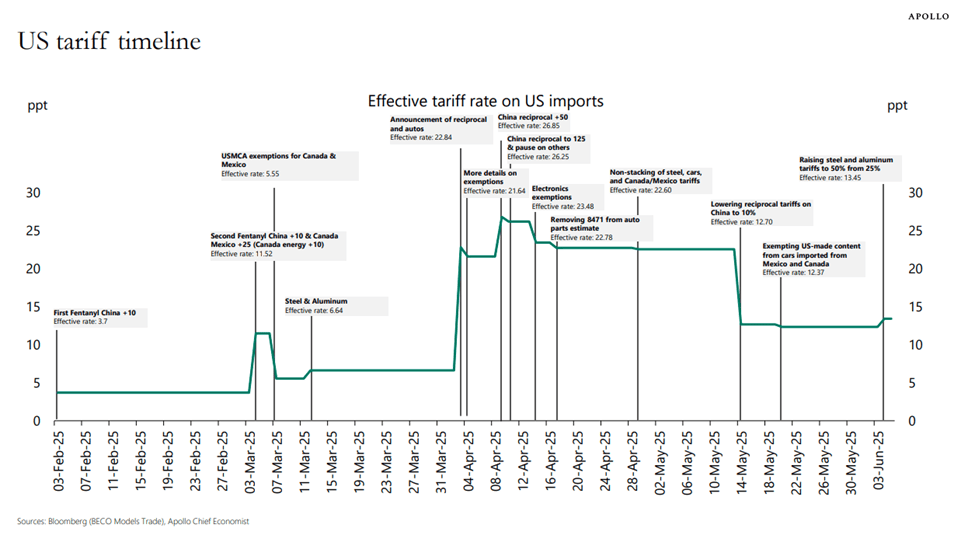
Tariffs: This chart summarizes the effective tariff rate that U.S. companies have had to pay since February:
The green line shows the effective tariff rate from February to June of this year. Prior to February, the U.S. was paying an effective tariff rate of about 2.4%. Currently, we are paying an effective rate of 13.45%. We were as high as 26.85% in April, so we have come off of the highs but still are at a level that is almost 6 times what we were paying at the start of the year. Now, it’s showing up in the prices that we are paying and also in the number of small businesses that have had to lay off workers, suspend operations, or shut down completely. This increase is just not sustainable and higher prices mean rates have to stay high to fend off runaway inflation.
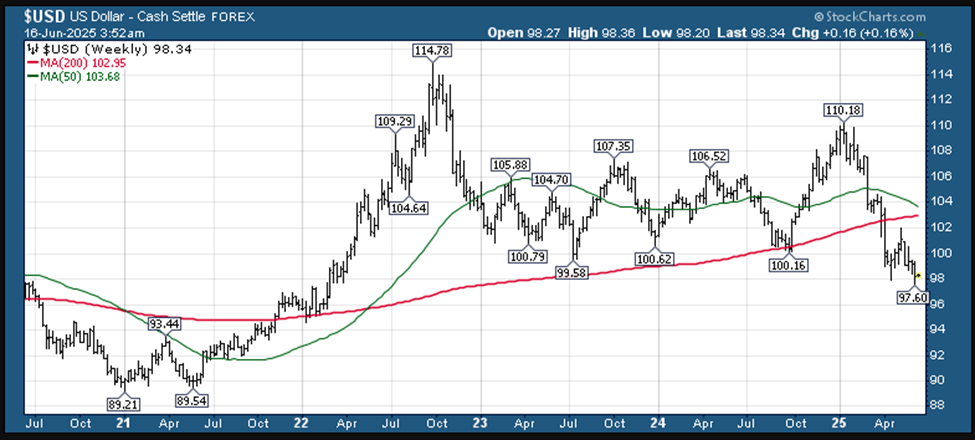
Weaker Dollar: Take a look at this chart of the US Dollar hitting a 3-year low recently.
The black is the dollar index value, the red is its 200-day moving average and the green is its 50-day moving average. There are several factors contributing to the downward pressure on the U.S. dollar, including:
Tariffs and Trade Policy
Global Concerns about U.S. Economic Growth and Recession Risks
Fiscal Deficit and Debt Concerns
Erosion of U.S. Except
In essence, a combination of protectionist trade policies, concerns about the U.S. economy’s resilience, fiscal anxieties, and a shift in global investor sentiment are all contributing to the weakening of the U.S. dollar in 2025. A weaker dollar is inflationary and another reason for the Fed to keep rate elevated.
As I have said before, these issues are self-inflicted, which means they can be resolved quickly if we act now. The longer these policies are in place, the harder it will be to recover from them. Then, the Federal Reserve will have to lower interest rates but for all the wrong reasons, aka a recession.
Please comment or send an email if you have any questions.
Wednesday, January 1st – New Year’s Day: Stock market is closed.
Thursday, January 9th – National Day of Mourning for President Jimmy Carter – Stock market is closed.
Monday, January 20th – Martin Luther King, Jr. Day – Stock market is closed.
Stocks seemed a bit tired in December as the year-end rally flamed out. I can’t blame them. They worked hard all year, and it showed, racking up a 20%+ return for the second year in a row. This hasn’t happened since the 1990’s, which sounds so long ago. The biggest catalysts for this performance were the continuing AI expansion on all fronts as well as inflation dropping substantially over the past year.
For the month, the S&P 500 dropped about 2.5%. However, it was still able to finish the year with a gain of over 23.3%.
Looking ahead, we will have Q4 earnings reports coming out in a few weeks. Also, Trump and his new administration will be coming in later this month. Finally, the Federal Reserve meets at the end of the month in a very cloudy interest-rate environment. Those are some pretty big catalysts that can move the markets, making for a very busy start to the year.
Historically, January has been a good month for stock performance. It has also been a pretty accurate indicator of how stocks will perform the rest of the year. For instance, when stocks have a positive January, full year returns have been positive 77% of the time. Let’s hope history repeats itself this month.
Take a look at the Outlook section below to see what events could move the markets over the short term.
Bond prices flip flopped once again, reflecting the uncertainty in the current interest rate environment. Both corporate and government bond prices fell during the month of December as new inflation data coming in showed that inflation is stickier than anyone expected. Still, the Federal Reserve did cut rates another 25 bps at their December meeting but where they go from here is anyone’s guess, including the Fed.
The 10-year US Treasury note yield finished higher in December, settling at about 4.57%, above the 4.18% that it was at the beginning of the month. The 30-year bond yield closed out the month at 4.79%, higher than the 4.37% that it was a month ago.
Bond investors are waiting with bated breath for the new administration to get in office and lay out their plans for trade and immigration policies, which will heavily influence the direction of bond prices and their yields. We should get some clarity on those issues by the end of the month.
Savings rates either stopped dropping or even went up a little bit this past month. The change in direction is most likely due to the Fed’s talk of slowing down their pace of lowering short-term interest rates in 2025. The direction of where these rates are heading will continue to be uncertain until the inflation picture clears up, which will also depend on the incoming administration’s trade and immigration policies. That said, these rates are pretty good for savers and risk-averse investors. You can get above 4% return on your money currently. So, CDs and MMAs continue to be a great place to put your cash and your emergency fund, for now.
Now, take a look at the top rates for CDs and money market accounts (MMA):
MMA Rates
National Average
High Rate
0.66%
5.00%
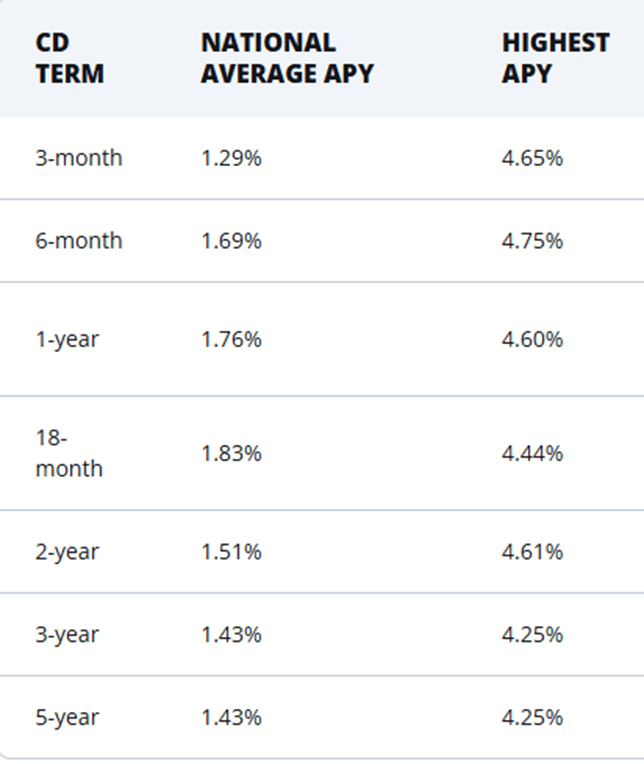
The best 1-year CD interest rate is currently at 4.60%, higher than last month. The best 5-year CD rate right now is around 4.25%, a 25-basis point rise from last month. Once again, MMA and traditional bank savings account rates changed very little from last month.
Savings rates are now in a holding pattern until we get a clearer picture on where interest rates are heading. This isn’t a bad thing, especially for risk-averse investors and savers. Knowing this, it makes sense in most situations to put cash that you don’t immediately need into CDs with up to 2-year maturities. For emergency cash, stick to high yielding money market and savings accounts, which are still yielding around 5%. As always, keep the total under $250,000 per person at any one bank to ensure you are fully covered by the FDIC.
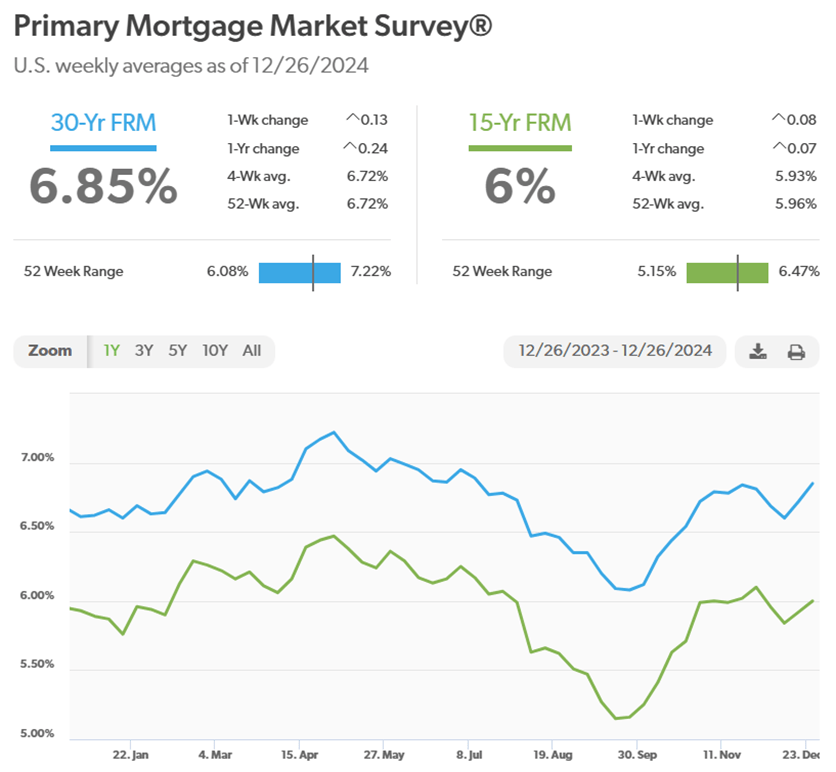
Mortgage rates stayed about the same as a month ago, with the 30-year loan getting ever so close to the 7% mark. Currently, the 30-year rate sits at 6.85%, slightly higher than a month ago, at 6.81%. There is still low inventory, especially for existing homes, so any drop in rates continues to be met with a quick surge in demand.
Oil prices headed higher as hopes of new drilling to lower oil prices were dashed by oil producers’ comments. It seems that these companies like high oil prices (shocking!) and don’t necessarily want to pump more oil. This is a global market that is motivated by profits, so it is difficult to tell them how much oil to produce unless they become operated by the government.
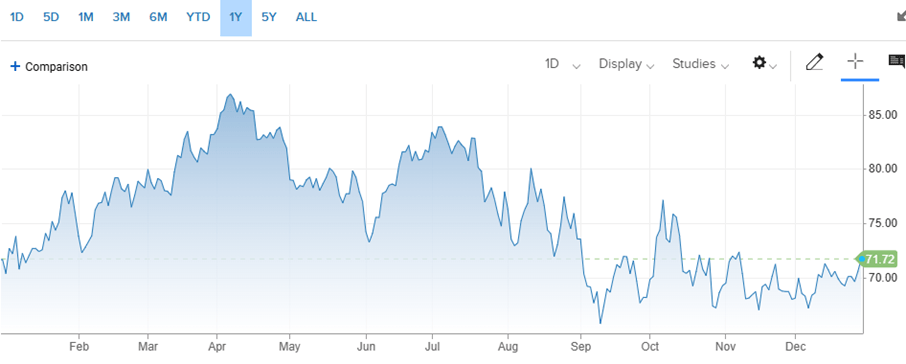
For the month, the price for a barrel of oil closed at $71.72, down from $68.15 at the beginning of December. For the year, prices ended right where they started in January. Getting oil prices below $70 for an extended period of time would help greatly in lowering the overall inflation rate.
Here’s a look at the one-year chart for U.S. oil:
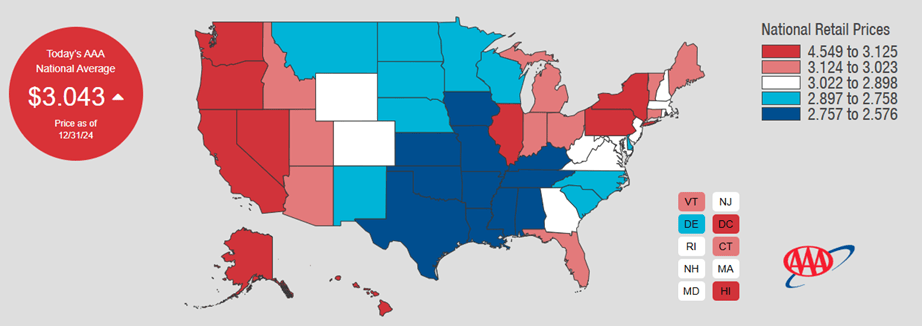
Gasoline prices lagged the rise in oil prices and fell once again in December, albeit barely. Regular unleaded gasoline is now averaging $3.04 per gallon, down from $3.06 last month. Oklahoma has the cheapest gas currently, checking in at $2.58 a gallon. Hawaii has the most expensive gasoline at $4.55 per gallon. FYI, a year ago, we were paying $3.11.
Check out the prices at the pump in your area: AAA Gas Prices.
Outlook
Events on the horizon that could move the markets in the near term:
Fed & Inflation: The Federal Reserve cut interest rates by another 25 basis points at their last meeting of 2024 a few weeks ago. They did state that they might not be as aggressive in cutting rates in 2025 as they thought just a few months ago. I believe they want to let the new administration get settled in to see what policies they plan to implement, particularly tariffs and mass deportation, since these could have a significant impact on inflation. We could know as soon as the end of this month so volatility in the stock and bond markets may be higher than normal this January.
Monday, May 27th, Memorial Day. The stock market is closed.
Stocks finally took a breather in April after a five-month run of positive returns. It’s always healthy for the markets to take a break and consolidate to form another base before moving higher again. So, this break in the upward trend is not surprising, but still not fun to watch if you are long stocks. For the month, the S&P 500 was lower by about 4.20%. For 2024, it is up about 5.57%.
Q1 earnings continue to pour in and, for the most part, have been exceeding expectations, supporting the strong economic data that we have seen so far this year. Of course, earnings reports are looking into the past and it is what companies say about future growth that really moves their stock prices. The good news here is that CEOs are signaling that strong revenue growth should continue, although they are concerned about interest rates staying elevated.
Historically, May has been a month where many traders, or short-term investors, like to prepare their portfolios for the summer. Like the saying goes, sell in May and go away. We will see if that holds true this month.
The Federal Reserve met today and held rates steady once again. They are certainly testing the patience of both stock and bond investors, but so far, their stance hasn’t broken the economic momentum that we have seen over the past year (yet).
Take a look at the Outlook section below to see what events could move the markets over the short term.
Bond prices continue to flip flop, this time heading lower during the month of April. This drop was mainly due to the continued signs of a strong economy and inflation remaining sticky in certain areas, such as food and fuel. This is certainly causing the Fed to rethink when they want to start cutting back on interest rates.
The 10-year US Treasury note yield rose in April, finishing the month at 4.69%, higher than the 4.21% that it was at the beginning of the month. The 30-year bond yield closed out the month at 4.79%, higher than the 4.35% that it was a month ago.
Although the path of interest rates still appears to be in the downward direction, it is not a given. Therefore, bond buyers should continue to focus on bonds with short-term maturities. I would keep maturities under 18 months and just plan on holding these bonds to maturity. That way, you won’t have to worry about selling at a discount if interest rates head higher.
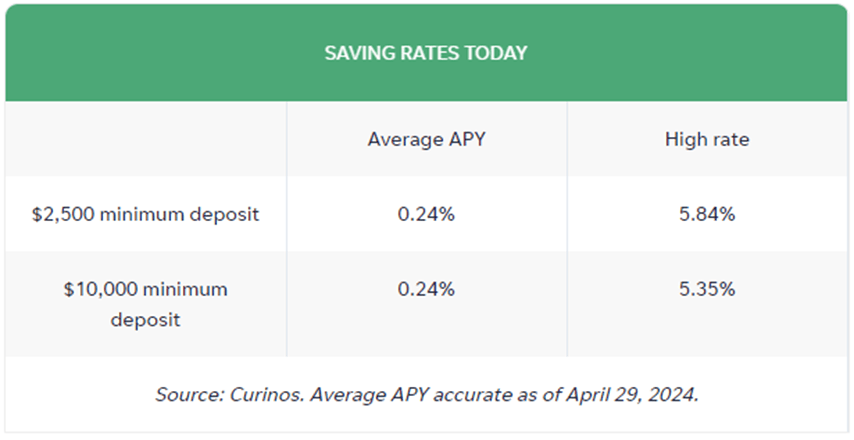
Savings rates stayed about the same in April as compared to March, even as other rates moved higher. But this is expected because savings rates typically follow, but lag, the direction of bond yields. These current savings rates are still quite high, especially with respect to inflation. So, CDs and MMAs continue to be agreat place to park your cash and your emergency fund. These rates continue to be a legitimate alternative to stocks and bonds and will keep pressure on those markets until we see this trend reverse, which looks like it will be happening later in the year than expected.
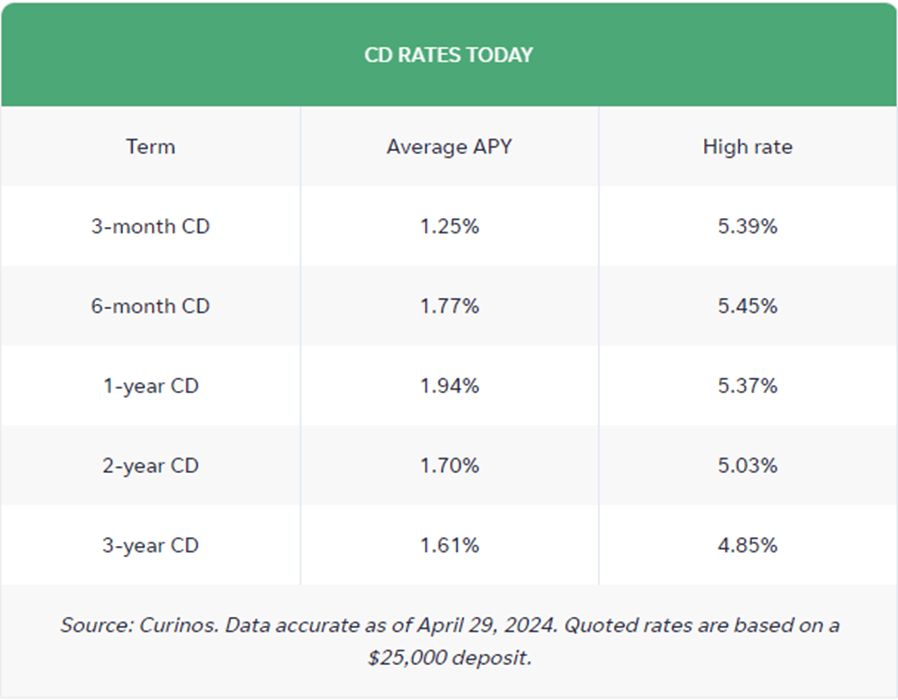
Now, take a look at the top rates for CDs and money market accounts (MMA):
The best 1-year CD interest rate is currently at 5.37%. The best 5-year CD rate right now is around 5.25%. We should see the 5-year CD rate surpass the 1-year rate by the end of the year based on current interest rate trends.
Eventually, savings rates will normalize but not until inflation comes down enough for the Fed to feel comfortable lowering interest rates. That said, I would still put my savings or emergency spending money into short-term CDs, 1 year or less, and reevaluate when they mature. If you would rather have more liquidity, look into an MMA (yielding close to 6% currently). Keep the total under $250,000 per person at any one bank to ensure you are fully covered by the FDIC. CDs and MMAs have become nice alternatives for risk-averse investors and have drawn money away from stocks because of their realtively high rates that carry virtually no risk.
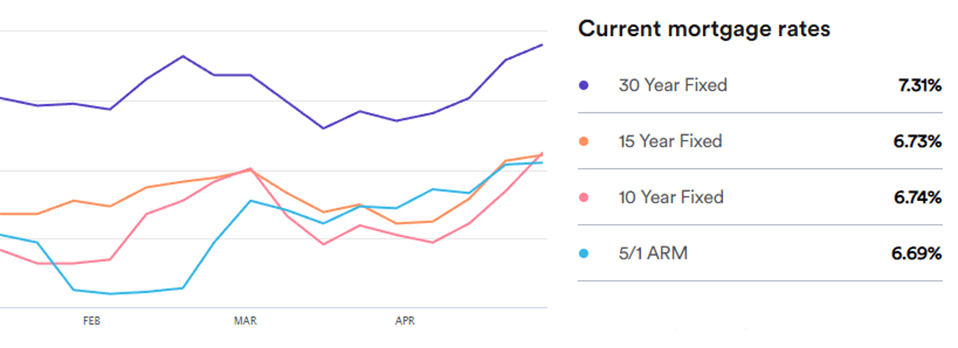
Mortgage rates rose in April as demand picked up most likely due to the spring buying season starting up. Currently, the 30-year rate sits at 7.31%, higher than a month ago, at 7.20%. The housing market continues to be in an unusual situation (high rates, low home inventory, strong demand) and that is making mortgage rates very volatile. Most homeowners either own their home outright or have a mortgage below 3.5%. There is very little incentive to sell a home with rates where they are right now. That will not change until mortgage rates fall. For now, the industry continues to bank on the Federal Reserve to get it squared away.
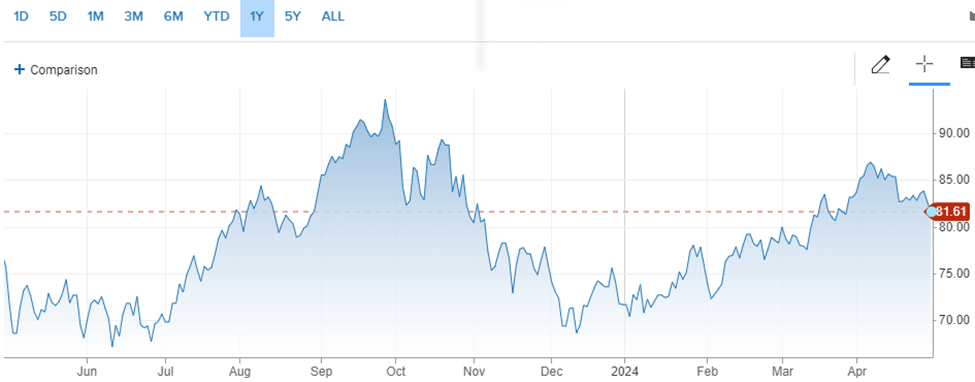
Oilprices broke their upward moving trend and dropped slightly in April, snapping a three-month streak. The drop could be attributed to the strong dollar due to rates in the U.S. staying higher, causing demand for the dollar worldwide, thus making imported oil cheaper.
For the month, the price for a barrel of oil settled at $81.61, down from $83.17 at the beginning of April. For the year, it is up about 14%. Although oil prices fell, they are still high and are a big cause of the stubborn inflation that we are seeing in consumer prices, especially in the food and travel/leisure industries. It could be tough to get prices lower with economies worldwide continuing to chug along at a strong pace. It is a quandary that might be resolved only through demand destruction, or put another way, the cure for high oil prices is high oil prices.
Here’s a look at the one-year chart for U.S. oil:
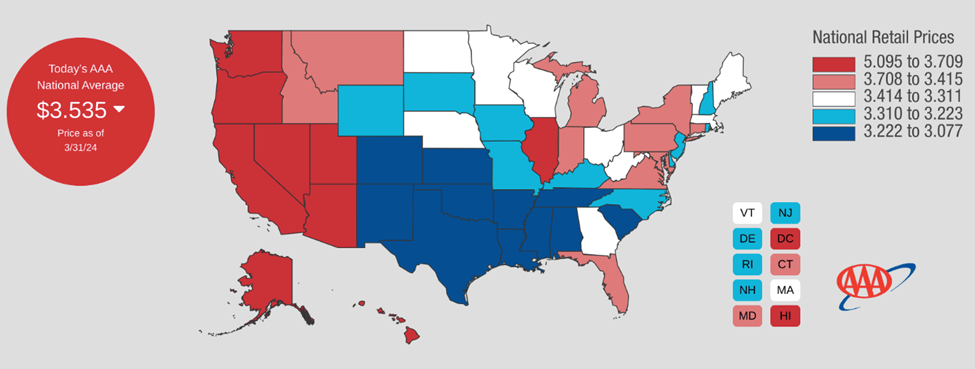
Gasoline prices headed higher again in April. Regular unleaded gasoline is now averaging $3.66 per gallon, up from $3.54 last month. Mississippi has the cheapest gas currently, checking in at $3.10 a gallon. California has the most expensive gasoline at $5.39 per gallon. FYI, a year ago, we were paying $3.61.
Check out the prices at the pump in your area: AAA Gas Prices.
Outlook
Events on the horizon that could move the markets in the near term:
Fed & Inflation: The Fed concluded their scheduled two-day meeting today and kept rates unchanged. They really don’t have a choice: unemployment is at historic lows and wages continue to rise. Both good things but too good, according to the Fed. Although prices have stabilized, especially for groceries, they just haven’t seen enough progress to justify cutting rates anytime soon. They feel what they have done so far is working, but not quite at the pace that they want so it looks like interest rates are going to remain high through at least the summer. Good news for savers, bad news for borrowers. For stock market investors, rate cuts aren’t fully priced into the market anymore so when it does happen, it will be a positive catalyst for stocks, but patience is warranted here.