
Calendar Notes
- Saturday, May 4th, Kentucky Derby
- Monday, May 27th, Memorial Day. The stock market is closed.
Stocks finally took a breather in April after a five-month run of positive returns. It’s always healthy for the markets to take a break and consolidate to form another base before moving higher again. So, this break in the upward trend is not surprising, but still not fun to watch if you are long stocks. For the month, the S&P 500 was lower by about 4.20%. For 2024, it is up about 5.57%.
Q1 earnings continue to pour in and, for the most part, have been exceeding expectations, supporting the strong economic data that we have seen so far this year. Of course, earnings reports are looking into the past and it is what companies say about future growth that really moves their stock prices. The good news here is that CEOs are signaling that strong revenue growth should continue, although they are concerned about interest rates staying elevated.
Historically, May has been a month where many traders, or short-term investors, like to prepare their portfolios for the summer. Like the saying goes, sell in May and go away. We will see if that holds true this month.
The Federal Reserve met today and held rates steady once again. They are certainly testing the patience of both stock and bond investors, but so far, their stance hasn’t broken the economic momentum that we have seen over the past year (yet).
Take a look at the Outlook section below to see what events could move the markets over the short term.
Bond prices continue to flip flop, this time heading lower during the month of April. This drop was mainly due to the continued signs of a strong economy and inflation remaining sticky in certain areas, such as food and fuel. This is certainly causing the Fed to rethink when they want to start cutting back on interest rates.
The 10-year US Treasury note yield rose in April, finishing the month at 4.69%, higher than the 4.21% that it was at the beginning of the month. The 30-year bond yield closed out the month at 4.79%, higher than the 4.35% that it was a month ago.
Although the path of interest rates still appears to be in the downward direction, it is not a given. Therefore, bond buyers should continue to focus on bonds with short-term maturities. I would keep maturities under 18 months and just plan on holding these bonds to maturity. That way, you won’t have to worry about selling at a discount if interest rates head higher.
Savings rates stayed about the same in April as compared to March, even as other rates moved higher. But this is expected because savings rates typically follow, but lag, the direction of bond yields. These current savings rates are still quite high, especially with respect to inflation. So, CDs and MMAs continue to be agreat place to park your cash and your emergency fund. These rates continue to be a legitimate alternative to stocks and bonds and will keep pressure on those markets until we see this trend reverse, which looks like it will be happening later in the year than expected.
Now, take a look at the top rates for CDs and money market accounts (MMA):
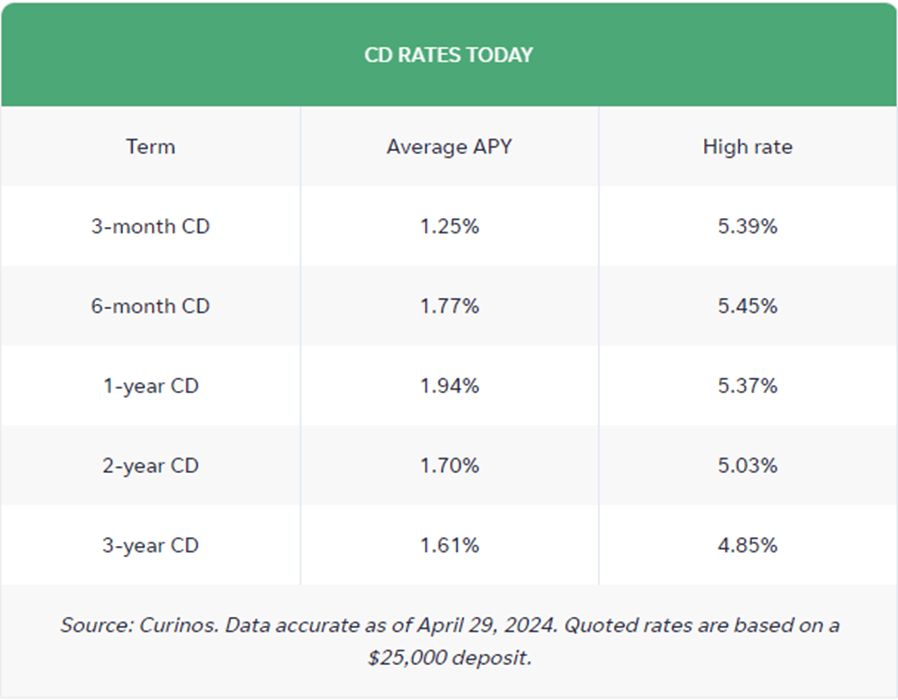
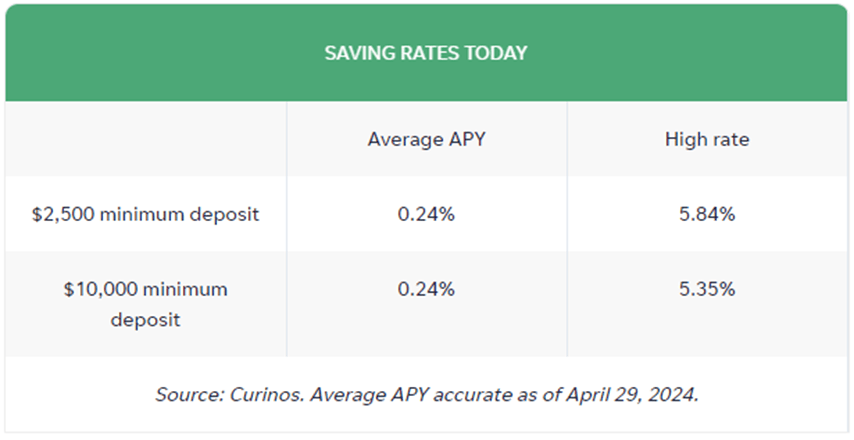
The best 1-year CD interest rate is currently at 5.37%. The best 5-year CD rate right now is around 5.25%. We should see the 5-year CD rate surpass the 1-year rate by the end of the year based on current interest rate trends.
Eventually, savings rates will normalize but not until inflation comes down enough for the Fed to feel comfortable lowering interest rates. That said, I would still put my savings or emergency spending money into short-term CDs, 1 year or less, and reevaluate when they mature. If you would rather have more liquidity, look into an MMA (yielding close to 6% currently). Keep the total under $250,000 per person at any one bank to ensure you are fully covered by the FDIC. CDs and MMAs have become nice alternatives for risk-averse investors and have drawn money away from stocks because of their realtively high rates that carry virtually no risk.
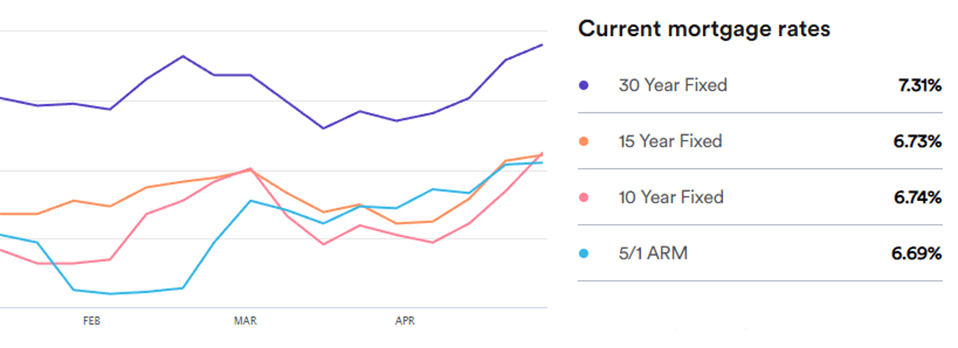
Mortgage rates rose in April as demand picked up most likely due to the spring buying season starting up. Currently, the 30-year rate sits at 7.31%, higher than a month ago, at 7.20%. The housing market continues to be in an unusual situation (high rates, low home inventory, strong demand) and that is making mortgage rates very volatile. Most homeowners either own their home outright or have a mortgage below 3.5%. There is very little incentive to sell a home with rates where they are right now. That will not change until mortgage rates fall. For now, the industry continues to bank on the Federal Reserve to get it squared away.
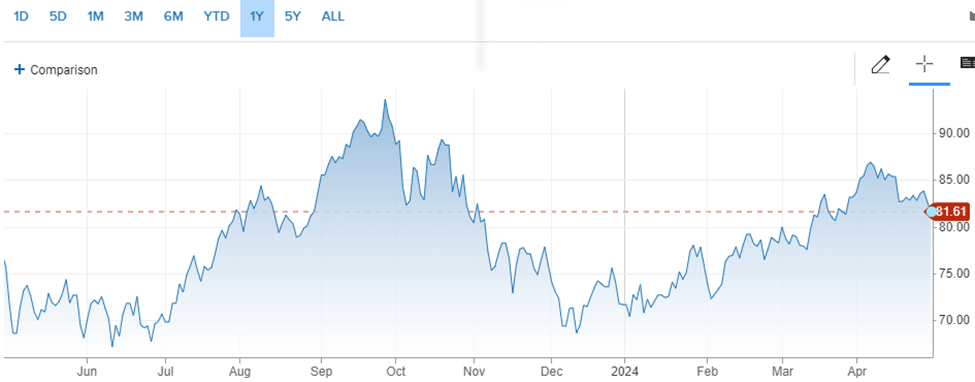
Oil prices broke their upward moving trend and dropped slightly in April, snapping a three-month streak. The drop could be attributed to the strong dollar due to rates in the U.S. staying higher, causing demand for the dollar worldwide, thus making imported oil cheaper.
For the month, the price for a barrel of oil settled at $81.61, down from $83.17 at the beginning of April. For the year, it is up about 14%. Although oil prices fell, they are still high and are a big cause of the stubborn inflation that we are seeing in consumer prices, especially in the food and travel/leisure industries. It could be tough to get prices lower with economies worldwide continuing to chug along at a strong pace. It is a quandary that might be resolved only through demand destruction, or put another way, the cure for high oil prices is high oil prices.
Here’s a look at the one-year chart for U.S. oil:
Gasoline prices headed higher again in April. Regular unleaded gasoline is now averaging $3.66 per gallon, up from $3.54 last month. Mississippi has the cheapest gas currently, checking in at $3.10 a gallon. California has the most expensive gasoline at $5.39 per gallon. FYI, a year ago, we were paying $3.61.
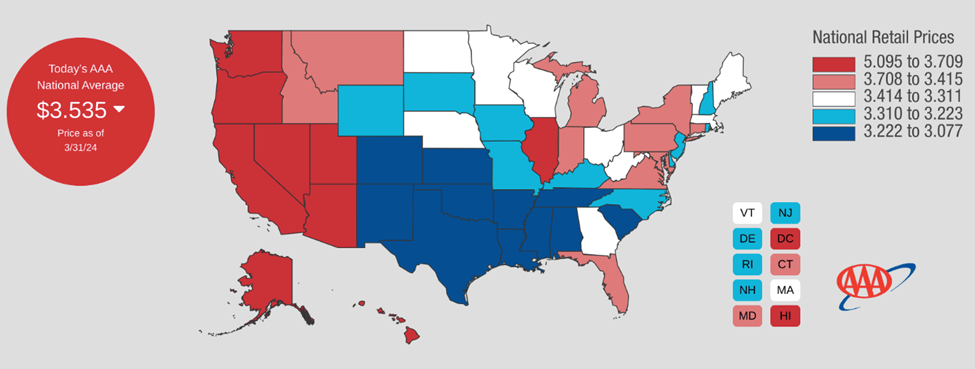
Check out the prices at the pump in your area: AAA Gas Prices.
Outlook
Events on the horizon that could move the markets in the near term:
Fed & Inflation: The Fed concluded their scheduled two-day meeting today and kept rates unchanged. They really don’t have a choice: unemployment is at historic lows and wages continue to rise. Both good things but too good, according to the Fed. Although prices have stabilized, especially for groceries, they just haven’t seen enough progress to justify cutting rates anytime soon. They feel what they have done so far is working, but not quite at the pace that they want so it looks like interest rates are going to remain high through at least the summer. Good news for savers, bad news for borrowers. For stock market investors, rate cuts aren’t fully priced into the market anymore so when it does happen, it will be a positive catalyst for stocks, but patience is warranted here.
Joe Baker, CFP®
Baker Asset Management, LLC
joebaker@bakerassetmanagement.com

