
A new rule regarding FDIC insurance for trust accounts became effective on April 1, 2024, that could impact anyone with a trust account held at an FDIC-member bank. The new rule simplifies insurance coverage for trust accounts by:
- Reducing the number of insurance rules for trust accounts
- Eliminating complexities from the revocable and irrevocable trust rules
- Utilizing the same familiar, straightforward insurance calculation for both revocable and irrevocable trusts
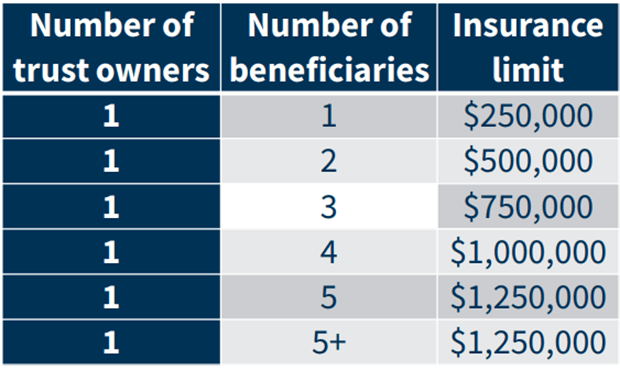
The new rule provides insurance of a trust account(s) of $250,000 per beneficiary, for up to five beneficiaries, for a total of $1,250,000.
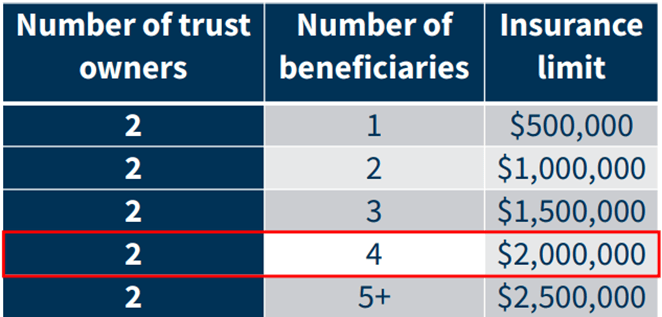
This is per each trust owner for each bank. However, many trusts have multiple owners. So, for example, if you own a trust with your spouse (two owners) and the trust has four beneficiaries, FDIC insures up to $2,000,000 (2 owners x 4 beneficiaries x $250,000).
It’s important to note that $1,250,000 remains the maximum insurance, per bank, for a single owner, regardless of how many trusts and/or beneficiaries that they have at that particular bank. That means if a person has, say, a revocable living trust and an irrevocable charitable trust, those trusts are combined to determine how much the owner is insured for those combined assets.
Although this new rule was enacted to simplify the FDIC insurance rules regarding trust accounts, it still has its complexities. I would definitely recommend working with your financial advisers to maximize coverage for your financial assets.
Please comment or send an email if you have any questions. Thanks!
Joe Baker, CFP®
Baker Asset Management, LLC
joebaker@bakerassemanagement.com

