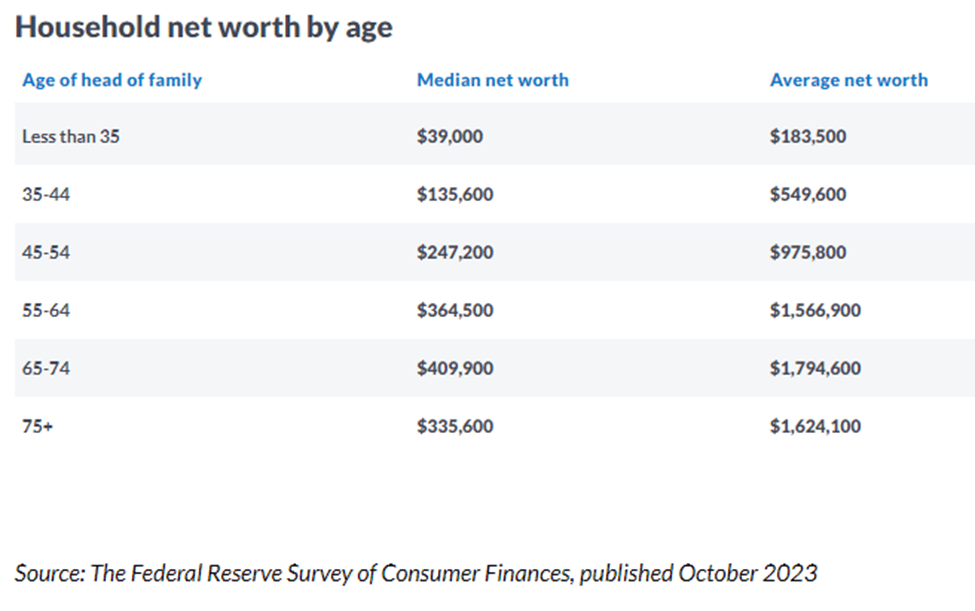I was looking at some data last week to see if the U.S. still had a good chance of avoiding a recession and came upon some interesting charts that I wanted to share with you.
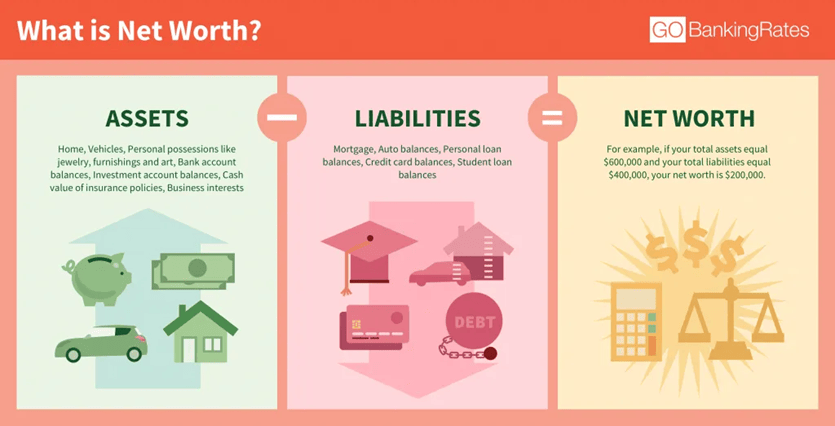
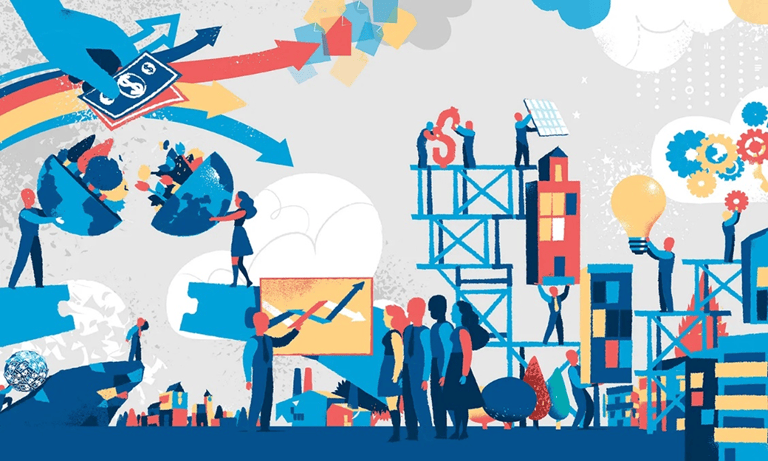
The first chart takes a look at the average and median net worth of U.S. citizens categorized by age as of 2023. Remember, net worth is just your assets minus your liabilities. The illustration above gives a great example of how net worth is calculated.
You can see there is quite a difference between average and median values. That’s because there are a bunch of households that are extremely wealthy and that will skew the average higher. The more realistic values are the ones in the Median Net Worth column. These amounts are calculated simply by locating the middle value of all the net worth values in that age group. That said, both show that the net worth of U.S. households is the highest that it’s ever been.
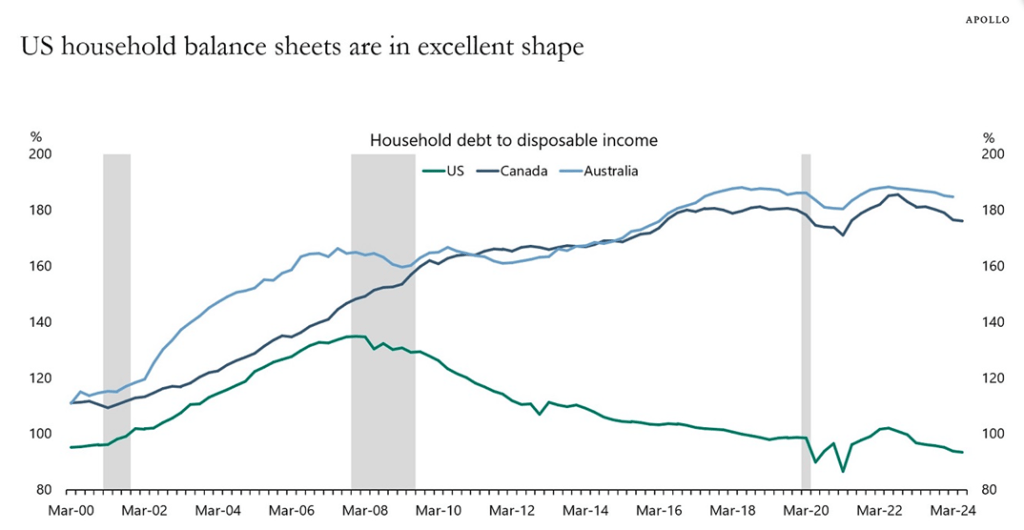
This next chart compares our household debt as a percentage of disposable income to our buddies in Canada and Australia. The lower the percentage, the better:
As you can see, we are below 100% which means that we have enough disposable income to pay off our debts. Also, we are in much better shape than our Canadian and Australian friends.
This is good news any way you slice it. The combination of rising asset values (homes, stocks, etc.), decent job growth, solid wage growth, and the Fed cutting interest rates, almost ensures that there is no recession on the horizon.
Please comment or send an email if you have any questions.
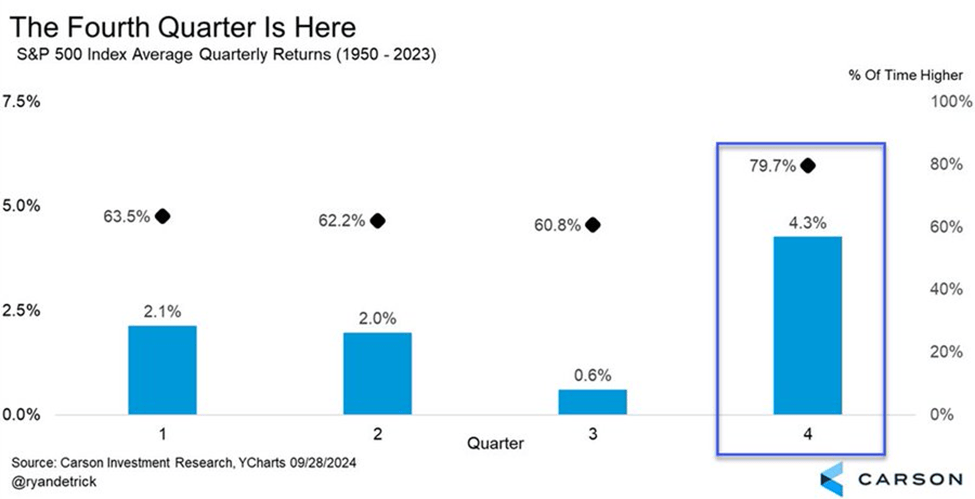
History tells us that the fourth quarter of the year is typically a very good time to be invested in stocks. Take a look at this chart:
As you can see, the S&P 500 index has an average return of 4.3% in the fourth quarter over the past seventy-three years. This is more than twice as good a return as any other quarter of the year.
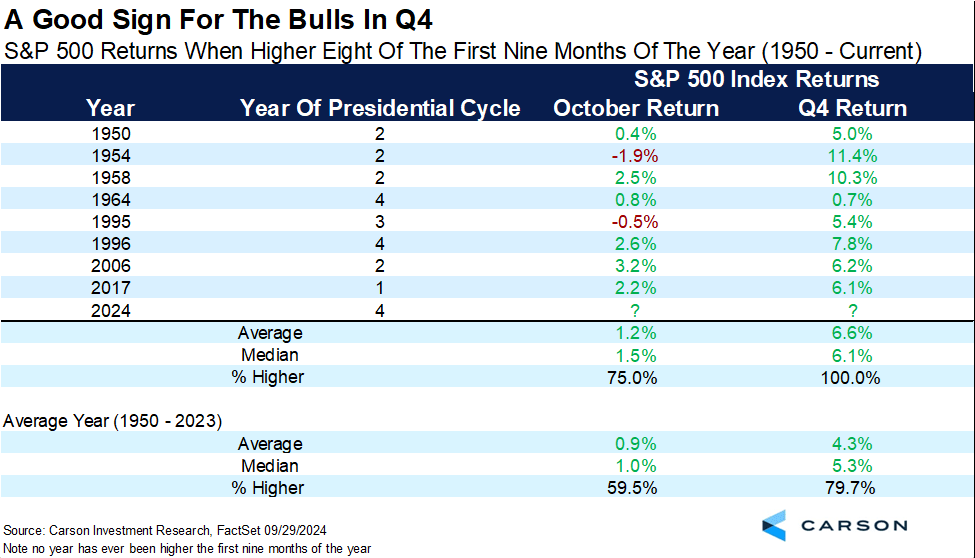
Historical data gets even better for stock market bulls when it comes to this year. When the S&P 500 index is higher the first eight of the nine months of a year, like it has been in 2024, then the fourth quarter is positive every single time (8 for 8), with an average gain of 6.6%. FYI, the index has never been up each of the first nine months of a year. This year, April has been the only down month.
I have to hedge this blog by stating that the upcoming election could have a greater influence on the markets than any other election in recent history. Even so, if history repeats itself, or at least rhymes, we should expect a pretty good quarter for the stock market to finish out 2024.
Please comment or send an email if you have any questions.
I recently took a look at a whole bunch of economic data charts compiled by economists and strategists from the financial world. Much of this information shows that the U.S. economy can still achieve a soft landing coming out of the interest rate hiking cycle of the past few years.
Regarding the stock market, there are mixed reviews with some showing further room to run in this current bull market while others expect a pullback, especially with uncertainty picking up as we approach the November elections.
Here are a few of those charts that I wanted you to see:
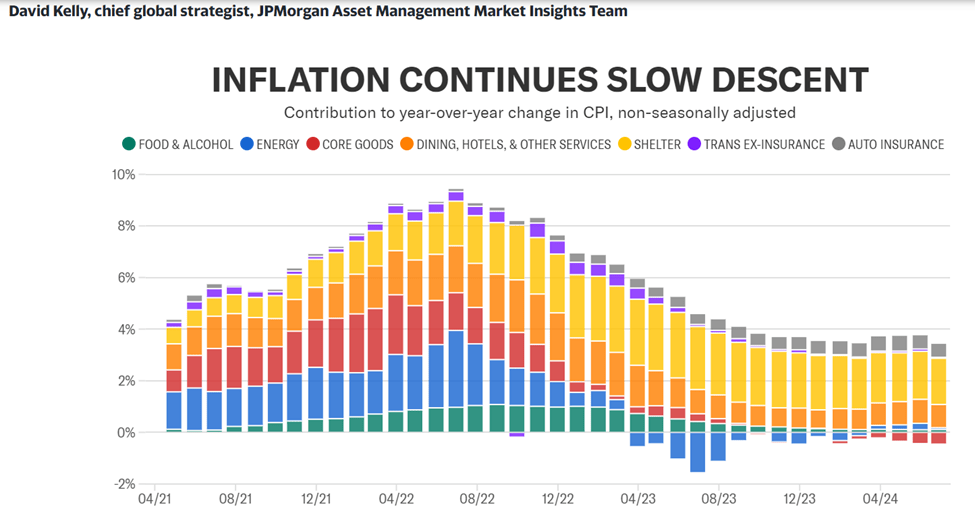
Shelter and auto insurance have been the two stubborn pieces of inflation that haven’t subsided yet. The good news is that rents and mortgage rates are rising much slower or even dropping in some areas, which should help get inflation down to the Federal Reserve’s target of 2% sometime in 2025.
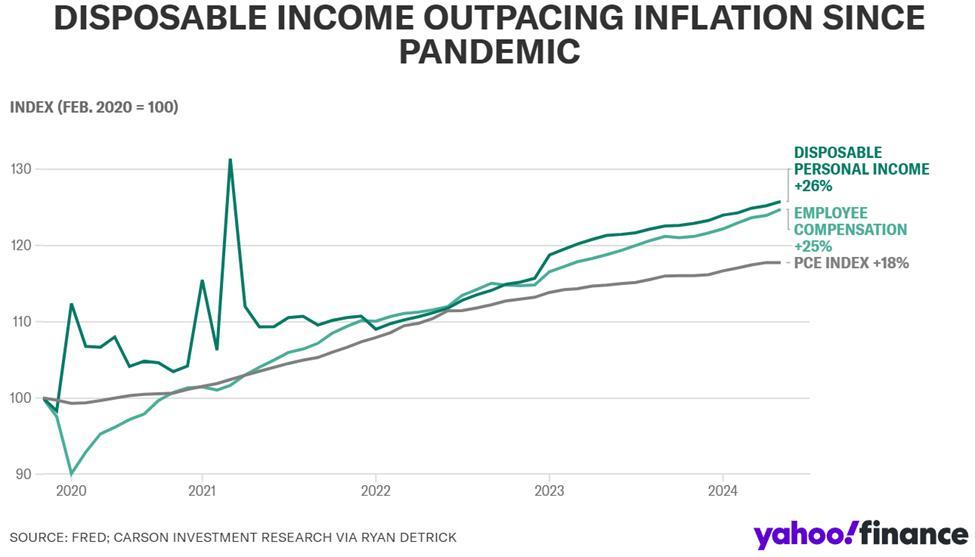
Because inflation has taken up all the oxygen in the room over the past few years, disposable income outpacing inflation is not a well-known statistic, but here it is. Both employee compensation and disposable personal income have increased more than inflation since the pandemic. Also, inflation is expected to continue to drop through the rest of this year, so consumers should see their disposable income increase, assuming their salaries remain the same.
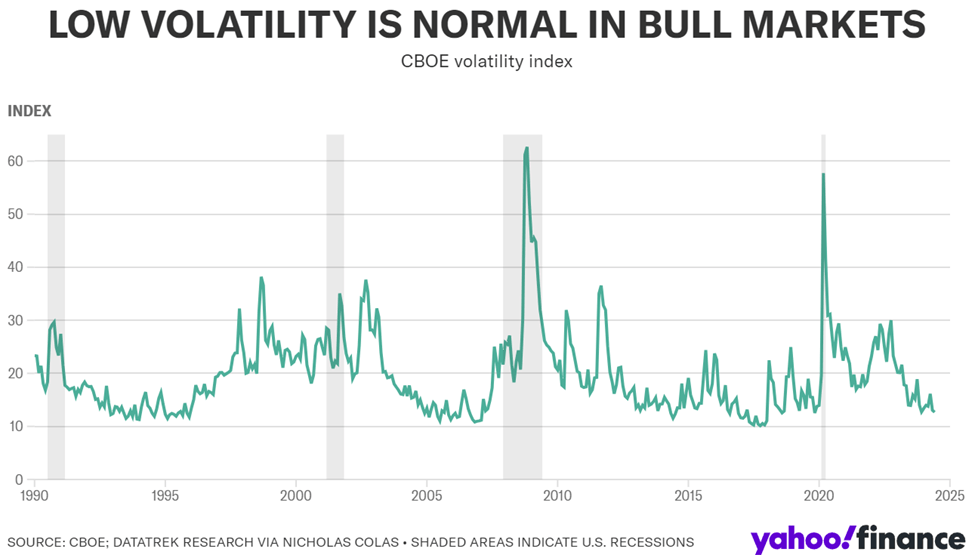
Chicago Board Options Exchange (CBOE) Volatility Index, more commonly known as the VIX, is an options-based measure of expected S&P 500 volatility over the next 30 days. When this indicator is consistently below 20, stocks tend to perform well. This was the case in the mid-1990s, mid-2000s, and much of the 2010s. When the VIX spikes, it is an indicator of a recession, of which the four most recent are shown as the shaded regions in the chart above. So, we could be in a period of low VIX, which is good for stocks, or about to enter a period where the VIX spikes. Interest rate and election forces will be what moves this index through the rest of this year.
To summarize, the economy and markets have done well so far in 2024 but it feels like we are at an inflection point now. The two big influencers are interest rates and the elections. These will dictate how we finish up in 2024. It should be an interesting ride into the end of the year.
Please comment or send an email if you have any questions.
I thought it would be interesting to take a look at the late 1990’s Dot Com era and see how it compares to the current AI era. There are some similarities that I see, particularly with investors’ mindsets, that make me think history will repeat itself. But there are also some key differences that could keep the AI era from suffering the same fate as the Dot com era. Here’s what I am seeing:
What’s the same
Transformational Change – In the 90’s, the internet was changing how businesses interacted with customers. We went from going to brick and mortar stores to sitting at a computer to transact business. Today, AI is involved not only on the transactional side of business, but also the marketing, manufacturing, research, and almost every aspect of business today.
Fear Of Missing Out (FOMO) – You couldn’t go to a party, restaurant or pretty much any social gathering without hearing someone talk about how well their Dot Com investments were doing. This caused a great deal of FOMO among both retail and institutional investors. If there was a “.com” at the end of a company’s name, you wanted to own its stock. Now, investors are lining up to buy any company that is involved in AI infrastructure and willing to pay a premium for them.
What’s different
Earnings – The Dot Com era ushered in an incredible number of companies that went public based on hype and the promise of amazing revenue and profits. Many had no revenue but the push to get their stock publicly traded was so great that they rushed to the markets. The insanity was that investors couldn’t get enough of them. Of course, once reality set in, these companies went bankrupt, and investors lost everything. Now, most companies involved in AI are already well established (Microsoft, Amazon, Google, Nvidia, Meta, etc.) and are very profitable already.
Behind the Scenes – AI is helping make companies more efficient, productive, and profitable by improving operations and procedures behind the scenes. It is involved in almost every aspect of a company’s business whereas in the Dot Com era, the internet was more concentrated in just the sales and marketing sectors.
Far Reaching – Back in the 90’s the internet focused mainly on the interphase between businesses and consumers. Today, AI is not only involved there, it is changing nearly every aspect of every industry. In health care for instance, AI can read x-rays, CAT scans, and biopsy slides with incredible accuracy, detecting and diagnosing diseases faster. In the forest fire arena, AI is now being used to detect fires much quicker than humanly possible. California has 1,000 cameras monitoring their forests using AI. The money, manpower, and property saved by employing AI is immense. Now, extrapolate that across every industry and you can see why AI is a game changer.
That being said, it does seem that the markets might be getting ahead of themselves in this AI era. But it is nowhere near the frenzied euphoria that caused the Dot Com era bubble to burst…..for now.
Please comment or send an email if you have any questions.
Since November of last year, the S&P 500 index has risen steadily, with just a handful of weeks with negative returns. So, you may be asking yourself if stocks have gone up too far, too fast and are ripe for a pullback. If you are good at timing the market, this may seem like a good time to take some chips off the table. I recently talked about timing the market and you can check that out here: Sell In May And Go Away?
But before you do anything, you should ask yourself this question: Are you a trader or an investor?
Traders and investors both deal with buying and selling financial assets, but they have different goals and timeframes. Here’s a breakdown of the key differences:
Timeframe:
Trader: Focuses on short-term gains, buying and selling assets within a short period, like seconds, days, or weeks. This is often called short-term trading or day trading.
Investor: Has a long-term perspective, buying and holding assets for years or even decades. They aim to grow their wealth through the overall appreciation of the assets and potentially through dividends (regular payments from companies to shareholders).
Goal:
Trader: Aims to capitalize on short-term market movements and price fluctuations. They may be more concerned with technical analysis, looking for patterns in charts and trading data.
Investor: Focuses on the underlying value of the asset and the company’s potential for long-term growth. They rely more on fundamental analysis, researching a company’s financials and overall economic conditions.
Effort:
Trader: Trading can be a very active process, requiring constant monitoring of markets and frequent buying and selling decisions.
Investor: Investing can be more passive, requiring less day-to-day attention. Investors may periodically rebalance their portfolio, but generally don’t need to be glued to the markets.
Risk:
Trader: Short-term trading can be riskier, as markets can be volatile and unpredictable.
Investor: Long-term investing is generally considered less risky, as history shows the stock market tends to trend upwards over time. However, there are still risks involved, such as economic downturns.
There are many people, me included, who operate as both a trader and an investor. For me, I have trader accounts and investor accounts. My retirement accounts are considered my investor accounts. I also have a small trader account that I manage as well.
For traders, this probably is a good time to take some profits and get some cash ready to make buys after the eventual dip that’s coming since stocks seem over bought currently. Traders can also buy put options (insurance of sorts) to protect their gains without having to sell their existing positions.
For investors, the current state of the markets shouldn’t influence your long-term strategy. If you are holding well-managed companies with strong financials in growing industries and high barriers to entry (wide moat), you stay the course. If their stock prices drop on the eventual pullback, you buy more.
Now, you can categorize your accounts based on how you manage them, as a trader or as an investor.
Finally, just as a reminder, if you need money for something in the immediate future, it should be in an emergency reserve account, like a money market, savings, or checking account.
Please comment or send an email if you have any questions.
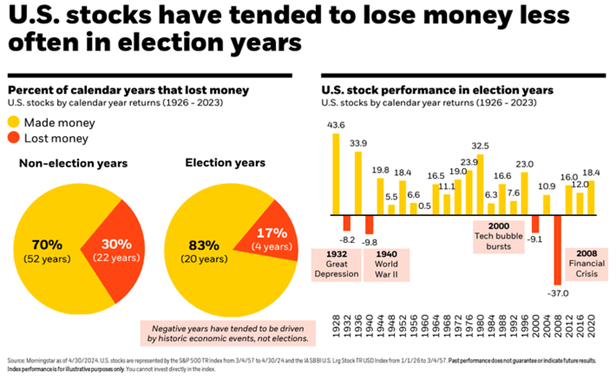
I saw some interesting charts in the past week that illustrate stock performance in a presidential election year.
First, in the chart above, you can see that stocks have performed well in past presidential election years. The four years that stocks had negative returns included some very significant economic and geopolitical events that contributed to their poor performance.
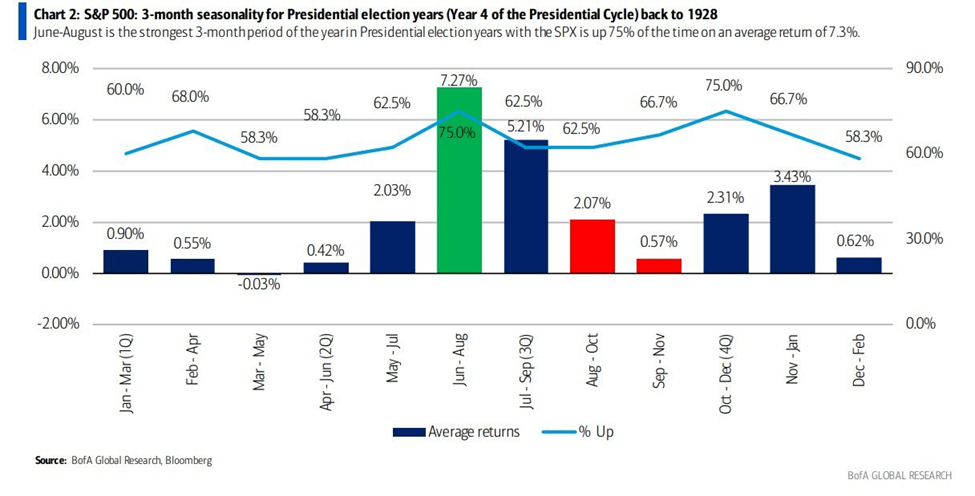
This next chart shows how stocks performed during every rolling three month stretch in an election year going all the way back to 1928. As you can see, the June, July, and August stretch is the best performing with a positive return 75% of the time and an average return of almost 7.3%.
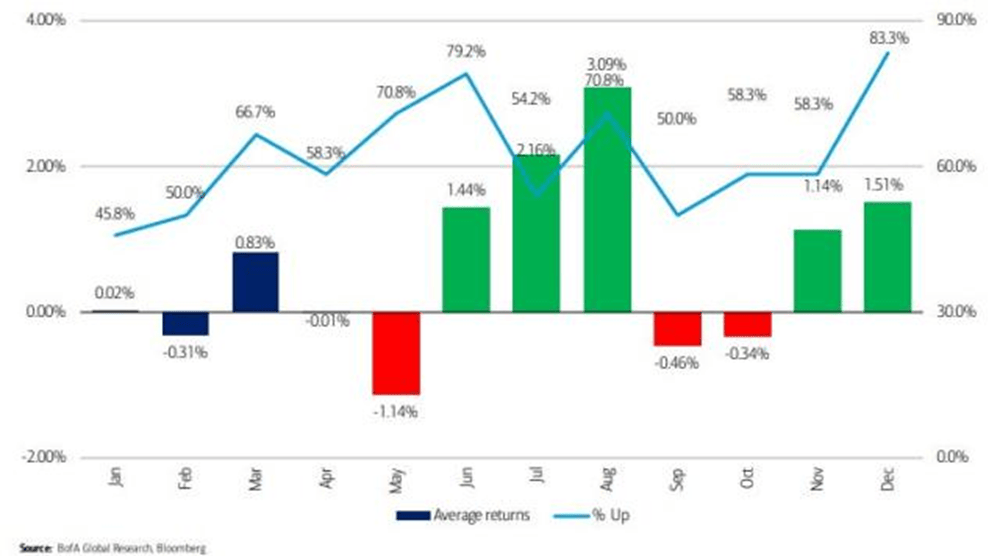
The last chart simply shows the performance of stocks during each month of a presidential election year going back to 1928.
So, it seems that summertime is the best time to be invested in the stock market during a presidential election year. However, we are currently at or near all-time highs in most stock indices and appear to be ripe for a pullback in stock prices. It will be interesting to see if this historical trend can hold up with such a positive return in stocks preceding it over the last eighteen months.
Please comment or send an email if you have any questions.
Sell in May and go away is an old Wall Street saying that is the basis for a market-timing investment strategy which calls for you to sell your stock holdings right before summer and buy them back in late fall, or right before Memorial Day and right after Halloween.
Historically, the S&P 500 has performed better during the winter months than in the summer months. So, there is evidence that this strategy could work, but we are really Monday-morning quarterbacking here. In reality, you have to be very good at timing the market not once, but twice every year! You have to pick when to sell and then you have to pick when to buy back in. Plus, you have to consider your holdings’ short-term versus long-term gains and losses as well as the associated tax ramifications.
I don’t know of anyone or any firm that has been able to do this successfully for an extended period of time.
So, whenever I hear the “Sell in May and go away” adage, I like to think of another old Wall Street saying: Time in the market, not timing the market. This means relying on a strategy where you don’t try to guess when the market is at its lowest or highest point. Instead, you invest knowing that your timing is probably going to be off, but that eventually, investing in great companies with strong fundamentals matters more than the timing.
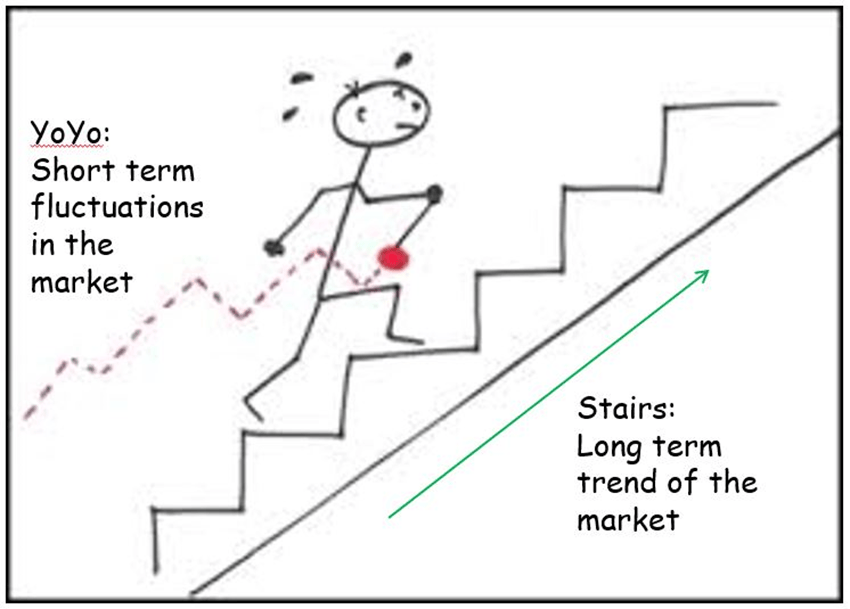
Now is when I roll out my favorite illustration to show why time in the market is better than timing the market for investors.
Picture the movement of the yo-yo as the short-term fluctuations of the stock market and the guy walking up the stairs as the long-term trend of the market. The market has its ups and downs, but over time, has consistently moved higher. This is a simple, but effective, way to illustrate why time in the market is better than timing the market.
Please comment or send an email if you have any questions. Have a great Memorial Day weekend!
In the financial world, everything today is about the Federal Reserve and interest rates. Currently, rates are at a level not seen since about 2007. As you know, rates affect how much it costs to borrow money and also how much interest that you receive when you lend money, like when you deposit it in a savings/money market account or buy a bond. So, it’s not all bad when interest rates are high. In fact, rates are closer to historical norms now than they have been in the last 16 years.
That said, why haven’t these higher rates had their desired effect on reducing inflation? Here are a few reasons:
About half of all mortgages have an interest rate locked in below 4% – When rates plummeted during Covid, anyone that had a high mortgage rate refinanced to a fixed rate mortgage below 4%, many in the 2% to 3% range. So, their biggest monthly expense was reduced significantly and will be for decades to come if they don’t sell. Thus, higher rates will have less of an influence on these consumers.
Homeowners are making money on their mortgage loans – You heard that right. People with a low-rate fixed mortgage are taking the money that they borrowed and are buying CDs and government bonds that pay five percent interest or more. For example, if you have a mortgage at 3.5%, instead of paying down your mortgage, you can take any extra cash and buy a CD at 5% and make 1.5% on your money.
People are still spending even with sustained high prices – Usually, when prices have risen this much (groceries, utilities, insurance, etc.), consumers tighten their belts and pull back on discretionary spending (vacations, big ticket items). This has not happened, at least not yet. With historically low unemployment and decent wage increases, people are still traveling and spending, especially those with no mortgage or a low mortgage rate.
Higher interest rates will eventually work to lower inflation, but it may take longer than anyone expected. Plus, it is a good thing for risk-averse investors and savers.
Please comment or send an email if you have any questions. Thanks!
A new rule regarding FDIC insurance for trust accounts became effective on April 1, 2024, that could impact anyone with a trust account held at an FDIC-member bank. The new rule simplifies insurance coverage for trust accounts by:
Reducing the number of insurance rules for trust accounts
Eliminating complexities from the revocable and irrevocable trust rules
Utilizing the same familiar, straightforward insurance calculation for both revocable and irrevocable trusts
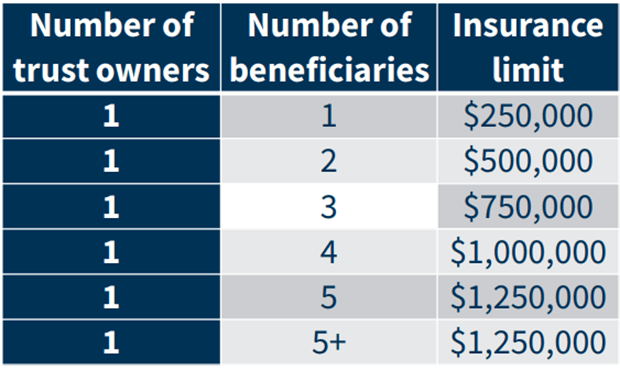
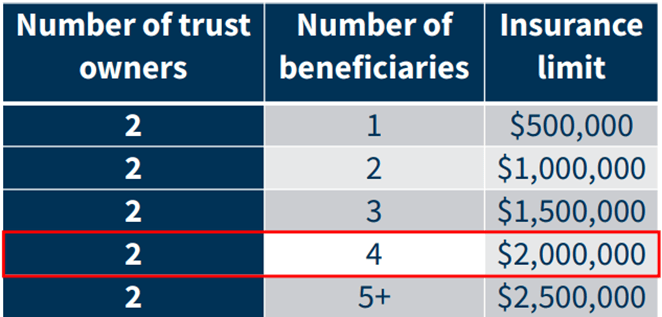
The new rule provides insurance of a trust account(s) of $250,000 per beneficiary, for up to five beneficiaries, for a total of $1,250,000.
This is per each trust owner for each bank. However, many trusts have multiple owners. So, for example, if you own a trust with your spouse (two owners) and the trust has four beneficiaries, FDIC insures up to $2,000,000 (2 owners x 4 beneficiaries x $250,000).
It’s important to note that $1,250,000 remains the maximum insurance, per bank, for a single owner, regardless of how many trusts and/or beneficiaries that they have at that particular bank. That means if a person has, say, a revocable living trust and an irrevocable charitable trust, those trusts are combined to determine how much the owner is insured for those combined assets.
Although this new rule was enacted to simplify the FDIC insurance rules regarding trust accounts, it still has its complexities. I would definitely recommend working with your financial advisers to maximize coverage for your financial assets.
Please comment or send an email if you have any questions. Thanks!
Monday, May 27th, Memorial Day. The stock market is closed.
Stocks finally took a breather in April after a five-month run of positive returns. It’s always healthy for the markets to take a break and consolidate to form another base before moving higher again. So, this break in the upward trend is not surprising, but still not fun to watch if you are long stocks. For the month, the S&P 500 was lower by about 4.20%. For 2024, it is up about 5.57%.
Q1 earnings continue to pour in and, for the most part, have been exceeding expectations, supporting the strong economic data that we have seen so far this year. Of course, earnings reports are looking into the past and it is what companies say about future growth that really moves their stock prices. The good news here is that CEOs are signaling that strong revenue growth should continue, although they are concerned about interest rates staying elevated.
Historically, May has been a month where many traders, or short-term investors, like to prepare their portfolios for the summer. Like the saying goes, sell in May and go away. We will see if that holds true this month.
The Federal Reserve met today and held rates steady once again. They are certainly testing the patience of both stock and bond investors, but so far, their stance hasn’t broken the economic momentum that we have seen over the past year (yet).
Take a look at the Outlook section below to see what events could move the markets over the short term.
Bond prices continue to flip flop, this time heading lower during the month of April. This drop was mainly due to the continued signs of a strong economy and inflation remaining sticky in certain areas, such as food and fuel. This is certainly causing the Fed to rethink when they want to start cutting back on interest rates.
The 10-year US Treasury note yield rose in April, finishing the month at 4.69%, higher than the 4.21% that it was at the beginning of the month. The 30-year bond yield closed out the month at 4.79%, higher than the 4.35% that it was a month ago.
Although the path of interest rates still appears to be in the downward direction, it is not a given. Therefore, bond buyers should continue to focus on bonds with short-term maturities. I would keep maturities under 18 months and just plan on holding these bonds to maturity. That way, you won’t have to worry about selling at a discount if interest rates head higher.
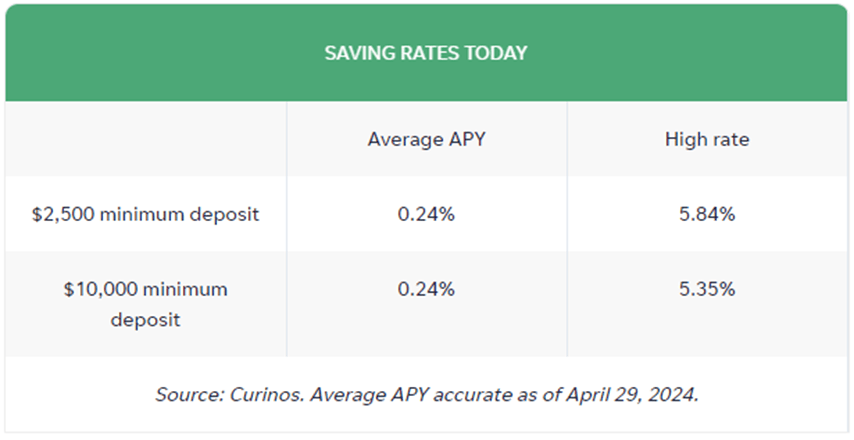
Savings rates stayed about the same in April as compared to March, even as other rates moved higher. But this is expected because savings rates typically follow, but lag, the direction of bond yields. These current savings rates are still quite high, especially with respect to inflation. So, CDs and MMAs continue to be agreat place to park your cash and your emergency fund. These rates continue to be a legitimate alternative to stocks and bonds and will keep pressure on those markets until we see this trend reverse, which looks like it will be happening later in the year than expected.
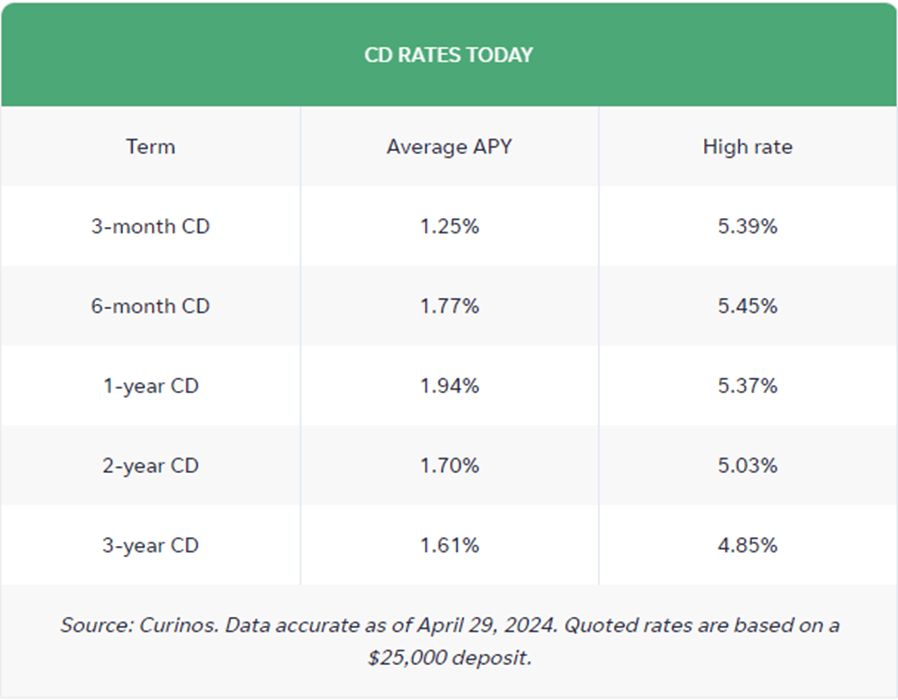
Now, take a look at the top rates for CDs and money market accounts (MMA):
The best 1-year CD interest rate is currently at 5.37%. The best 5-year CD rate right now is around 5.25%. We should see the 5-year CD rate surpass the 1-year rate by the end of the year based on current interest rate trends.
Eventually, savings rates will normalize but not until inflation comes down enough for the Fed to feel comfortable lowering interest rates. That said, I would still put my savings or emergency spending money into short-term CDs, 1 year or less, and reevaluate when they mature. If you would rather have more liquidity, look into an MMA (yielding close to 6% currently). Keep the total under $250,000 per person at any one bank to ensure you are fully covered by the FDIC. CDs and MMAs have become nice alternatives for risk-averse investors and have drawn money away from stocks because of their realtively high rates that carry virtually no risk.
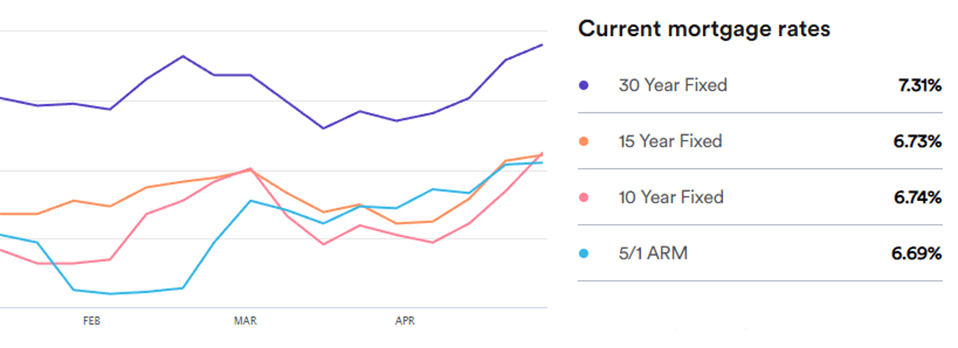
Mortgage rates rose in April as demand picked up most likely due to the spring buying season starting up. Currently, the 30-year rate sits at 7.31%, higher than a month ago, at 7.20%. The housing market continues to be in an unusual situation (high rates, low home inventory, strong demand) and that is making mortgage rates very volatile. Most homeowners either own their home outright or have a mortgage below 3.5%. There is very little incentive to sell a home with rates where they are right now. That will not change until mortgage rates fall. For now, the industry continues to bank on the Federal Reserve to get it squared away.
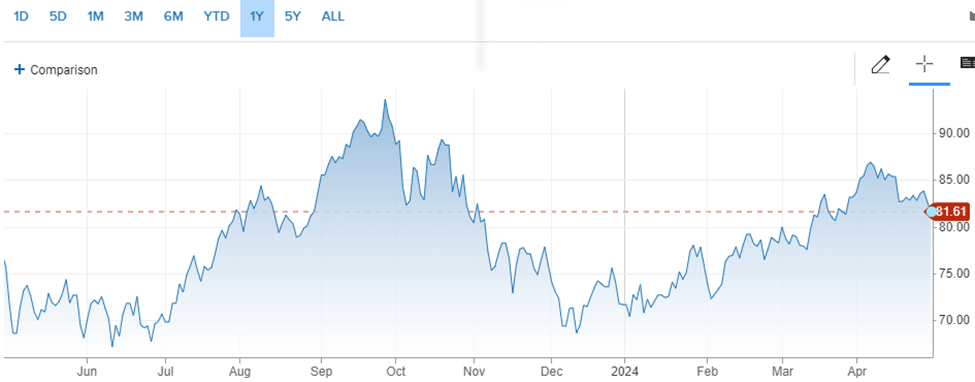
Oilprices broke their upward moving trend and dropped slightly in April, snapping a three-month streak. The drop could be attributed to the strong dollar due to rates in the U.S. staying higher, causing demand for the dollar worldwide, thus making imported oil cheaper.
For the month, the price for a barrel of oil settled at $81.61, down from $83.17 at the beginning of April. For the year, it is up about 14%. Although oil prices fell, they are still high and are a big cause of the stubborn inflation that we are seeing in consumer prices, especially in the food and travel/leisure industries. It could be tough to get prices lower with economies worldwide continuing to chug along at a strong pace. It is a quandary that might be resolved only through demand destruction, or put another way, the cure for high oil prices is high oil prices.
Here’s a look at the one-year chart for U.S. oil:
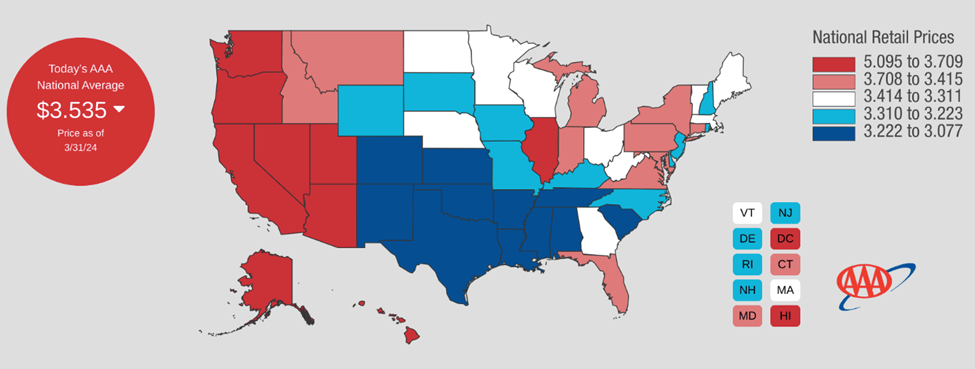
Gasoline prices headed higher again in April. Regular unleaded gasoline is now averaging $3.66 per gallon, up from $3.54 last month. Mississippi has the cheapest gas currently, checking in at $3.10 a gallon. California has the most expensive gasoline at $5.39 per gallon. FYI, a year ago, we were paying $3.61.
Check out the prices at the pump in your area: AAA Gas Prices.
Outlook
Events on the horizon that could move the markets in the near term:
Fed & Inflation: The Fed concluded their scheduled two-day meeting today and kept rates unchanged. They really don’t have a choice: unemployment is at historic lows and wages continue to rise. Both good things but too good, according to the Fed. Although prices have stabilized, especially for groceries, they just haven’t seen enough progress to justify cutting rates anytime soon. They feel what they have done so far is working, but not quite at the pace that they want so it looks like interest rates are going to remain high through at least the summer. Good news for savers, bad news for borrowers. For stock market investors, rate cuts aren’t fully priced into the market anymore so when it does happen, it will be a positive catalyst for stocks, but patience is warranted here.