Steer Clear of Small-Cap Stock Funds

For as long as I can remember, one of the standard ingredients in a diversified stock portfolio has always included small-cap stock mutual funds or ETFs. As a refresher, small-cap stocks are shares in publicly traded companies with a market capitalization between $250 million and $2 billion and are considered to have higher growth potential but also higher risk compared to larger companies, such as those in the S&P 500 index.

Some of the risks that differentiate small-cap stocks from their large-cap siblings are:

  • Lower Liquidity: Small-cap stocks often have lower trading volumes. This means it can be difficult to buy or sell a large number of shares quickly without significantly impacting the stock’s price. In times of market stress, this lack of liquidity can make it challenging to exit a position, potentially exacerbating losses.
  • Greater Risk of Failure: Many small-cap companies are still in their early growth stages, with unproven business models and limited financial resources. This makes them more susceptible to business failures, competition, and economic shocks. Investors in these companies face a higher risk of losing their entire investment compared to investing in established, larger firms.
  • Sensitivity to Economic Conditions: Small-cap companies tend to be more sensitive to macroeconomic factors like interest rates, inflation, and recessions. They often have higher debt burdens and shorter debt cycles, making them more vulnerable to rising interest rates, which increase borrowing costs. During economic downturns, small businesses can be hit harder and take longer to recover than larger, more diversified corporations.

Because of these increased risks, most investors like to use small-cap mutual funds or ETFs to meet their diversification goals because it allows them to invest in a basket of small-cap stocks which normally helps reduce some of the risk. Recently, however, this has not been the best strategy and another reason why too much diversification can lead to diworsification when setting up your stock portfolio.

The biggest problem with small-cap funds is that when a small-cap company does well, it either gets bought by a larger company or becomes too big to stay in the small-cap world. Either way, it gets taken out of the small-cap fund, leaving the lower performing companies in it and it looks like investors are starting to realize this:
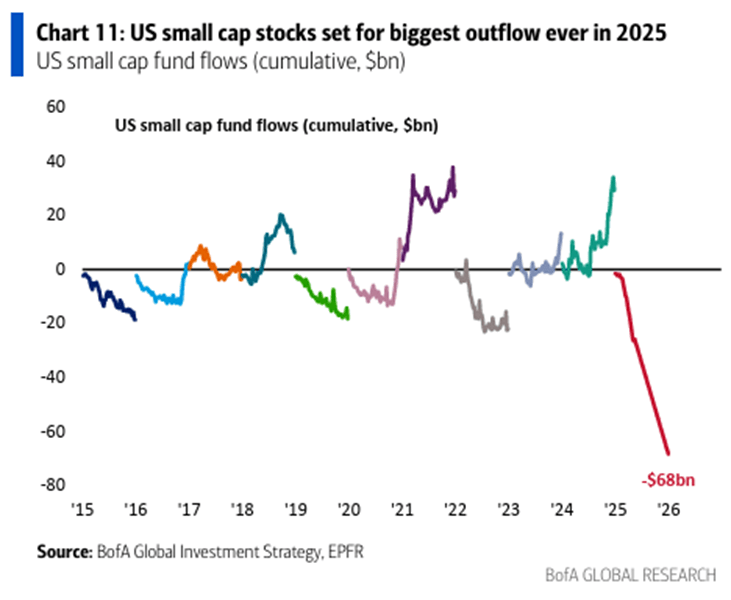
This illustration shows flow of money into and out of small-cap funds over the last ten years. As you can see, money is moving out big-time this year due to underperformance for the reasons stated above.

Here’s a few more charts that should scare you away from small-caps:
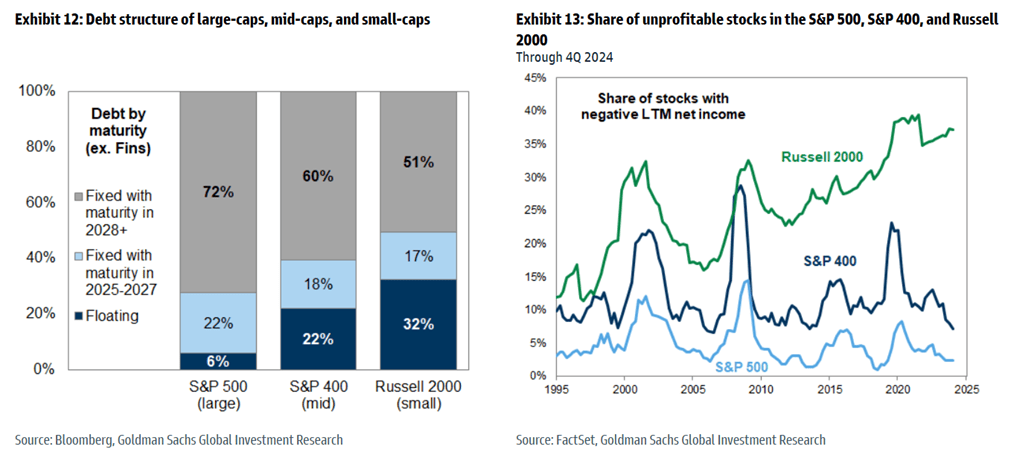
The chart on the left shows that small companies hold a larger portion of their debt in floating rate loans, which can be a huge risk in a rising interest-rate environment that we are starting to see as the tariffs start to kick in. The graph on the right shows that the number of unprofitable small-cap stocks is increasing while larger companies are becoming more profitable.

While it can pay off investing in small-cap stocks, it just seems like there is too much risk for the reward, especially in the current economic environment.

Please comment or send an email if you have any questions.

Joe Baker, CFP®

Baker Asset Management, LLC

joebaker@bakerassetmanagement.com
Calculating Estimated Taxes for Retirees

Retirement marks a significant financial transition, and with it comes a shift in how federal income taxes are managed. Unlike the years of employment where taxes were typically withheld from each paycheck, retirees often find that their income sources, such as distributions from retirement accounts, investment earnings, and even Social Security benefits, may not have taxes automatically deducted. This necessitates understanding and potentially paying estimated federal taxes, a system designed to ensure that income tax is paid throughout the year rather than in a single lump sum at the time of filing. Navigating these obligations is crucial for retirees to avoid potential penalties and interest imposed by the Internal Revenue Service (IRS) for underpayment.

Many individuals transitioning into retirement may find the concept of estimated taxes unfamiliar, especially if their primary income source for most of their working lives was through wages with automatic withholding. This change in tax responsibility can be a significant adjustment, requiring a proactive approach to tax planning and payment. Furthermore, the diverse nature of retirement income, which can include pensions, annuities, investment portfolios, and Social Security benefits, often makes tax obligations more intricate than during active employment. Each of these income streams has its own set of tax rules and varying degrees of potential withholding, demanding careful management of one’s overall tax situation. By taking a proactive stance in understanding and managing estimated tax obligations, retirees can achieve greater financial security and enjoy their retirement years with the assurance of having met their tax responsibilities, thereby avoiding unexpected tax bills.

How do retirees know if they have to pay estimated taxes?

The fundamental question for retirees is whether they are required to pay estimated federal income taxes. Generally, the rule is that a retiree must pay estimated tax if they anticipate owing at least $1,000 in federal income tax for the year, after accounting for any withholding and refundable credits. Here is a list of the most common forms of income that are not subject to automatic federal income tax withholding:

  • Taxable distributions from traditional IRAs, 401(k) plans, and other pre-tax retirement accounts may not have sufficient withholding to cover total tax liability.
  • Interest income, excluding tax-free municipal bonds, generally lacks automatic withholding.
  • Dividend income, whether ordinary or qualified, typically does not have automatic withholding either.
  • Capital gains from sales of investments like stocks, bonds, or real estate are usually not subject to withholding at the point of sale.
  • Rental income often requires estimated tax payments as it is treated as self-employment income for tax purposes.
  • Self-employed retirees, including freelancers and consultants, should also make estimated tax payments for both income tax and self-employment tax.
  • Retirees can choose to have federal taxes withheld from Social Security benefits; otherwise, the taxable portion may need estimated tax payments.

How do retirees calculate payments for estimated taxes?

Calculating estimated federal income tax requires retirees to project their expected income, deductions, and credits for the entire current tax year. The primary tool for this process is IRS Form 1040-ES, “Estimated Tax for Individuals”. This form includes worksheets designed to guide taxpayers through the necessary calculations.

Here is a quick summary of the steps to calculate estimated taxes for retirees:

  • The first step in calculating estimated tax is to estimate total income from all taxable sources anticipated for the year.
  • Next, estimate any adjustments to income they may be eligible for, such as deductions for contributions to a traditional IRA (if applicable, for instance, for a non-working spouse), health savings account (HSA) contributions, and if self-employed, the deduction for one-half of their self-employment tax.
  • Following this, retirees need to estimate their deductions, deciding whether to take the standard deduction or to itemize deductions. Seniors who are age 65 or older may be entitled to a higher standard deduction.
  • Once total deductions are estimated, they are subtracted from the estimated adjusted gross income (AGI) to arrive at the estimated taxable income.
  • The next step involves calculating the estimated income tax based on the estimated taxable income and the applicable tax brackets for their filing status for the current tax year.
  • After estimating their total tax liability, retirees should then estimate any tax credits they may be eligible for, such as the Credit for the Elderly or the Disabled  , or other credits like the retirement savings contributions credit (Saver’s Credit) if they are still contributing to retirement accounts. These credits directly reduce the amount of tax owed. The total estimated tax is then calculated by subtracting the total estimated tax credits from the total estimated tax liability.
  • Finally, retirees need to account for any anticipated tax withholding from sources like pensions, annuities, or Social Security benefits throughout the year. If the remaining tax liability, after subtracting withholding, is $1,000 or more, this is the estimated tax payment that will likely need to be made in four quarterly installments.

The worksheets included with the instructions for Form 1040-ES provide a structured framework to assist retirees in performing these calculations. Additionally, the IRS offers an online tool called the Tax Withholding Estimator, which can be particularly helpful for retirees in estimating the tax on their Social Security benefits and pension payments. Given the complexities involved, especially in the initial years of retirement or if a retiree’s financial situation is multifaceted, seeking guidance from a qualified tax advisor is highly recommended.

How do retirees pay their estimated taxes?

Estimated federal income taxes are generally due in four installments throughout the year  :

Payment PeriodDue Date
January 1–March 31April 15
April 1–May 31June 15
June 1–August 31September 15
September 1–Dec. 31January 15 of next year

Retirees have several options for paying their estimated federal income taxes to the IRS. One convenient method is IRS Direct Pay, which allows for electronic funds withdrawal directly from a checking or savings account without any fees. Payments can also be made using a debit card, credit card, or digital wallet through third-party payment processors authorized by the IRS, although these processors may charge a small convenience fee. For those who prefer traditional methods, payments can be made by mail by sending the Form 1040-ES payment voucher along with a check or money order payable to the U.S. Treasury to the address specified in the form instructions for their state.

Regardless of the payment method chosen, it is crucial to ensure that payments are made on time to avoid potential penalties for underpayment. Even if a retiree later overpays their taxes, penalties may still be assessed for underpayments made earlier in the year. While the standard payment schedule is quarterly, retirees have the option to pay more frequently, such as monthly or bi-weekly, as long as the total amount due for each quarter is paid by the respective deadline. This can aid in budgeting and managing cash flow throughout the year.

To summarize, understanding how to calculate and pay estimated federal taxes is a critical aspect of financial management for retirees. By determining whether estimated taxes are necessary, accurately calculating the estimated amount, paying on time through the various available methods, and exploring alternatives like adjusting withholding, retirees can fulfill their tax obligations effectively. Also, implementing smart tax planning strategies throughout retirement can potentially reduce their overall tax liability and simplify their tax management. Utilizing the wealth of resources provided by the IRS and considering professional advice when needed will empower retirees to navigate their tax responsibilities successfully and enjoy their retirement with greater financial peace of mind.

Please comment or send an email if you have any questions.

Joe Baker, CFP®

Baker Asset Management, LLC

joebaker@bakerassetmanagement.com
Using The VIX In Portfolio Management

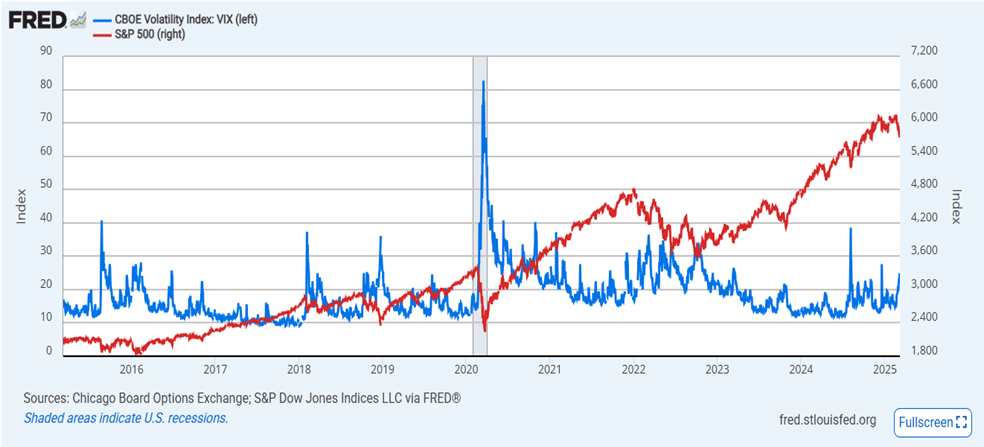
One of the metrics that I like to look at when assessing market risk is the CBOE Volatility Index, more commonly known as the VIX. The VIX measures the level of fear, anxiety, and/or uncertainty in the stock market. Technically, it looks at the options pricing of the S&P 500 index into the near future (about a month). When investors buy a lot of call options, meaning they expect the stock market to go up, the VIX drops. Conversely, when a lot of put options are bought, meaning people expect the stock market to drop, the VIX rises.

Of course, like everything else on Wall Street, there is a saying for the VIX: “When the VIX is high, it’s time to buy. When the VIX is low, look out below!” You’re probably thinking that this doesn’t make sense. A high VIX means there are a lot of pessimistic investors and so it would be bad for stocks. This is true but it is also true that the herd is usually wrong, so the VIX is normally interpreted as a contrarian indicator. This means when everyone is fearful, a high VIX, it’s probably not a bad time to buy stocks and vice versa.

Right now, we have a VIX of a little more than 26, a bit higher than what most investors consider a neutral VIX of 20. This makes sense because there is a lot of uncertainty in the market due to several of the current administration’s policies and there on again, off again status. I suspect that it will stay elevated until the chaos and confusion coming out of D.C. subsides.

An elevated VIX typically brings larger swings in stock market prices. For equity investors with a time horizon of three years or more, this volatility isn’t a big deal, as the major market indices have always trended up over time. For those with a shorter time period, they should have the money that they need in the near-term out of the stock market.

Using the VIX as part of your big picture view of the market’s risk is a useful data point to help with your portfolio management.

Please comment or send an email if you have any questions. Thanks!

Joe Baker, CFP®

Baker Asset Management, LLC

When Can I Get Rid of My Old Tax Documents?

It’s always a good time to go through your stuff and purge what you don’t need anymore. I know I have a few boxes of financial paperwork that need a good going-through to see if anything can be sent to the shredder. Regarding tax documents, there is always the question of how long do we have to keep this information. The good news is that the Internal Revenue Service has some guidelines that can help you sort what to keep and what to get rid of.

Here are some of the retention guidelines that the IRS recommends:

General Rule:

Keep records for 3 years from the date you filed your original return or 2 years from the date you paid the tax, whichever is later, if you file a claim for credit or refund.

Exceptions and Longer Retention:

  • Keep records for 7 years if you file a claim for a loss from worthless securities or bad debt deduction.
  • Keep records for 6 years if you do not report income that you should report, and it is more than 25% of the gross income shown on your return.
  • Keep records indefinitely if you do not file a return or if you file a fraudulent return.
  • Employment Tax Records: Keep employment tax records for at least 4 years after the date that the tax becomes due or is paid, whichever is later.

Property Records:

  • Keep records related to property until the period of limitations expires for the year in which you dispose of the property.
  • These records are essential for calculating depreciation, amortization, depletion, and gain or loss on sale.

Important Considerations:

  • Even after IRS requirements are met, consider if other entities (e.g., state where you file taxes, lenders, insurance companies) require longer retention.
  • When records are no longer needed, dispose of them securely, such as by shredding.

Please comment or send an email if you have any questions. Thanks!

Joe Baker, CFP®

Baker Asset Management, LLC

joebaker@bakerassetmanagement.com

Don’t Forget About Your Capital Loss Carryover When Filing Your 2024 Taxes This Year

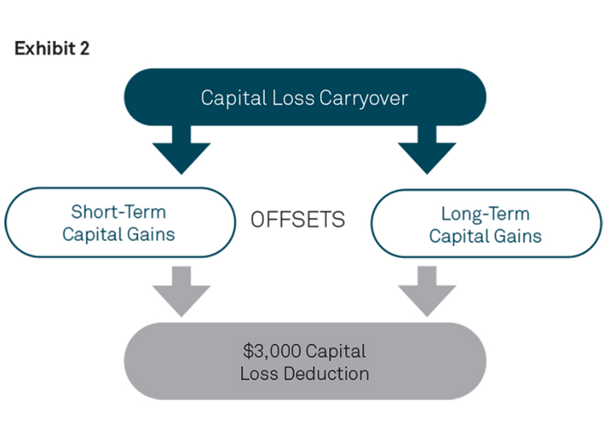
Most investors may not have to worry about capital loss carryover when filing their 2024 federal income taxes since the last two years have been extremely profitable for them. However, because 2022 was such a bad year for the markets, many investors who sold back then may have had more capital losses than capital gains for that year. The good news is that they could have used those excess losses to reduce their capital gains in 2023 and even some of their ordinary income (up to $3,000). If there were still losses left over, they can be used towards offsetting any realized capital gains in 2024 as well as $3,000 of ordinary income.

Capital loss carryover is a tax rule that lets you use investment losses from one year to reduce your taxable income in future years. Before going any further, keep in mind that this rule only applies to taxable accounts, not retirement accounts, such as IRAs.

Here’s how it works:

1. Calculating your net capital loss:

  • First, you need to calculate your net capital loss for the year. This is the difference between your capital gains (money you made on investments) and your capital losses (money you lost on investments). If it’s less than zero, meaning you have more losses than gains, you can offset some of your income.
  • You can only deduct up to a certain amount of net capital losses in a single year. This limit is currently $3,000.

2. Carryover of unused losses:

  • If your net capital loss is greater than the allowable deduction ($3,000), the unused portion automatically carries over to future tax years.
  • There is no time limit to how long you can carry over capital losses.
  • You can use the carryover to:
    • (1) Offset capital gains in future years.
    • (2) Deduct up to $3,000 against your ordinary income in future years.

3. Applying the carryover:

  • Each year, you calculate your net capital loss again, considering any new gains and losses.
  • You can use your current year’s net capital loss first to offset any capital gains you have.
  • Then, you can apply any remaining unused carryover from previous years to further reduce your taxable income.

4. Important points to remember:

  • Capital losses are categorized as short-term or long-term based on how long you held the investment before selling. Short-term losses can only offset short-term gains, while long-term losses can offset both short-term and long-term gains.
  • Wash sales are a strategy where you sell an investment at a loss and then repurchase it shortly after. This is generally not allowed and can prevent you from claiming the capital loss.
  • It’s important to keep accurate records of your capital gains and losses for tax purposes.

Here’s an example:

In 2022, you had $10,000 in capital losses and no capital gains. You deducted $3,000 of your losses to offset your ordinary income, and the remaining $7,000 carried over to 2023. In 2023, you had $3,000 in capital gains. You can first use your $7,000 loss carryover to completely offset these gains. You then have $4,000 remaining in your carryover that you can offset $3,000 of your ordinary income with, leaving you with $1,000 capital loss carryover to use to offset any gains in 2024.

I hope this explanation helps. Remember, it’s always a good idea to consult with a tax professional for advice specific to your situation.

Please comment or send an email if you have any questions. Thanks!

Joe Baker, CFP®

Baker Asset Management, LLC

joebaker@bakerassemanagement.com

A Little Known IRS Program That Can Make Tax Season Less Taxing

There is a program offered by the IRS that allows you to file your federal taxes through an associated tax preparer for free! The IRS Free File program is a public-private partnership between the IRS and a group of tax software companies called the Free File Alliance. It allows eligible taxpayers to prepare and file their federal income tax returns online for free. Here’s how it works:

1. Eligibility:

  • Income: The main requirement is your Adjusted Gross Income (AGI). For the 2024 tax year (filing in 2025), the AGI limit is $84,000. This applies to all filing statuses (single, married filing jointly, etc.).
  • Other factors: Some participating companies may have additional eligibility requirements, such as age or state residency.

2. Accessing Free File:

3. Preparing and Filing:

  • Create an account: Once you’ve chosen a provider, you’ll be redirected to their website to create an account.
  • Follow the instructions: The software will guide you through the process of entering your tax information.
  • File electronically: When you’re finished, the software will transmit your return electronically to the IRS.

Key Features of IRS Free File:

  • Free federal return: Participating companies cannot charge you to prepare and e-file your federal tax return if you qualify.
  • Guided experience: The software uses a question-and-answer format to help you complete your return accurately.
  • Error checks: Built-in checks help catch mistakes and ensure your return is complete.
  • Direct deposit: You can choose to receive your refund via direct deposit for faster processing.

Important Notes:

  • State taxes: While federal filing is free, some providers may charge for state tax preparation.14 Check with your chosen provider for details.
  • Support: The level of customer support offered may vary between providers.
  • Accuracy: Always review your return carefully before filing, even with the help of software.

This is a great service that is most certainly underutilized by eligible tax filers and can potentially save you some hard-earned cash.

Please comment or send an email if you have any questions.

Joe Baker, CFP®

Baker Asset Management, LLC

joebaker@bakerassetmanagement.com
US Balance Sheets Looking Strong Heading Into 2025

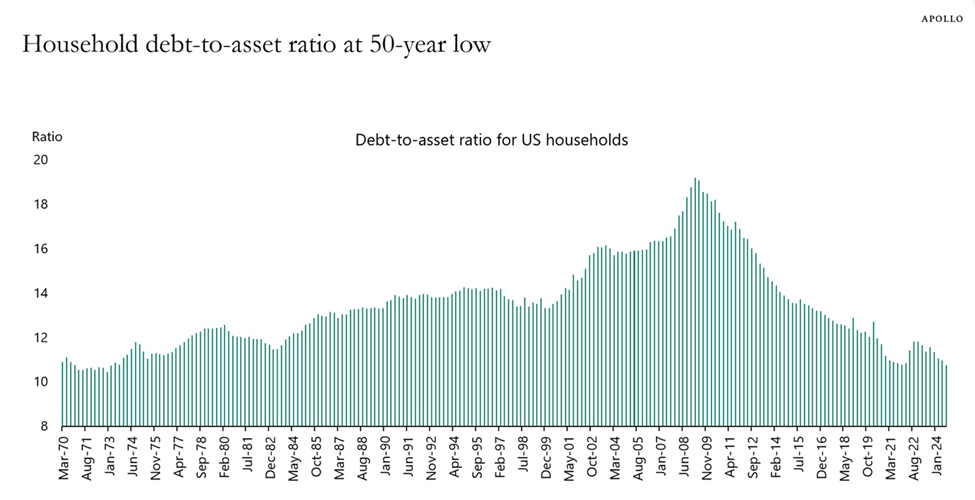
Financially speaking, U.S. households are looking strong heading into 2025. In fact, they have never looked better. Just check out the following chart to see how we are doing compared to the last 50 years:

Source: Federal Reserve, Haver Analytics, Apollo Chief Economist

As you can see, we have come quite a long way from the Great Financial Crisis era in 2008/2009 and are at levels that we haven’t seen since the early 1970’s. There are a few key reasons for such a strong showing:

  • Home prices have increased at a much faster rate over the past fifteen years than in the past. This has improved the asset side of the balance sheet.
  • More homes are now owned outright (no mortgage) or have mortgages at a 3% rate or lower than ever before. This has helped reduce household debt quite a bit.
  • Stellar stock market returns over the past two years have bolstered people’s retirement and investment accounts, thereby increasing their assets and subsequently, their net worth.

Can it keep going?

It’s possible. We still have a shortage of housing which will keep upward pressure on home prices. But mortgage rates are still relatively high which could increase the debt side of the balance sheet of new homeowners.

Regarding stocks, history is on our side. For instance, the S&P 500 has a history of delivering strong gains following two consecutive years of 20%+ gains, which we just had. Since 1950, there have been eight instances where the S&P 500 index has risen by 20% or more for two consecutive years. In six of those cases, the U.S. stock market achieved positive returns in the third year, with an average return of 12%.

Obviously, it’s always tough to predict what’s going to happen over the course of the next year but it’s good to know that we are in a great position now, regardless of what the future holds.

Please comment or send an email if you have any questions.

Joe Baker, CFP®

Baker Asset Management, LLC

joebaker@bakerassetmanagement.com
Monthly Update – January 2025

Calendar Notes

  • Wednesday, January 1st – New Year’s Day: Stock market is closed.
  • Thursday, January 9th – National Day of Mourning for President Jimmy Carter – Stock market is closed.
  • Monday, January 20th – Martin Luther King, Jr. Day – Stock market is closed.

Stocks seemed a bit tired in December as the year-end rally flamed out. I can’t blame them. They worked hard all year, and it showed, racking up a 20%+ return for the second year in a row. This hasn’t happened since the 1990’s, which sounds so long ago. The biggest catalysts for this performance were the continuing AI expansion on all fronts as well as inflation dropping substantially over the past year.

For the month, the S&P 500 dropped about 2.5%. However, it was still able to finish the year with a gain of over 23.3%.

Looking ahead, we will have Q4 earnings reports coming out in a few weeks. Also, Trump and his new administration will be coming in later this month. Finally, the Federal Reserve meets at the end of the month in a very cloudy interest-rate environment. Those are some pretty big catalysts that can move the markets, making for a very busy start to the year.

Historically, January has been a good month for stock performance. It has also been a pretty accurate indicator of how stocks will perform the rest of the year. For instance, when stocks have a positive January, full year returns have been positive 77% of the time. Let’s hope history repeats itself this month.

Take a look at the Outlook section below to see what events could move the markets over the short term.

Bond prices flip flopped once again, reflecting the uncertainty in the current interest rate environment. Both corporate and government bond prices fell during the month of December as new inflation data coming in showed that inflation is stickier than anyone expected. Still, the Federal Reserve did cut rates another 25 bps at their December meeting but where they go from here is anyone’s guess, including the Fed.

The 10-year US Treasury note yield finished higher in December, settling at about 4.57%, above the 4.18% that it was at the beginning of the month. The 30-year bond yield closed out the month at 4.79%, higher than the 4.37% that it was a month ago.

Bond investors are waiting with bated breath for the new administration to get in office and lay out their plans for trade and immigration policies, which will heavily influence the direction of bond prices and their yields. We should get some clarity on those issues by the end of the month.

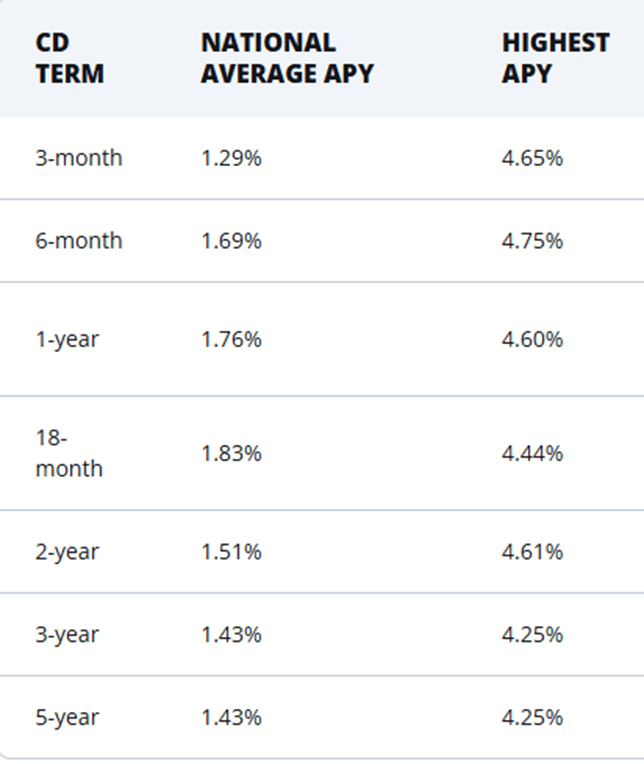
Savings rates either stopped dropping or even went up a little bit this past month. The change in direction is most likely due to the Fed’s talk of slowing down their pace of lowering short-term interest rates in 2025. The direction of where these rates are heading will continue to be uncertain until the inflation picture clears up, which will also depend on the incoming administration’s trade and immigration policies. That said, these rates are pretty good for savers and risk-averse investors. You can get above 4% return on your money currently. So, CDs and MMAs continue to be a great place to put your cash and your emergency fund, for now.

Now, take a look at the top rates for CDs and money market accounts (MMA):

MMA Rates

National AverageHigh Rate
0.66%5.00%

The best 1-year CD interest rate is currently at 4.60%, higher than last month. The best 5-year CD rate right now is around 4.25%, a 25-basis point rise from last month. Once again, MMA and traditional bank savings account rates changed very little from last month.

Savings rates are now in a holding pattern until we get a clearer picture on where interest rates are heading. This isn’t a bad thing, especially for risk-averse investors and savers. Knowing this, it makes sense in most situations to put cash that you don’t immediately need into CDs with up to 2-year maturities. For emergency cash, stick to high yielding money market and savings accounts, which are still yielding around 5%. As always, keep the total under $250,000 per person at any one bank to ensure you are fully covered by the FDIC.

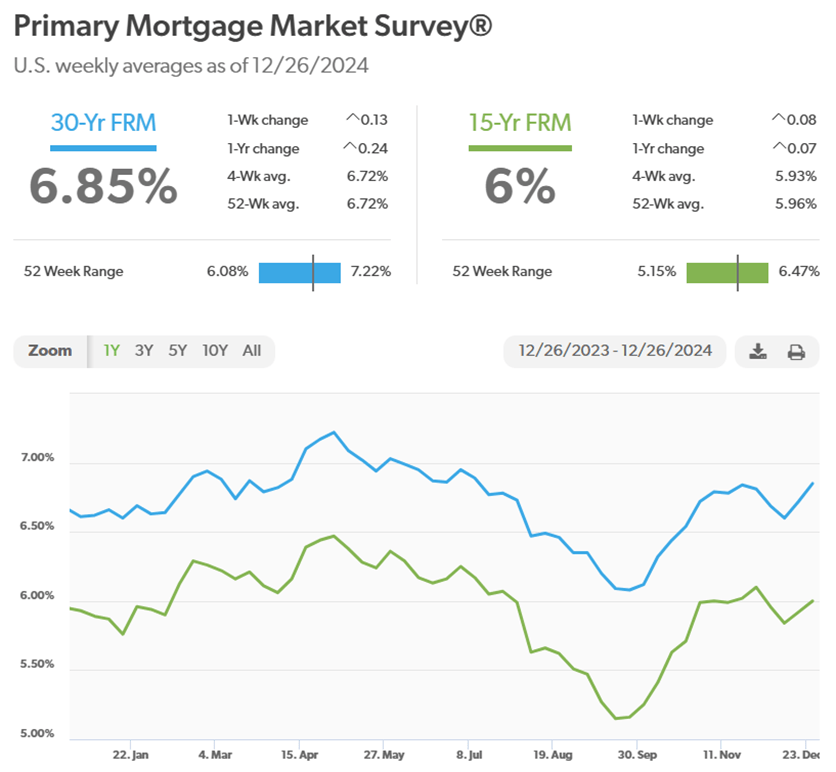
Mortgage rates stayed about the same as a month ago, with the 30-year loan getting ever so close to the 7% mark. Currently, the 30-year rate sits at 6.85%, slightly higher than a month ago, at 6.81%. There is still low inventory, especially for existing homes, so any drop in rates continues to be met with a quick surge in demand.

Oil prices headed higher as hopes of new drilling to lower oil prices were dashed by oil producers’ comments. It seems that these companies like high oil prices (shocking!) and don’t necessarily want to pump more oil. This is a global market that is motivated by profits, so it is difficult to tell them how much oil to produce unless they become operated by the government.

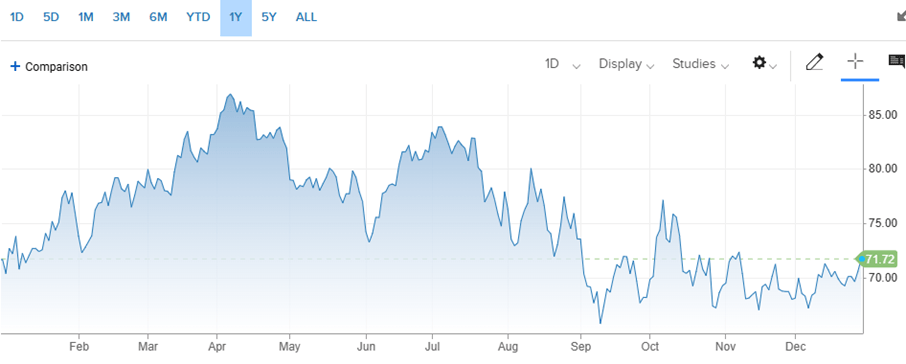
For the month, the price for a barrel of oil closed at $71.72, down from $68.15 at the beginning of December. For the year, prices ended right where they started in January. Getting oil prices below $70 for an extended period of time would help greatly in lowering the overall inflation rate.

Here’s a look at the one-year chart for U.S. oil:

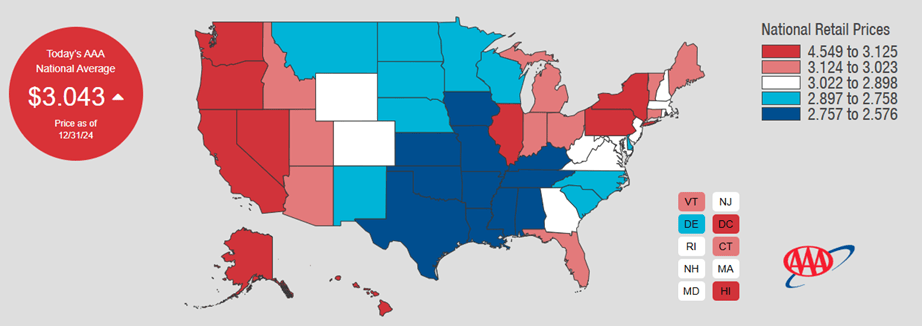
Gasoline prices lagged the rise in oil prices and fell once again in December, albeit barely. Regular unleaded gasoline is now averaging $3.04 per gallon, down from $3.06 last month. Oklahoma has the cheapest gas currently, checking in at $2.58 a gallon. Hawaii has the most expensive gasoline at $4.55 per gallon. FYI, a year ago, we were paying $3.11.

Check out the prices at the pump in your area: AAA Gas Prices.

Outlook

Events on the horizon that could move the markets in the near term:

  • Fed & Inflation: The Federal Reserve cut interest rates by another 25 basis points at their last meeting of 2024 a few weeks ago. They did state that they might not be as aggressive in cutting rates in 2025 as they thought just a few months ago. I believe they want to let the new administration get settled in to see what policies they plan to implement, particularly tariffs and mass deportation, since these could have a significant impact on inflation. We could know as soon as the end of this month so volatility in the stock and bond markets may be higher than normal this January.

Joe Baker, CFP®

Baker Asset Management, LLC

joebaker@bakerassetmanagement.com
What Is A Wash Sale When Selling Stocks?

This is the time of year that many investors sell some loser investments to offset their income or other capital gains, sometimes referred to as tax-loss harvesting. There is an obscure tax rule, known as the wash sale rule, that could affect how the IRS views these trades. So, here is a brief summary of how the wash sale rule works.

The wash sale rule was designed to discourage people from selling securities at a loss simply to claim a tax benefit.

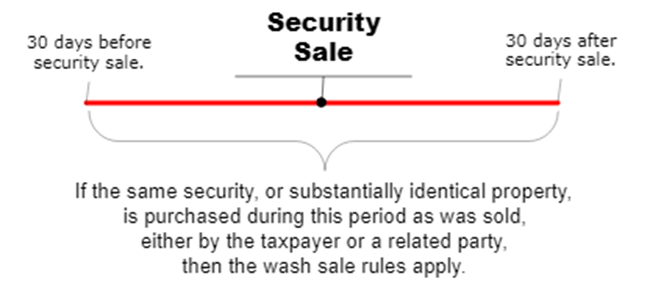
A wash sale occurs when an investment is sold at a loss and, within a period of 30 days before or 30 days after the sale, the identical or “substantially identical” investment is purchased again.

Under such circumstances, that loss will be “disallowed” and may not be considered in calculating a taxpayer’s losses for income tax purposes.

An example is the easiest way to explain this rule:

Suppose Joe has a taxable brokerage account that holds 50 shares of XYZ stock with a cost basis of $500 because he bought the stock when it cost $10 per share. The stock is worth only $5 per share on July 31, and he sells all 50 shares for a total sales proceeds of $250. Joe now has a realized capital loss of $250.

If Joe purchases new shares in XYZ within 30 calendar days before the sale or up to 30 calendar days after the sale, his capital loss can’t be used to offset income or capital gains for that tax year but is deferred until he sells the new, replacement shares.

As you can see in the example, you temporarily lose the tax benefit of the realized loss, but you get it back when you eventually sell the newly purchased shares because you add the original capital loss to the new purchase price to establish your actual cost basis for the newly purchased shares. The only time that you lose the loss permanently is when you sell an investment in a taxable account, and you buy it back in an IRA.

If it sounds confusing, don’t worry. It is. That’s our tax code.

Please comment or send an email if you have any questions. Thanks!

Joe Baker, CFP®

Baker Asset Management, LLC

joebaker@bakerassetmanagement.com
Tax Loss Harvesting (TLH) – What It Is and When To Do It

Tax loss harvesting (TLH) is a term used in the financial industry to describe strategies employed by investors to minimize their taxes due on any realized gains of investment sales for the year. Realized gains occur when you sell an investment at a higher price than when you bought it.

Before reading any further, please note that TLH only applies to investments in taxable accounts, not retirement accounts or any other tax-deferred accounts. That said, let’s take a look at what this harvesting is all about.

I think an example is the best way to understand how this strategy works:

Suppose you sold shares of XYZ earlier this year for a $10,000 profit, also known as a realized gain. Let’s say that you also have a stinker, ABC, in your account that is down $15,000 from when you bought it. You can sell ABC and now have a realized loss of $15,000. This will offset the $10,000 realized gain. It will also offset up to $5,000 of any other realized gains that you have this year. If you don’t have any other gains, you can apply $3,000 to reduce your taxable income and the remaining $2,000 of losses can be carried forward to next year.

In this example, you were able to avoid paying taxes on that gain of $10,000 by using the TLH strategy.

Most investors prefer to do this strategy towards the end of the year, but you can do it any time during the calendar year. I like to do it for my clients during the slow summer months because that is one less thing to worry about during crunch time in December.

I also want to share with you some do’s and don’ts when you are considering TLH:

  1. Don’t sell losers just to offset gains. Make sure that the investment no longer fits with your investment objectives.
  2. Considering #1 above, do maximize your tax savings by using TLH when you have short term capital gains, since they are taxed at your ordinary income tax rate, which may be much higher than the long-term capital gain tax rate.
  3. Do sell losers if they no longer fit your strategy, even if you don’t have any gains to offset. You can always carry the losses forward to use in later years.
  4. Don’t buy the same investment within 30 days before or after the TLH sale. If you do, this will disallow the loss.
  5. Don’t ever consider any tax strategy, such as TLH, as the sole reason to buy or sell any investment. They should be incorporated into your investment decisions as part of your overall game plan.

Please comment or send an email if you have any questions.

Joe Baker, CFP®
Baker Asset Management, LLC
joebaker@bakerassetmanagement.com