Using The VIX In Portfolio Management

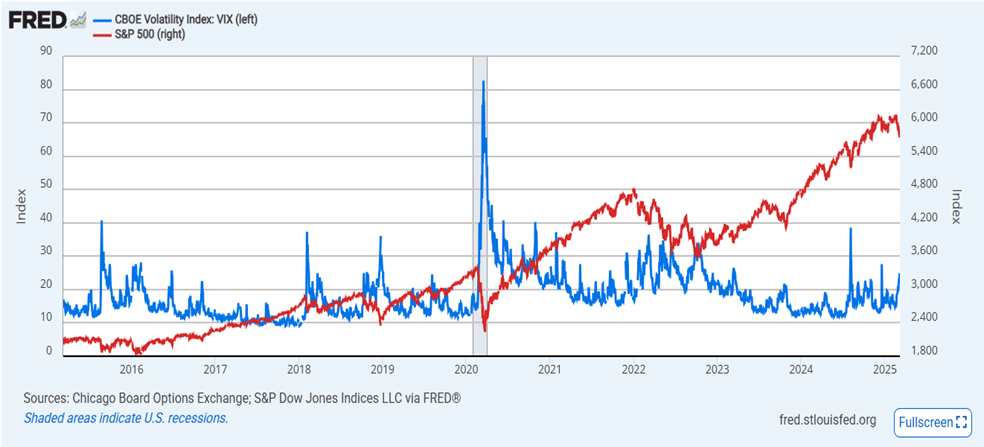
One of the metrics that I like to look at when assessing market risk is the CBOE Volatility Index, more commonly known as the VIX. The VIX measures the level of fear, anxiety, and/or uncertainty in the stock market. Technically, it looks at the options pricing of the S&P 500 index into the near future (about a month). When investors buy a lot of call options, meaning they expect the stock market to go up, the VIX drops. Conversely, when a lot of put options are bought, meaning people expect the stock market to drop, the VIX rises.

Of course, like everything else on Wall Street, there is a saying for the VIX: “When the VIX is high, it’s time to buy. When the VIX is low, look out below!” You’re probably thinking that this doesn’t make sense. A high VIX means there are a lot of pessimistic investors and so it would be bad for stocks. This is true but it is also true that the herd is usually wrong, so the VIX is normally interpreted as a contrarian indicator. This means when everyone is fearful, a high VIX, it’s probably not a bad time to buy stocks and vice versa.

Right now, we have a VIX of a little more than 26, a bit higher than what most investors consider a neutral VIX of 20. This makes sense because there is a lot of uncertainty in the market due to several of the current administration’s policies and there on again, off again status. I suspect that it will stay elevated until the chaos and confusion coming out of D.C. subsides.

An elevated VIX typically brings larger swings in stock market prices. For equity investors with a time horizon of three years or more, this volatility isn’t a big deal, as the major market indices have always trended up over time. For those with a shorter time period, they should have the money that they need in the near-term out of the stock market.

Using the VIX as part of your big picture view of the market’s risk is a useful data point to help with your portfolio management.

Please comment or send an email if you have any questions. Thanks!

Joe Baker, CFP®

Baker Asset Management, LLC
A Little Known IRS Program That Can Make Tax Season Less Taxing

There is a program offered by the IRS that allows you to file your federal taxes through an associated tax preparer for free! The IRS Free File program is a public-private partnership between the IRS and a group of tax software companies called the Free File Alliance. It allows eligible taxpayers to prepare and file their federal income tax returns online for free. Here’s how it works:

1. Eligibility:

  • Income: The main requirement is your Adjusted Gross Income (AGI). For the 2024 tax year (filing in 2025), the AGI limit is $84,000. This applies to all filing statuses (single, married filing jointly, etc.).
  • Other factors: Some participating companies may have additional eligibility requirements, such as age or state residency.

2. Accessing Free File:

3. Preparing and Filing:

  • Create an account: Once you’ve chosen a provider, you’ll be redirected to their website to create an account.
  • Follow the instructions: The software will guide you through the process of entering your tax information.
  • File electronically: When you’re finished, the software will transmit your return electronically to the IRS.

Key Features of IRS Free File:

  • Free federal return: Participating companies cannot charge you to prepare and e-file your federal tax return if you qualify.
  • Guided experience: The software uses a question-and-answer format to help you complete your return accurately.
  • Error checks: Built-in checks help catch mistakes and ensure your return is complete.
  • Direct deposit: You can choose to receive your refund via direct deposit for faster processing.

Important Notes:

  • State taxes: While federal filing is free, some providers may charge for state tax preparation.14 Check with your chosen provider for details.
  • Support: The level of customer support offered may vary between providers.
  • Accuracy: Always review your return carefully before filing, even with the help of software.

This is a great service that is most certainly underutilized by eligible tax filers and can potentially save you some hard-earned cash.

Please comment or send an email if you have any questions.

Joe Baker, CFP®

Baker Asset Management, LLC

joebaker@bakerassetmanagement.com

US Balance Sheets Looking Strong Heading Into 2025

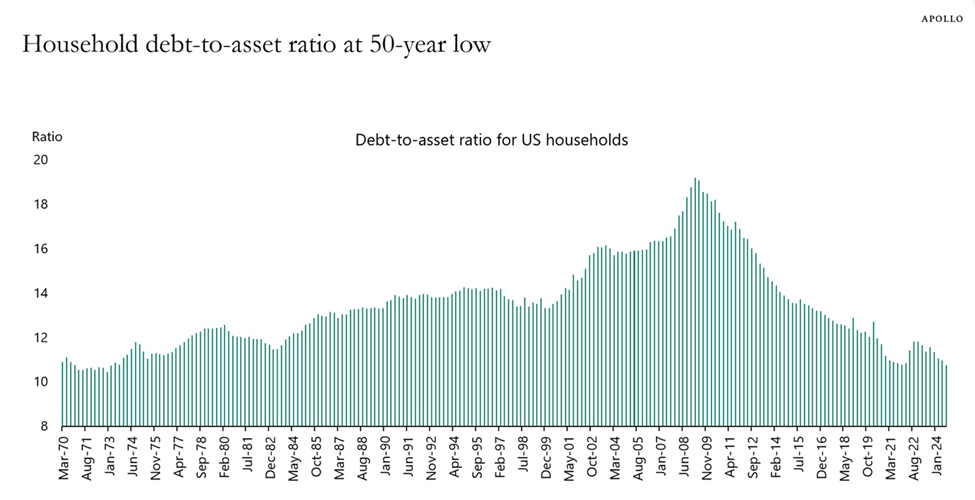
Financially speaking, U.S. households are looking strong heading into 2025. In fact, they have never looked better. Just check out the following chart to see how we are doing compared to the last 50 years:

Source: Federal Reserve, Haver Analytics, Apollo Chief Economist

As you can see, we have come quite a long way from the Great Financial Crisis era in 2008/2009 and are at levels that we haven’t seen since the early 1970’s. There are a few key reasons for such a strong showing:

  • Home prices have increased at a much faster rate over the past fifteen years than in the past. This has improved the asset side of the balance sheet.
  • More homes are now owned outright (no mortgage) or have mortgages at a 3% rate or lower than ever before. This has helped reduce household debt quite a bit.
  • Stellar stock market returns over the past two years have bolstered people’s retirement and investment accounts, thereby increasing their assets and subsequently, their net worth.

Can it keep going?

It’s possible. We still have a shortage of housing which will keep upward pressure on home prices. But mortgage rates are still relatively high which could increase the debt side of the balance sheet of new homeowners.

Regarding stocks, history is on our side. For instance, the S&P 500 has a history of delivering strong gains following two consecutive years of 20%+ gains, which we just had. Since 1950, there have been eight instances where the S&P 500 index has risen by 20% or more for two consecutive years. In six of those cases, the U.S. stock market achieved positive returns in the third year, with an average return of 12%.

Obviously, it’s always tough to predict what’s going to happen over the course of the next year but it’s good to know that we are in a great position now, regardless of what the future holds.

Please comment or send an email if you have any questions.

Joe Baker, CFP®

Baker Asset Management, LLC

joebaker@bakerassetmanagement.com

What Is A Wash Sale When Selling Stocks?

This is the time of year that many investors sell some loser investments to offset their income or other capital gains, sometimes referred to as tax-loss harvesting. There is an obscure tax rule, known as the wash sale rule, that could affect how the IRS views these trades. So, here is a brief summary of how the wash sale rule works.

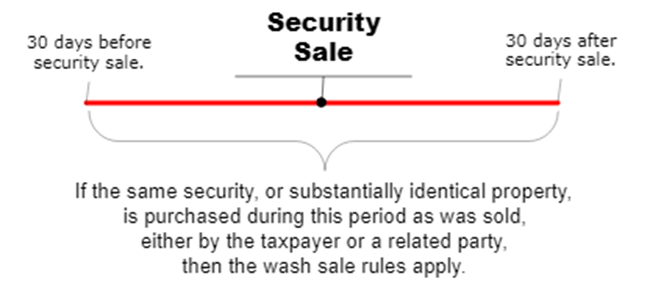
The wash sale rule was designed to discourage people from selling securities at a loss simply to claim a tax benefit.

A wash sale occurs when an investment is sold at a loss and, within a period of 30 days before or 30 days after the sale, the identical or “substantially identical” investment is purchased again.

Under such circumstances, that loss will be “disallowed” and may not be considered in calculating a taxpayer’s losses for income tax purposes.

An example is the easiest way to explain this rule:

Suppose Joe has a taxable brokerage account that holds 50 shares of XYZ stock with a cost basis of $500 because he bought the stock when it cost $10 per share. The stock is worth only $5 per share on July 31, and he sells all 50 shares for a total sales proceeds of $250. Joe now has a realized capital loss of $250.

If Joe purchases new shares in XYZ within 30 calendar days before the sale or up to 30 calendar days after the sale, his capital loss can’t be used to offset income or capital gains for that tax year but is deferred until he sells the new, replacement shares.

As you can see in the example, you temporarily lose the tax benefit of the realized loss, but you get it back when you eventually sell the newly purchased shares because you add the original capital loss to the new purchase price to establish your actual cost basis for the newly purchased shares. The only time that you lose the loss permanently is when you sell an investment in a taxable account, and you buy it back in an IRA.

If it sounds confusing, don’t worry. It is. That’s our tax code.

Please comment or send an email if you have any questions. Thanks!

Joe Baker, CFP®

Baker Asset Management, LLC
joebaker@bakerassetmanagement.com

How Long Will This Bull Market Last?

We recently hit the two-year anniversary of the current bull market in stocks. As a refresher, a bull market happens when stock prices have gone up 20% or more from the previous low for a sustained period of time. The current bull market started on October 12, 2022, and is being sustained by an expanding economy, low unemployment, and, most recently, falling interest rates.

Two years seems like a pretty long time for stocks to go up consistently, so how long can we expect this bull market to last? There’s no fool-proof way to determine the length of a bull market with any accuracy but we can look at historical data to see how long they have lasted in the past.

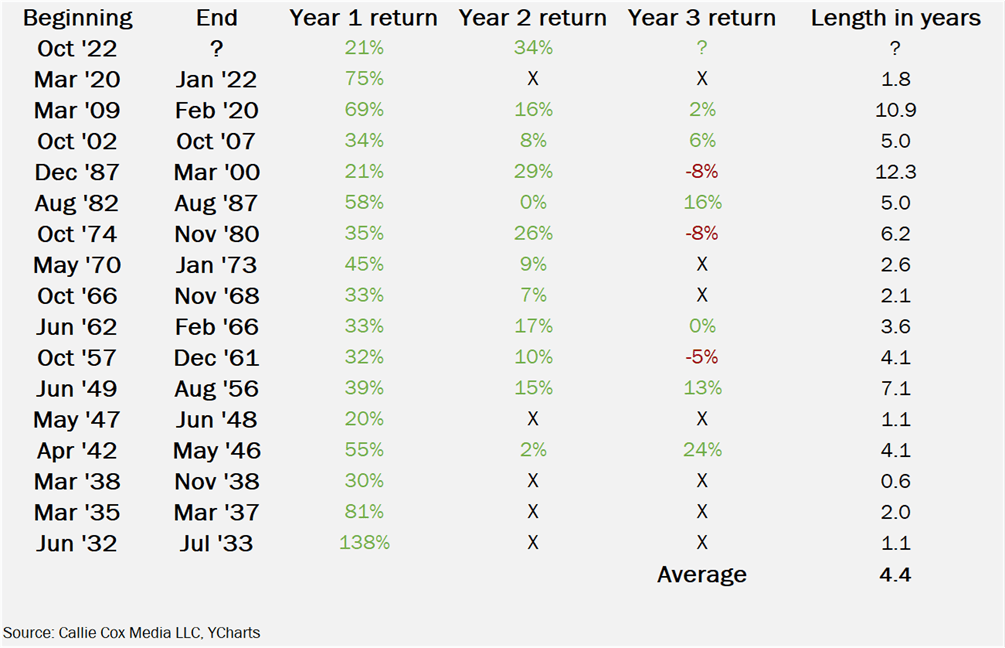
The table below shows all the bull markets of the S&P 500 index since the early 1930’s.

As you can see, bull markets have averaged almost 4.5 years in length so there’s a good chance that this bull market still has a ways to go. Of course, there are always unknown events that could throw a wrench into this bull, and don’t forget about an election that’s only a few weeks away that could stir up some volatility.

Please comment or send an email if you have any questions.

Joe Baker, CFP®

Baker Asset Management, LLC
joebaker@bakerassemanagement.com

What History Tells Us About Stock Performance in the 4th Quarter

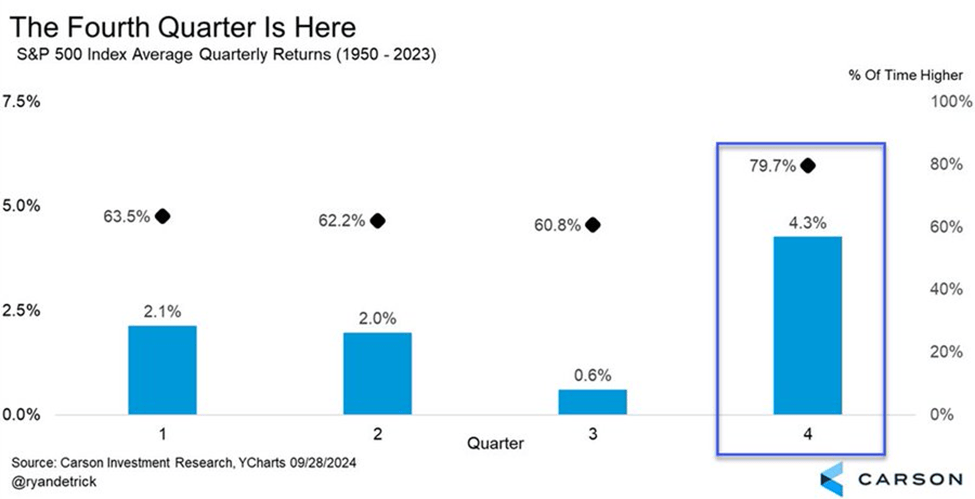
History tells us that the fourth quarter of the year is typically a very good time to be invested in stocks. Take a look at this chart:

As you can see, the S&P 500 index has an average return of 4.3% in the fourth quarter over the past seventy-three years. This is more than twice as good a return as any other quarter of the year.

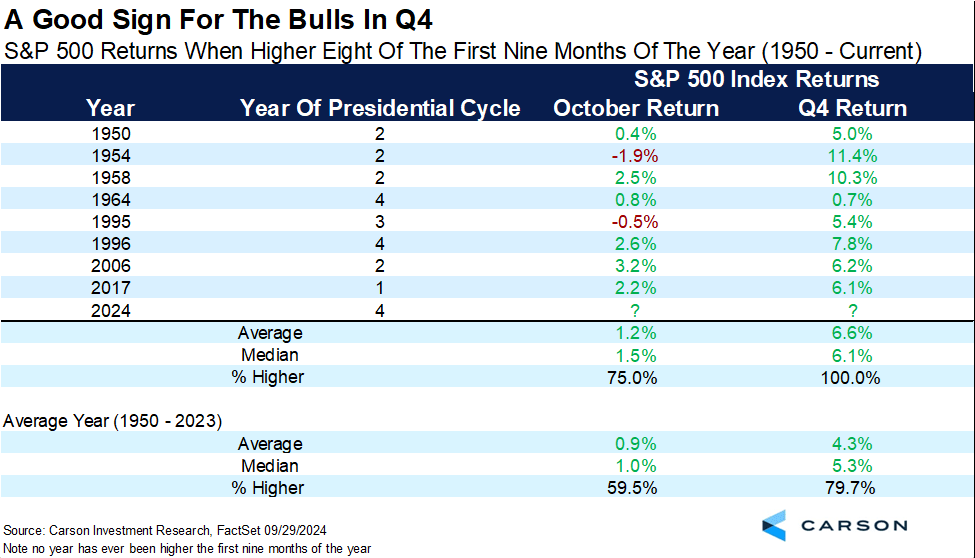
Historical data gets even better for stock market bulls when it comes to this year. When the S&P 500 index is higher the first eight of the nine months of a year, like it has been in 2024, then the fourth quarter is positive every single time (8 for 8), with an average gain of 6.6%. FYI, the index has never been up each of the first nine months of a year. This year, April has been the only down month.

I have to hedge this blog by stating that the upcoming election could have a greater influence on the markets than any other election in recent history. Even so, if history repeats itself, or at least rhymes, we should expect a pretty good quarter for the stock market to finish out 2024.

Please comment or send an email if you have any questions.

Joe Baker, CFP®

Baker Asset Management, LLC
joebaker@bakerassemanagement.com

Our Current Economy in Charts

I recently took a look at a whole bunch of economic data charts compiled by economists and strategists from the financial world. Much of this information shows that the U.S. economy can still achieve a soft landing coming out of the interest rate hiking cycle of the past few years.

Regarding the stock market, there are mixed reviews with some showing further room to run in this current bull market while others expect a pullback, especially with uncertainty picking up as we approach the November elections.

Here are a few of those charts that I wanted you to see:

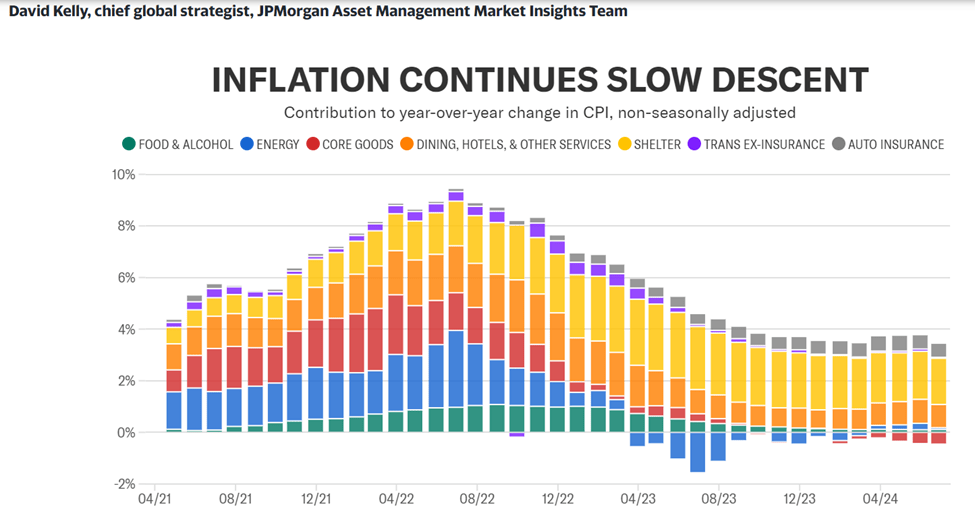
Shelter and auto insurance have been the two stubborn pieces of inflation that haven’t subsided yet. The good news is that rents and mortgage rates are rising much slower or even dropping in some areas, which should help get inflation down to the Federal Reserve’s target of 2% sometime in 2025.

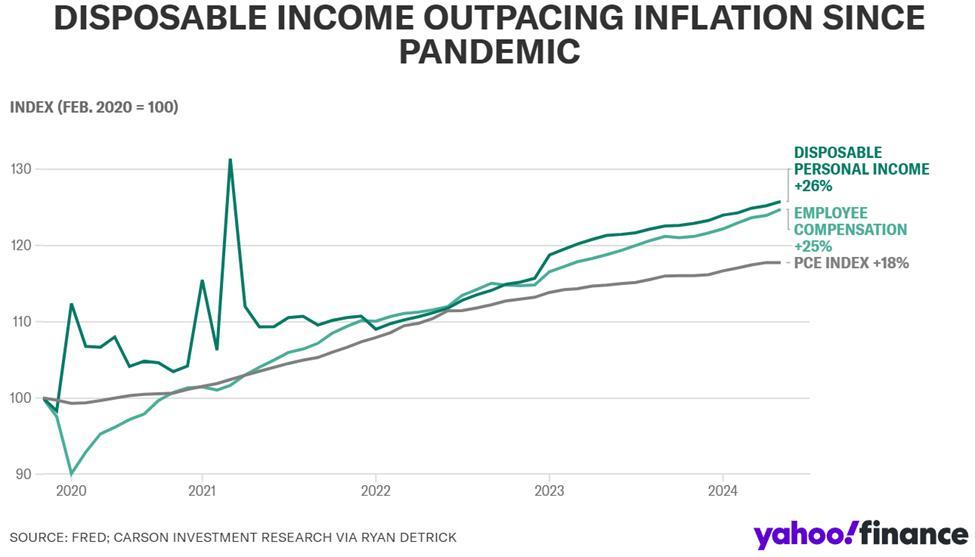
Because inflation has taken up all the oxygen in the room over the past few years, disposable income outpacing inflation is not a well-known statistic, but here it is. Both employee compensation and disposable personal income have increased more than inflation since the pandemic. Also, inflation is expected to continue to drop through the rest of this year, so consumers should see their disposable income increase, assuming their salaries remain the same.

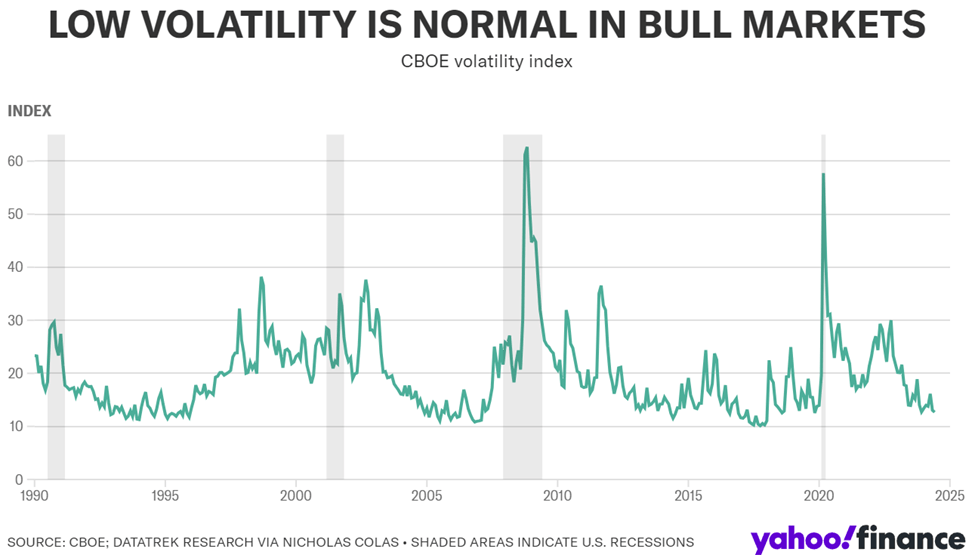
Chicago Board Options Exchange (CBOE) Volatility Index, more commonly known as the VIX, is an options-based measure of expected S&P 500 volatility over the next 30 days. When this indicator is consistently below 20, stocks tend to perform well. This was the case in the mid-1990s, mid-2000s, and much of the 2010s. When the VIX spikes, it is an indicator of a recession, of which the four most recent are shown as the shaded regions in the chart above. So, we could be in a period of low VIX, which is good for stocks, or about to enter a period where the VIX spikes. Interest rate and election forces will be what moves this index through the rest of this year.

To summarize, the economy and markets have done well so far in 2024 but it feels like we are at an inflection point now. The two big influencers are interest rates and the elections. These will dictate how we finish up in 2024. It should be an interesting ride into the end of the year.

Please comment or send an email if you have any questions.

Joe Baker, CFP®

Baker Asset Management, LLC
joebaker@bakerassemanagement.com

Dot Com Vs. AI Era Comparison

I thought it would be interesting to take a look at the late 1990’s Dot Com era and see how it compares to the current AI era. There are some similarities that I see, particularly with investors’ mindsets, that make me think history will repeat itself. But there are also some key differences that could keep the AI era from suffering the same fate as the Dot com era. Here’s what I am seeing:

What’s the same

Transformational Change – In the 90’s, the internet was changing how businesses interacted with customers. We went from going to brick and mortar stores to sitting at a computer to transact business. Today, AI is involved not only on the transactional side of business, but also the marketing, manufacturing, research, and almost every aspect of business today.

Fear Of Missing Out (FOMO) – You couldn’t go to a party, restaurant or pretty much any social gathering without hearing someone talk about how well their Dot Com investments were doing. This caused a great deal of FOMO among both retail and institutional investors. If there was a “.com” at the end of a company’s name, you wanted to own its stock. Now, investors are lining up to buy any company that is involved in AI infrastructure and willing to pay a premium for them.

What’s different

Earnings – The Dot Com era ushered in an incredible number of companies that went public based on hype and the promise of amazing revenue and profits. Many had no revenue but the push to get their stock publicly traded was so great that they rushed to the markets. The insanity was that investors couldn’t get enough of them. Of course, once reality set in, these companies went bankrupt, and investors lost everything. Now, most companies involved in AI are already well established (Microsoft, Amazon, Google, Nvidia, Meta, etc.) and are very profitable already.

Behind the Scenes – AI is helping make companies more efficient, productive, and profitable by improving operations and procedures behind the scenes. It is involved in almost every aspect of a company’s business whereas in the Dot Com era, the internet was more concentrated in just the sales and marketing sectors.

Far Reaching – Back in the 90’s the internet focused mainly on the interphase between businesses and consumers. Today, AI is not only involved there, it is changing nearly every aspect of every industry. In health care for instance, AI can read x-rays, CAT scans, and biopsy slides with incredible accuracy, detecting and diagnosing diseases faster. In the forest fire arena, AI is now being used to detect fires much quicker than humanly possible. California has 1,000 cameras monitoring their forests using AI. The money, manpower, and property saved by employing AI is immense. Now, extrapolate that across every industry and you can see why AI is a game changer.

That being said, it does seem that the markets might be getting ahead of themselves in this AI era. But it is nowhere near the frenzied euphoria that caused the Dot Com era bubble to burst…..for now.

Please comment or send an email if you have any questions.

Joe Baker, CFP®

Baker Asset Management, LLC
joebaker@bakerassemanagement.com

Must See Stock Charts During Presidential Election Years

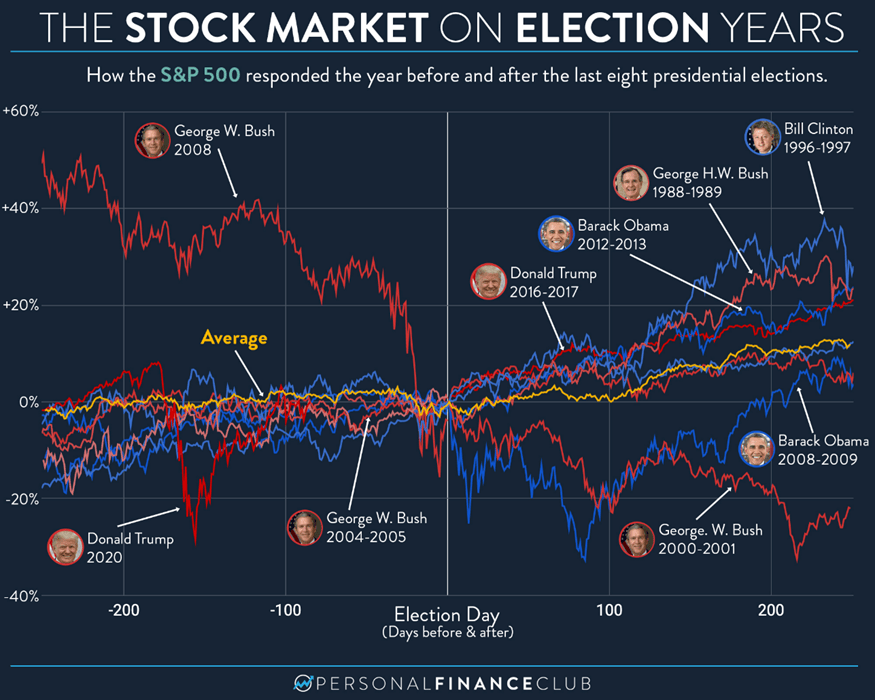
I saw some interesting charts in the past week that illustrate stock performance in a presidential election year.

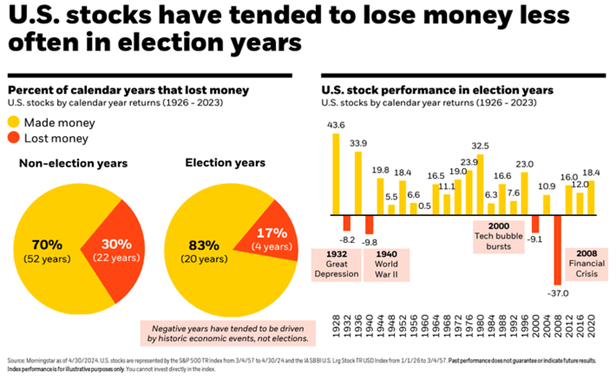
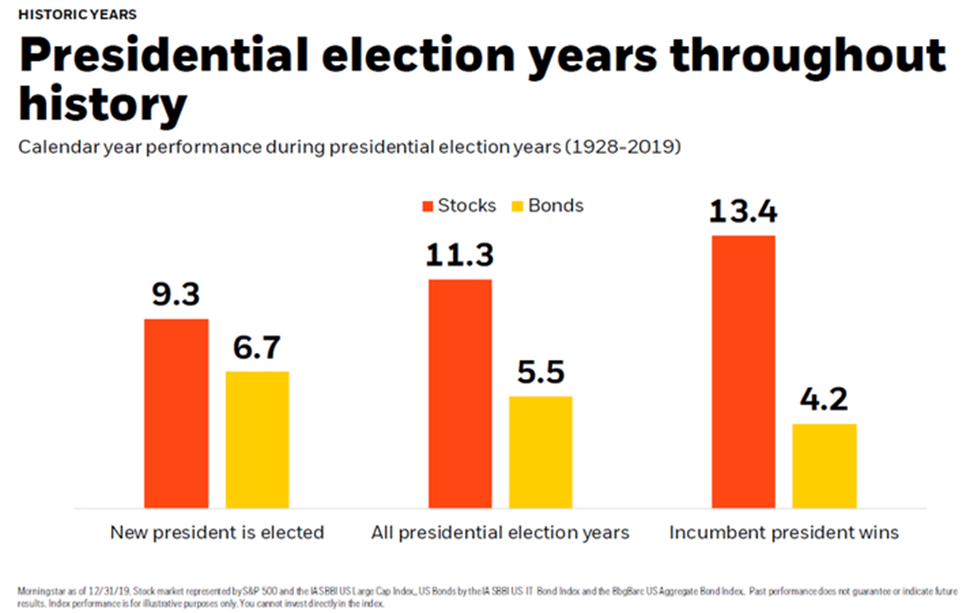
First, in the chart above, you can see that stocks have performed well in past presidential election years. The four years that stocks had negative returns included some very significant economic and geopolitical events that contributed to their poor performance.

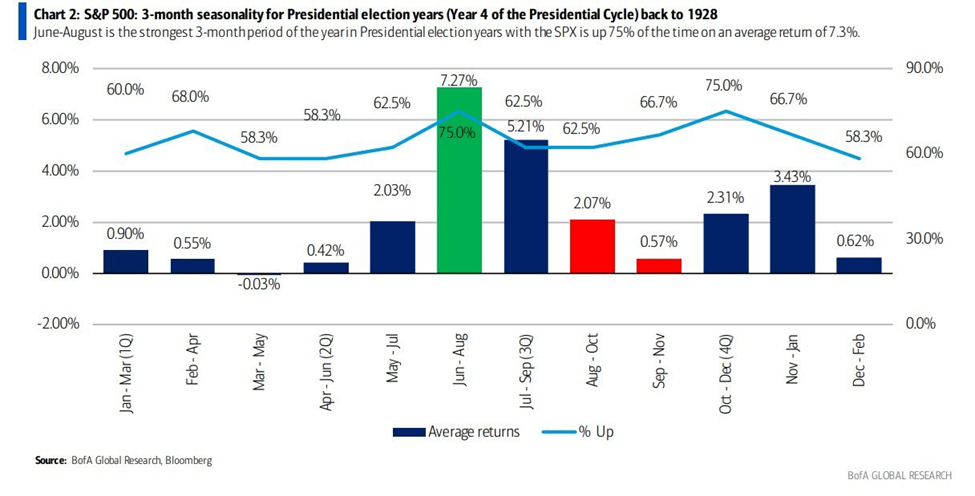
This next chart shows how stocks performed during every rolling three month stretch in an election year going all the way back to 1928. As you can see, the June, July, and August stretch is the best performing with a positive return 75% of the time and an average return of almost 7.3%.

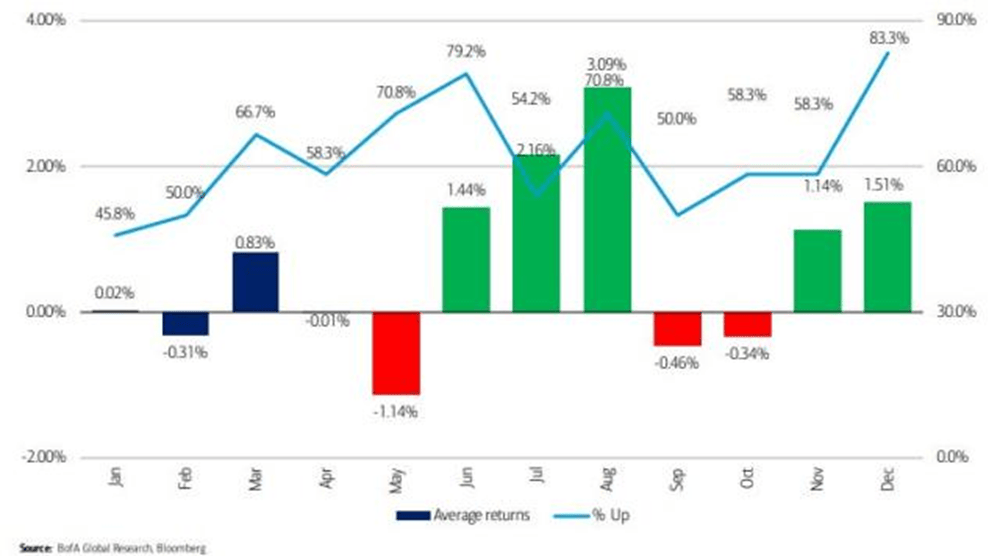
The last chart simply shows the performance of stocks during each month of a presidential election year going back to 1928.

So, it seems that summertime is the best time to be invested in the stock market during a presidential election year. However, we are currently at or near all-time highs in most stock indices and appear to be ripe for a pullback in stock prices. It will be interesting to see if this historical trend can hold up with such a positive return in stocks preceding it over the last eighteen months.

Please comment or send an email if you have any questions.

Joe Baker, CFP®

Baker Asset Management, LLC
joebaker@bakerassemanagement.com

How Stocks Perform In Presidential Election Years

Besides interest rates and The Federal Reserve, stock market volatility is going to be heavily influenced by the presidential election this November. And it’s not going to wait until Fall. Headlines are going to be filled with polls, debates, and trials from now until election day (and beyond, I’m sure). I have always felt that elections are just short-term catalysts, both positive and negative, for stocks and Presidents don’t really have an affect on stock prices. It will still hold true this year. However, I suspect there will be much more volatility due to politics than normal, especially with addition of the Trump trials to the landscape.

So, let’s take a look at how markets have performed historically in a presidential election year:

  • Historically, the S&P 500 has averaged a 7% gain during U.S. presidential election years since 1952. This is lower than the average annual gain of around 10% but still positive.
  • Re-election years: Markets tend to perform better in re-election years (such as this year), with the S&P 500 averaging a 12.2% gain since 1952. This could be due to an incumbent president’s focus on maintaining stability and avoiding major policy changes.
  • Party control: The party in control of Congress doesn’t seem to have a significant impact on market performance. However, major policy changes proposed by either party can cause uncertainty and volatility.
  • Economic conditions: The overall health of the economy has a much stronger influence on the stock market than the election itself. Strong economic growth and low inflation are typically associated with positive market returns.

Historically, stocks perform the best when an incumbent president wins and the opposite party controls at least one  section of Congress, either the House of Representatives or the Senate. But this shouldn’t influence your investment strategy for the long term. Holding high-quality, well-run companies will serve you well regardless of the political climate.

Please comment or send an email if you have any questions.

Joe Baker, CFP®

Baker Asset Management, LLC
joebaker@bakerassetmanagement.com