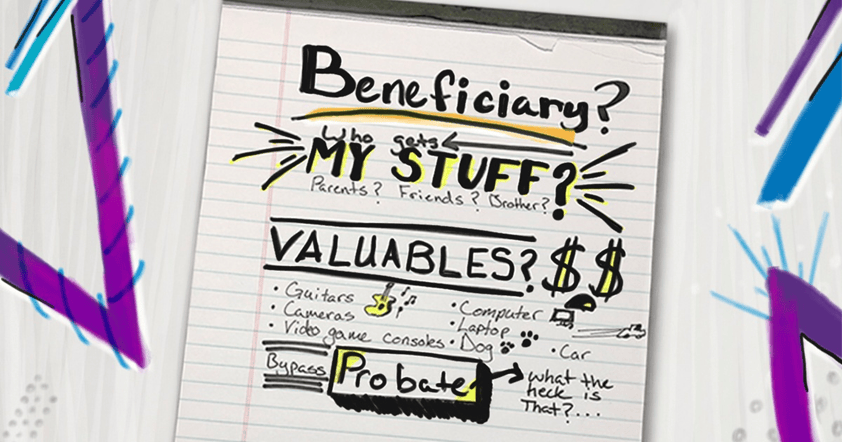
Talking about your beneficiaries means talking about death, specifically your death. Planning for your death may sound like the worst thing ever but it is really an incredibly thoughtful act on your part and will help to minimize stress for your family and loved ones when you ultimately check out.
Beneficiaries are typically assigned to retirement accounts (401k, IRAs, etc.), life insurance and annuity policies, as well as transfer-on-death (TOD) accounts. Naming beneficiaries on these accounts allow these assets to avoid the probate process after your death. If you don’t name any beneficiaries, these accounts will be passed on to your estate where they will go through probate based on your state laws. Probate is a legal proceeding that determines who will get your stuff. It is a lengthy, complex process that can be pretty expensive.
If you have a will, probate will use that to determine how your assets get divvied up. If you don’t have a will, also known as intestate, the state will do the best they can to determine who gets what. Suffice it to say, naming beneficiaries is the way to go. Getting this done before you pass away will make things simpler, quicker, and cheaper for your heirs during a very stressful time.
Naming beneficiaries can also be a very simple and inexpensive estate plan for most people, especially if you title your real estate property as a TOD asset.
You should name both primary and contingent beneficiaries. The primary beneficiary is first in line to receive your assets. If the primary beneficiary passes away before you, the contingent beneficiary will receive those assets, depending on your selection of per capita or per stirpes (see explanation below). You can have as many primary and contingent beneficiaries as you want.
Now, here is the most overlooked section of the beneficiary page: Choosing per stirpes or per capita.
Per stirpes (derived from the Latin word for roots) means that if a beneficiary dies before you die, the deceased beneficiary’s children inherit your money.
Per capita (Latin for each head) means that if a beneficiary dies before you die, their share of the inheritance goes back to the estate and gets divided among the other living beneficiaries.
Choosing which one of these for your beneficiaries is very important and should be considered carefully. In the most basic instance, you should elect per stirpes on your beneficiary designations to ensure that your heirs’ heirs receive their share.
I mentioned transfer-on-death (TOD) accounts earlier and just wanted to review what they are and when to use them. TOD is used for taxable accounts, and it allows you to assign beneficiaries just as you do with retirement accounts, annuities, and life insurance. This allows your taxable accounts to bypass the probate process, which is quicker, cheaper, and less stressful for your heirs.
Also, there are about 25 states that currently offer a TOD deed for real estate property. This is a huge time and money saver for your heirs because the property automatically passes down to your beneficiaries named on the deed.
Finally, remember to review your beneficiaries at least annually and certainly after any major life events, such as death, divorce, marriage, adoption, etc.
Please comment or send an email if you have any questions.
Joe Baker, CFP®
Baker Asset Management, LLC
joebaker@bakerassetmanagement.com