
We are fast approaching the final quarter of 2023, so I wanted to make sure that you are on track to maximize your contributions to your retirement plan(s).
For all W-2 employees, the quickest way to check if you are on track is to take a look at your last paystub. Find the amount that you have contributed to your plan so far this year. Take that amount and subtract it from the maximum contribution shown in the table below that corresponds with your retirement plan. Be sure to include the catch-up amount if you are age 50 or over as of December 31st of 2023. The result is the remaining amount needed to max out your employee contributions for the year. If you take this number and divided it by the number of pay periods that you have left in the year, you will get the amount that needs to come out of each of your remaining paychecks to hit your 2023 contribution limit. Compare this number with what is actually being taken out and if the current amount being taken out is greater, then you’re good to go. If it is less, then you should adjust your contributions accordingly. Here’s a quick example:
Mary is age 55 and has contributed $20,000 to her 401k through September 30th, or $1,111.11 per paycheck ($20,000/18 pay periods). She has 6 pay periods left in 2023, which equates to a total of $6,666.66 in contributions for the rest of the year, giving her a total of $26,666.66 in contributions for 2023.
To maximize her contributions, Mary can contribute a total of $30,000 in 2023. So, she will be short $3,333.34 ($30,000.00 – $26,666.66) unless she increases her contributions. Therefore, she should change her contributions to $1,666.66 per pay period if she wants to maximize her annual contributions.
Maximum Employee Contributions for Retirement Plans
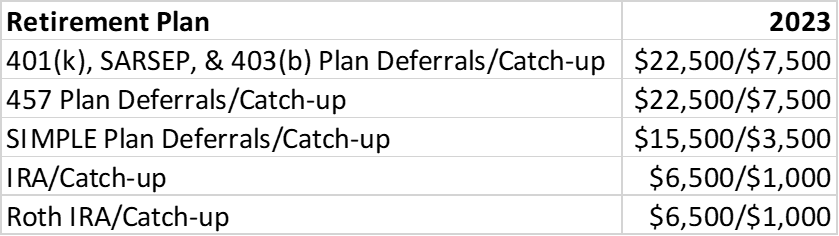
Note: Catch-up contributions are allowed for those employees that turn age 50 at any time in the year that they are contributing.
Check with your retirement plan advisor or your payroll department to confirm how much you need to contribute by the end of the year to max out your 2023 contributions.
Please comment or email me if you have any questions.
Joe Baker, CFP®
Baker Asset Management, LLC
joebaker@bakerassetmanagement.com

