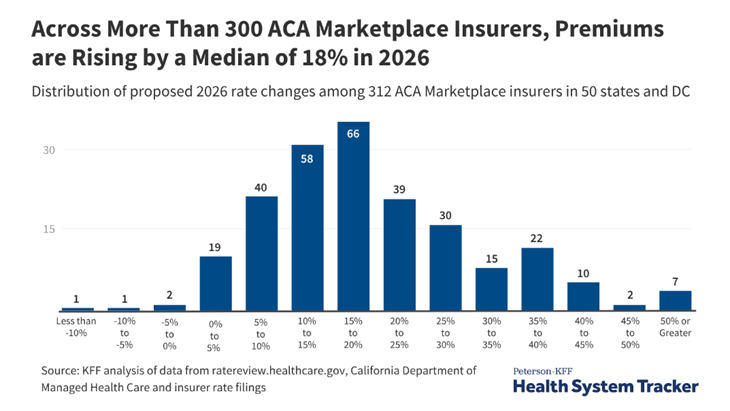
Starting this year, the landscape of the Affordable Care Act (ACA) has shifted dramatically. With the expiration of temporary enhancements, millions of Americans are now facing a return to the strict “subsidy cliff,” where earning just a dollar over the income limit means losing all premium assistance. So, let’s take a look at the new 2026 rules, including the specific income thresholds that trigger a full repayment “clawback,” and identify some of the ways that you can lower your Modified Adjusted Gross Income (MAGI), maintain essential subsidies, and avoid a massive tax bill.
For 2026, Affordable Care Act (ACA) premium tax credits have reverted to pre-2021 rules following the expiration of temporary enhancements. Subsidies are now generally limited to individuals and families with household incomes between 100% and 400% of the Federal Poverty Level (FPL).
2026 Income Limits for Subsidies
Based on 2025 Federal Poverty Guidelines used for 2026 coverage, the income ranges for eligibility in most states are:
| Household Size | Lower Limit (100% FPL) | Upper Limit (400% FPL) |
| Single Person | $15,650 | $62,600 |
| Family of Four | $32,150 | $128,600 |
If the income that you provided on the healthcare.gov (ACA) site falls within the range above, you will receive a healthcare premium subsidy. The amount will vary based on where your income falls within these ranges.
For 2026, the maximum percentage of income you must pay for a benchmark plan is as follows:
- 100% to 133% FPL: Premiums are limited to approximately 2.1% to 3.14% of your annual income.
- 300% to 400% FPL: Premiums are capped at approximately 9.96% of your income.
- Above 400% FPL: The “subsidy cliff” has returned; households earning even $1 over this limit are generally responsible for 100% of their premiums, with no federal tax credits available.
The subsidy covers the difference between the actual cost of the plan and your required income-based contribution. For example, a family of four earning $45,000 (roughly 140% FPL) might pay about $1,607 annually for their premium in 2026, whereas under previous enhanced rules, they might have paid $0.
In 2026, avoiding an ACA subsidy “clawback” (repaying excess tax credits) is critical because the repayment caps that previously protected low-income households have been eliminated. You are now responsible for repaying the full amount of any excess subsidy received.
The following strategies can help you manage your income and eligibility to prevent a large tax bill:
1. Reduce Your Modified Adjusted Gross Income (MAGI)
Since subsidies are based on your MAGI, lowering this figure can increase your credit or keep you under the “subsidy cliff” ($62,600 for individuals; $128,600 for a family of four).
- Maximize Contributions to Pre-Tax Retirement Accounts: Contributions to a Traditional IRA, 401(k), or 403(b) directly reduce your MAGI.
- Maximize HSA Contributions: Starting in 2026, all Bronze and catastrophic plans are automatically eligible for a Health Savings Account (HSA). Contributing to your HSA reduces your MAGI dollar-for-dollar.
- Harvest Investment Losses: If you have stocks or bonds that have lost value, selling them can offset capital gains and reduce your income by up to an additional $3,000.
2. Strategic Income Management
- Update the Marketplace Immediately: Report any raises, new jobs, or household changes (like a child moving out) to HealthCare.gov as soon as possible. The Marketplace will adjust your monthly credit in real-time to match your new income, preventing a lump-sum debt at tax time.
- Use Roth Accounts for Extra Cash: If you need more money during the year, withdraw from a Roth IRA or Roth 401(k). Because these are funded with after-tax dollars, qualified withdrawals do not count as income and will not trigger a clawback.
- Underestimate with Caution: If you are unsure of your income, you can choose to take only a portion of your subsidy upfront (e.g., take 75% of the credit monthly and claim the remaining 25% as a refund when you file).
3. Timing and “Bunching”
- Time Large Income Events: If possible, postpone large capital gains, property sales, or Roth conversions until a year when you are not using ACA coverage or have reached Medicare age.
- Make Last-Minute Adjustments: You have until April 15, 2027, to make 2026 contributions to an IRA or HSA. This allows you to calculate your exact 2026 income during tax season and make a final contribution to lower your MAGI and reduce what you owe back to the IRS.
Careful income planning is crucial under the 2026 ACA rules. By maximizing pre-tax contributions, managing income events, and keeping your income information updated with the Marketplace, you can preserve your health insurance subsidies and avoid unexpected tax bills.
Please comment or send an email if you have any questions.
Joe Baker, CFP®
Baker Asset Management, LLC
joebaker@bakerassetmanagement.com