
Fun Facts about December
- Birthstone: Turquoise, Blue Topaz, and Tanzanite
- Flower: Holly and Narcissus
- Zodiac signs: Sagittarius and Capricorn
- December in the Northern Hemisphere is similar to June in the Southern Hemisphere.
- Hanukkah starts on Thursday, the 7th, through Friday, the 15th.
- Thursday, the 21st, is the winter solstice, which marks the shortest day of the year in the northern hemisphere. It is also the start of the winter season.
- Christmas is on Monday, the 25th. All stock and bond markets are closed.
- New Year’s Eve is on Sunday, the 31st.
Stocks broke their three-month losing streak and bolted higher this past month with one of their best showings for November in recent years. Q3 earnings have all been reported for almost all major corporations. Also, the battle in Gaza quieted down quickly and the Ukraine/Russia war has had no surprises recently, so investors have been focusing strictly on inflation and the Federal Reserve. Nearly all of the economic data coming in has been pointing to cooling inflation which is what the Fed intended with its rate hikes over the last few years. As such, investors are betting that the Fed is done raising rates and that has been the major catalyst for stocks rising in November.
The S&P 500 for the first time in five months, finishing up 8.9%. That is the best month for the index in 2023 so far and one of the best Novembers for the S&P 500 ever. For the year, it is up about 19.3%, By the way, the average return in November has been 0.90% since 1928.
Based on November, it looks like the Santa Claus rally has started early. Stocks have a couple of good things going for them right now. First, this is a good time of the year to be invested in the stock market, historically speaking. Second, the artificial intelligence (AI) revolution is legit, and the U.S. is home to some of the best companies to capitalize on it. Finally, if the Fed holds rates steady at their next meeting in mid-December, we could see a strong finish into the end of the year.
Take a look at the Outlook section below to see what events could move the markets over the short term.
Bond prices reversed course after a four-month decline and headed higher in November. This went for bonds across the entire debt universe as inflation continues to cool down across the globe. The Fed held steady on rates after their November meeting, and it looks like they are going to do the same at their last meeting of the year in a few weeks.
The 10-year US Treasury note yield dropped over 50 basis points to close out November at 4.34%. The 30-year bond yield fell about 50 bps, closing the month at 4.50%. We still have an inverted yield curve, which historically has preceded a recession, but there are some signs that point to a soft landing for the economy, which would be great for everybody and a huge pat on the back for the Federal Reserve.
Bond buyers should continue to focus on bonds with short-term maturities. I would keep maturities under 18 months and just plan on holding these bonds to maturity. That way, you won’t have to worry about selling at a discount if interest rates head higher. If rates do start to drop, you can sell the bonds at a profit since their price will rise as their yield drops.
Savings rates continued to rise in November, but only slightly. Are they at the top or just taking a breather? Only time will tell but if the data continues to show inflation has peaked, this could be the highs that we’ll see in savings rates for a while. Having said that, these rates are fantastic for our risk-averse investors out there and for anyone with cash in savings, money market, and CD accounts. These rates are a legitimate alternative to stocks and bonds and will keep pressure on those markets until we see this trend reverse.
Now, take a look at the top rates for CDs and money market accounts (MMA):
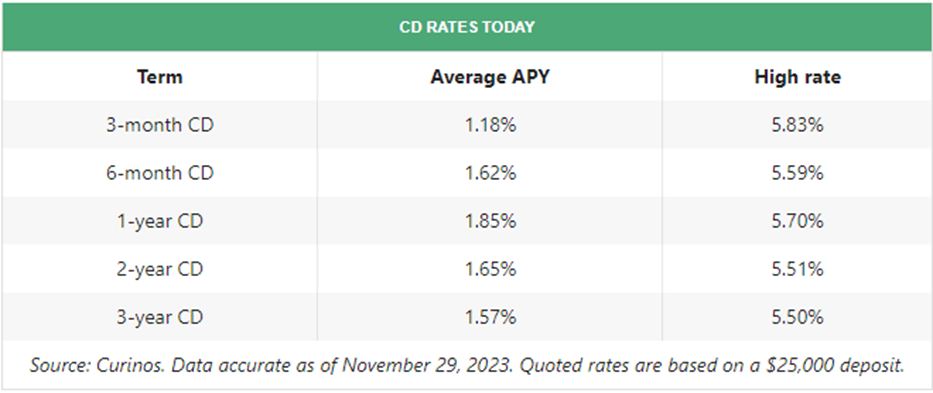
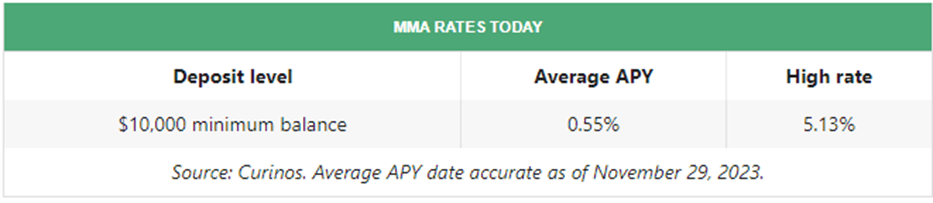
The best 1-year CD interest rate is currently at 5.70%. The best 5-year CD rate right now is right around 5.65%. These rates are still inverted, but are close to even now, which means that they are continuing to normalize. We are getting closer to the point where buying longer-term maturity bonds and CDs will make sense but for now, I would still put my savings or emergency spending money into short-term CDs, 1 year or less, and reevaluate when they mature. If you’d rather have more liquidity, look into an MMA (still yielding over 5% currently). Keep the total under $250,000 per person at any one bank to ensure you are fully covered by the FDIC. As I mentioned above, CDs and MMAs have become nice alternatives for risk-averse investors and have drawn money away from stocks because of their relatively high rates that carry virtually no risk.
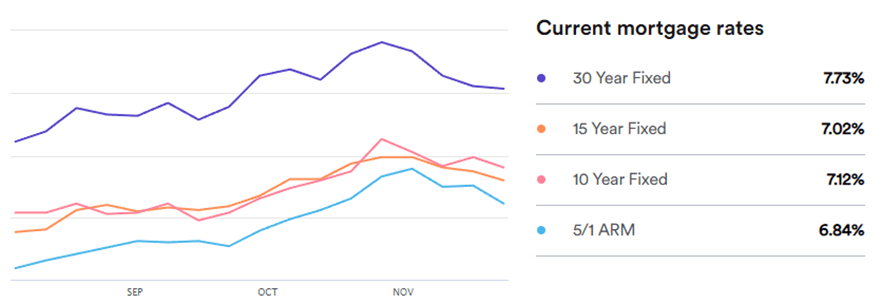
Mortgage rates finally took a breather and headed lower in November. Currently, the 30-year rate sits at 7.73%, much lower than what it was a month ago, at 8.09%. This trend looks like it could continue based on the current yield path of the 10-year treasury bond, which has the biggest influence on mortgage rates.
Even with this drop in mortgage rates, existing home sales are still going to be lower than normal since most homeowners who want to move are sitting tight with their 2-3% mortgage rate loans. For new homes, raw material prices, such as lumber and copper, have come down some so that should help lower pricing on newly built homes. Of course, location plays a big factor in pricing as well.
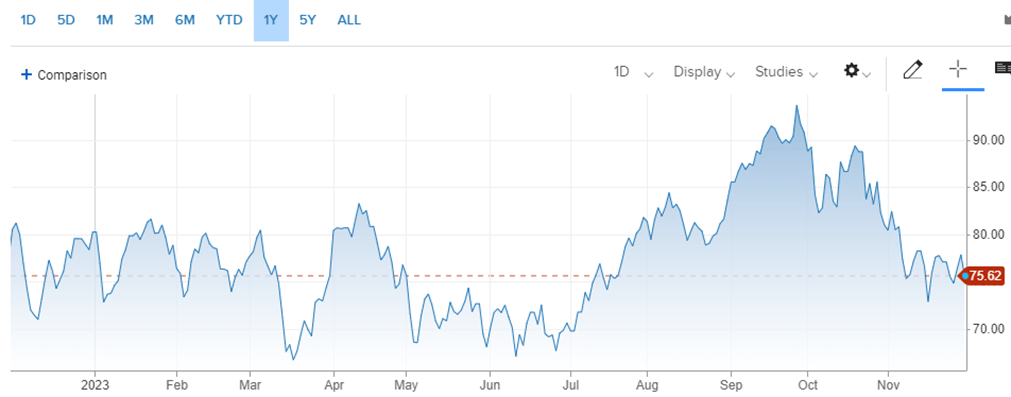
Oil prices declined for the second month in a row in November despite all of the chaos happening in the Middle East. I think the price may have run up too far in anticipation of China’s economy recovering faster than it has and has pulled back some to get more in line with reality. The U.S. doesn’t seem to have let up on fuel usage based on recent travel and shipping data. For the month, the price for a barrel of oil settled around $75.62, down from $81.20 at the beginning of November. Hopefully, we can keep this trend going and get prices down closer to $70.
Here’s a look at the one-year chart for U.S. oil:
Gasoline prices continued to drop in November, to the delight of travelers during the Thanksgiving holiday. Regular unleaded gasoline is now averaging $3.25 per gallon, down from $3.48 last month. Texas has the cheapest gas currently, checking in at $2.75 a gallon. California has the most expensive gasoline at $4.85 per gallon. FYI, a year ago, we were paying $3.52.
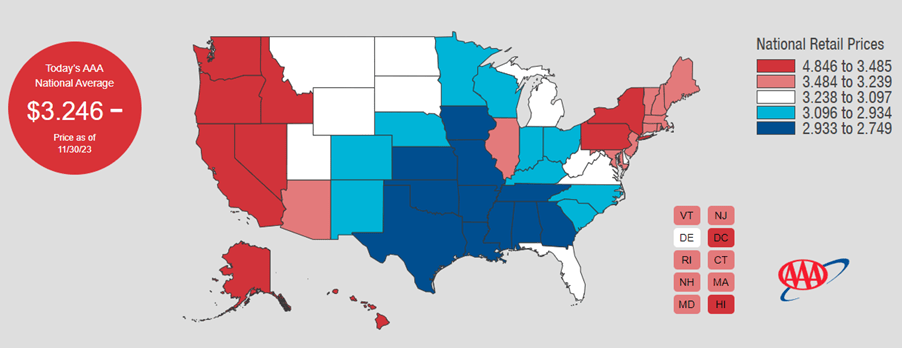
Check out the prices at the pump in your area: AAA Gas Prices.
Outlook
Events on the horizon that could move the markets in the near term:
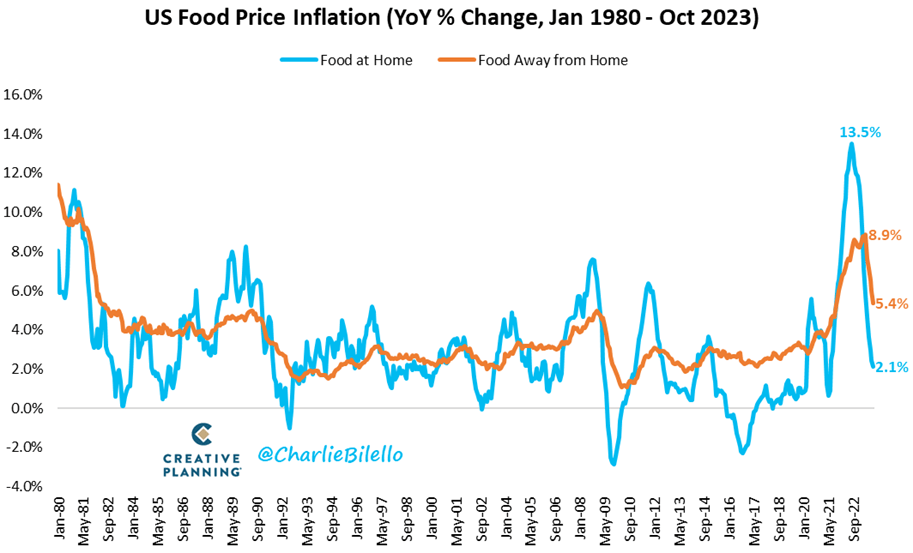
- Fed & Inflation: The data coming in on inflation keeps looking better and better. For instance, here’s a chart showing food inflation over the last 43 years. As you can see, inflation for food-at-home prices (groceries) has dropped to 2.1% from a peak last year of 13.5%. Inflation for food-away-from-home prices (restaurants) has dropped quite a bit as well. If these rates stay at least flat, it will go a long way in convincing the Federal Reserve that their work is done fighting inflation, and we shouldn’t see any more interest rate increases in the near future. This is positive for both the stock and bond markets in the near term.
- Green Shoots for Most Americans: Some encouraging data have recently come out showing that most Americans are better off financially now than before the pandemic and that’s true across all demographic and income groups. Here are some highlights:
- Millions more good jobs.
- Bigger paychecks, even after inflation.
- Consumer spending is back to a strong pre-Covid trend.
- Historic increases in wealth, including at the bottom.
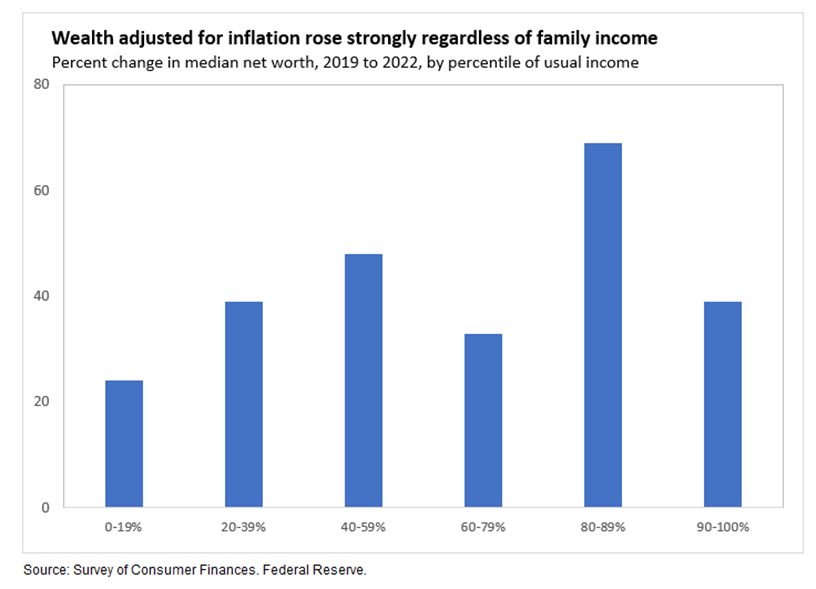
All of this points to positive catalysts for stocks over the next six months and I don’t believe that this good news has been fully priced into the market yet.
- Savings Rates Peak: This may be a little farther out than a few months but if savings rates are close to peaking right now and start to come down, there could be a ton of money that will shift from money markets and maturing bonds into stocks. This could easily fund the next leg up for stocks over the next 12-18 months.
Joe Baker, CFP®
Baker Asset Management, LLC
joebaker@bakerassetmanagement.com

