
The IRS has just set the new contribution limits for retirement plans for 2023 and there are some big increases regarding how much that you can contribute. The big jump in contributions limits is mostly due to the high inflation that we are experiencing this year.
Here are the new limits:
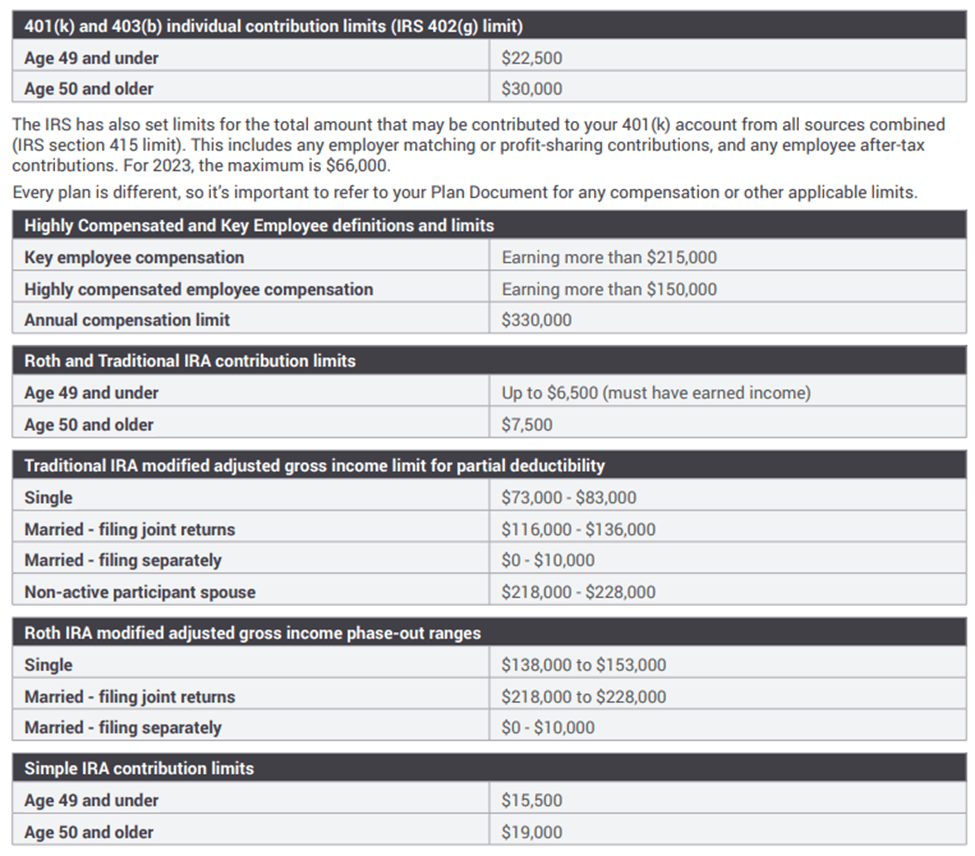
With respect to IRAs, here are some additional notes:
For most people your modified adjusted gross income, or MAGI, is the same as your adjusted gross income, which can be found on the front page of form 1040.
Traditional IRA
- The limits shown above are for those people that are covered by a retirement plan at work. If you have no plan at work, your IRA contribution is always fully deductible, regardless of how much you earn.
- If you’re single and your MAGI is less than $73,000, you can get the full tax deduction.
- If you’re married and your MAGI is less than $116,000, you can get the full tax deduction.
Roth IRA
- If you’re single and your MAGI is less than $138,000, you can contribute the full amount allowed, $6,500 or $7,500 if over age 50.
- If you’re married and your MAGI is less than $218,000, you can contribute the full amount allowed, $6,500 or $7,500 if over age 50.
Depending on your situation, it might make sense to contribute to both a traditional IRA and a Roth IRA. Your total contributions to both are still capped at the allowable limits for a single IRA.
Please comment or send an email if you have any questions. Thanks!
Joe Baker, CFP®
Baker Asset Management, LLC
joebaker@bakerassetmanagement.com

