
Stocks made it 2 months in a row of positive returns, with the S&P 500 rising about 3% in February. It’s still off the highs from last September but the comeback from the Christmas lows is pretty incredible. Check this chart out of the S&P 500 over the last 6 months (it bottoms out on Christmas Eve 2018):
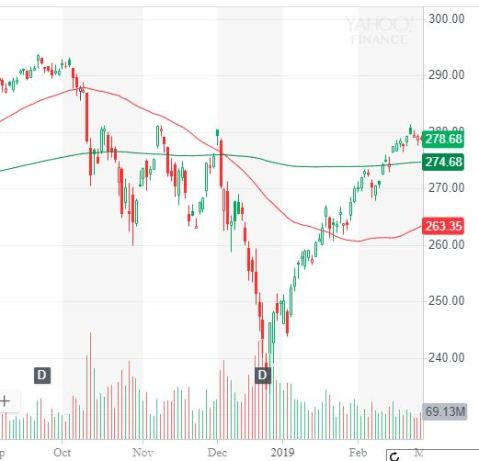
The markets can’t keep this pace up so expect a pause or a pullback in the near future, as this is a normal market reaction. The catalyst for this will most likely be one of the events that I talk about in the Outlook section below.
Bonds had a mixed performance in February. Low risk government bond prices were flat for the month but corporate bonds had some nice gains. I think this is a continuation from January when the Fed stated they would put the brakes on any more rate increases. In this environment, it is a good idea to own bonds that mature in 1 or 2 years and to hold them to maturity. That way, you don’t have to worry as much about big price moves while you own the bond.
Interest rates seem to have stalled out since their big rise last year. A pause was definitely needed and it is a healthy and normal reaction in the current economic environment. So, if you are investing in bonds, make sure their maturity is 3 years or less and expect to hold the bonds until maturity. Also, try to avoid investment vehicles that have no maturity constraints, such as bond mutual funds.
On the savings side, rates have leveled off as the Fed goes into a wait and see mode. This is reflected in the rates for savings accounts, money markets, and CDs.
Currently, the average savings account is paying 1.34%, gaining a little bit back from the big drop in January.
The 1 year CD interest rate is now averaging 2.72% and the 5 year CD rate is at 3.03%, pretty much unchanged from the beginning of the month.
Mortgage rates have reversed course, although the 30 year still remains firmly above 4%. Currently, the 30 year rate is at 4.33%, down from 4.40% last month and down for the second month in a row. These rates are responding to the slow down in home sales, the change in policy from the FOMC, and the effects that the tariffs are having on our economy. Rates are responding the right way, so there are no surprises here.
Oil prices followed up its huge rise in January with a 6% gain in February, ending the month around $57 a barrel. The main reasons for this continued upswing are OPEC’s agreement to tighten supplies and the sanctions on Iran and Venezuela.
Obviously, higher prices is good for producers and since the U.S. is the biggest oil producer in the world now, it is good for our economy. But, we are also the world’s biggest oil consumer, so higher prices hurts us as well. It’s a blessing and a curse. Prices right now are in a nice sweet spot, between $50 and $75. Hopefully, they’ll stay there for awhile.
Nationally, gasoline prices haven’t jumped up that much with the increase in oil prices. Prices at the pump are averaging about $2.41 per gallon, 12 cents higher than a month ago. Arkansas has the cheapest fuel, at $2.16. FYI, a year ago, we were paying $2.52.
Check out the prices at the pump in your area: Gas Buddy.
Outlook
Events on the horizon that could move the markets in the near term:
- Federal Reserve: Jay Powell, the chairman of the Federal Open Market Committee (FOMC), had his routine hearing with Congress this past week. He calmed Wall Street once again with his words. This is a positive event for the stock and bond markets.
- Trump-related Investigations: I had to rename this event because there are so many offshoots that have sprung from the original investigation: 17 known investigations. Still nothing from the Mueller-led investigation but I’m pretty sure they have to wrap it up by June of this year, so at least the end is in sight for one investigation. This event will be ongoing for quite awhile, most likely through the 2020 presidential election and will cause some unexpected market swings, in both directions.
- Trade Wars: Negotiations continue with China to try and get a deal that suits both parties. Right now, this standoff is hurting China more than us, but again, they can take the pain for much longer than we can. The deal will get done at some point this year and it should give the market a nice boost if we get the concessions that we want. I kind of think that some of the upswing in stock prices recently is due to the anticipation that a deal will get done, so when it actually does gets done, the boost might not be as big as many expect.
Joe Baker, CFP®
Baker Asset Management, LLC
joebaker@bakerassetmanagement.com

