
Calendar Notes
- Tuesday, November 5th – Election Day
- Monday, November 11th – Veterans Day
- Thursday, November 28th – Thanksgiving, Stock market is closed.
- Friday, November 29th – Black Friday, Stock market closes early at 1 p.m.
Stocks followed history and fell for the first time in the last six months. Since 1950, election-year Octobers have been bad for stocks and this one was no exception. The craziness of the election, the surprisingly robust economy, and the uncertainty of what the Federal Reserve is going to do with interest rates has combined with lackluster Q3 earnings reports to knock stocks down this past October.
For the month, the S&P 500 was lower for the first time in six months, dropping about 1%. For 2024, it is still up nearly 20%.
Interest rates and the election are still the main drivers for stocks in the short term. Another catalyst for stock prices has been AI spending. Companies are spending a ton on implementing artificial intelligence systems but are not seeing the payback yet. This is hurting earnings now but should be a big boost to companies’ bottom lines in the future.
Historically, we are entering the best six months for the stock market: November through April. Looking at November, it has returned a positive 1.4%, on average, since 1945. Stocks have already had a banner year so any gains in these last two months will be outstanding. I am looking forward to seeing how November turns out.
Take a look at the Outlook section below to see what events could move the markets over the short term.
Bond prices reversed course and headed lower in October, for the first time in six months. Government, blue chip corporate, and high yield bonds all moved lower as uncertainty on how much the Fed is going to cut rates in the short term crept back into the markets.
The 10-year US Treasury note yield finished higher in October, settling at about 4.28%, higher than the 3.79% that it was at the beginning of the month. The 30-year bond yield closed out the month at 4.47%, higher than the 4.12% that it was a month ago.
Bond investors may have to watch the election outcomes a bit more closely now. A republican Congress and president may cause rates to increase to combat the expected inflation if heavy tariffs are implemented, which is what is being suggested right now. A democratic win could cause problems for corporations if taxes are raised, and regulations increased. Regardless of the party that wins, keeping maturities under 18 months should not pose a problem, as long as you can hold to maturity.
Savings rates are dropping ever so slightly but most rates changed very little over this past month. It seems like they hit the pause button for now until the Federal Reserve can give us a clearer picture on their rate cutting strategy for the next year or so. Until then, accounts are still churning out some decent interest, risk free, and because of that, there is still a ton of money parked in cash (CDs, MMA, Savings). You can still get over 5% return on your money. So, CDs and MMAs continue to be a great place to put your cash and your emergency fund, for now.
Now, take a look at the top rates for CDs and money market accounts (MMA):
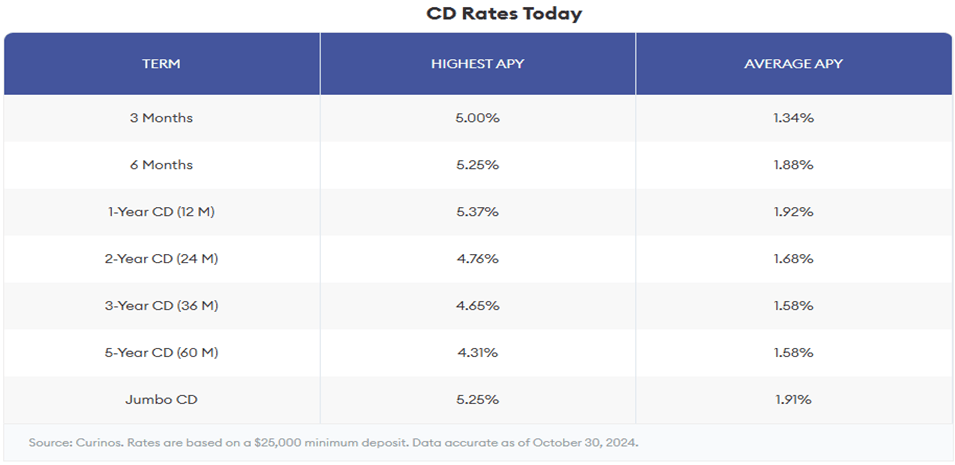
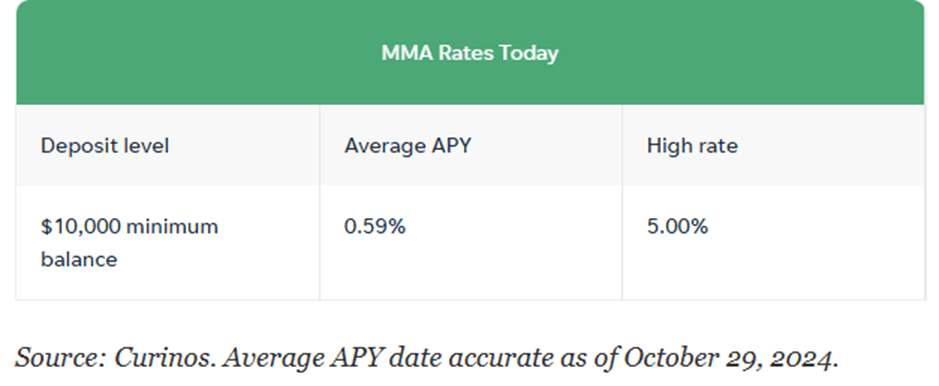
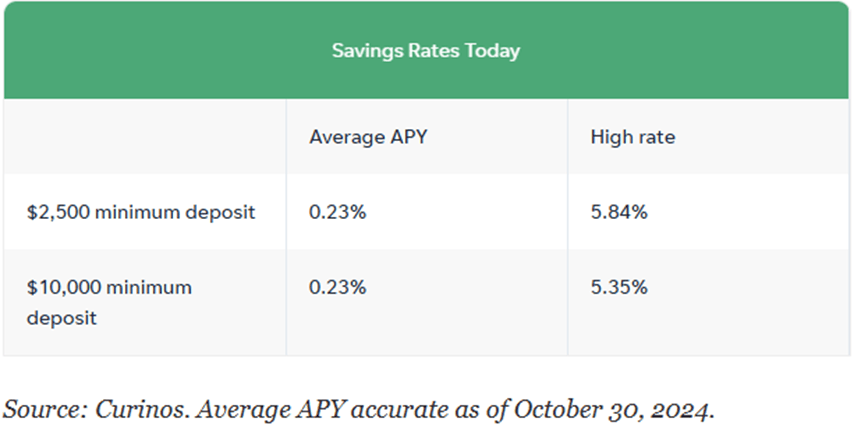
The best 1-year CD interest rate is currently at 5.37%, slightly lower than last month. The best 5-year CD rate right now is around 4.31%, just a 3-basis point drop from last month. MMA and traditional bank savings account rates stayed the same from last month.
Savings rates are going to be coming down over the next year or so as long as inflation remains tame. If this holds true, it would be okay to put cash that you don’t need immediately in CDs with up to 2-year maturities. For emergency cash, stick to high yielding money market and savings accounts, which are still yielding well over 5%. As always, keep the total under $250,000 per person at any one bank to ensure you are fully covered by the FDIC.
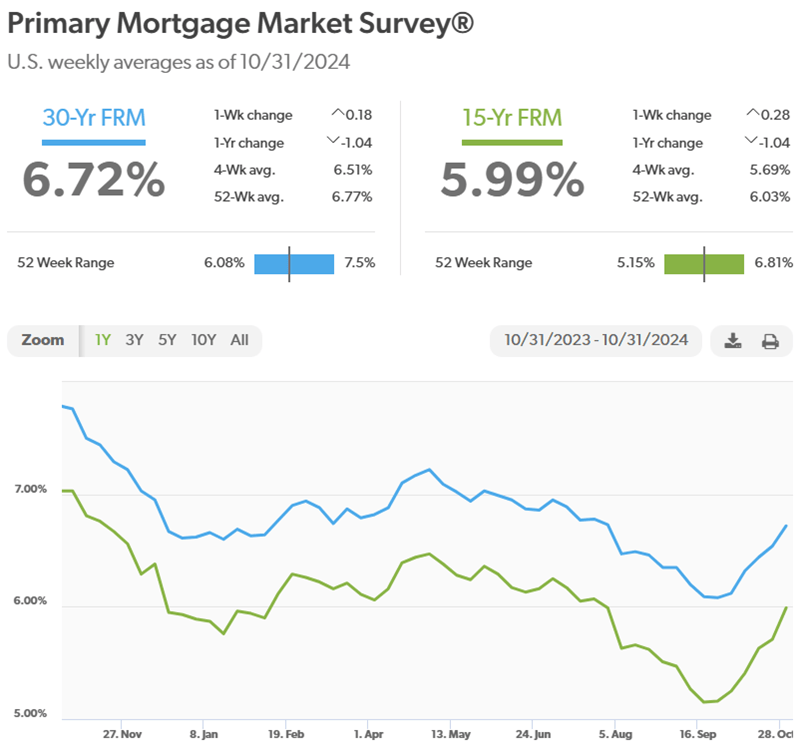
Mortgage rates reversed course and headed higher in October, with the 30-year loan climbing above 6% once again. Currently, the 30-year rate sits at 6.72%, higher than a month ago, at 6.08%. This change in trajectory is mainly due to the data coming in showing an even stronger economy than expected, which is making the case to the Federal Reserve that the country can handle rates staying higher for longer.
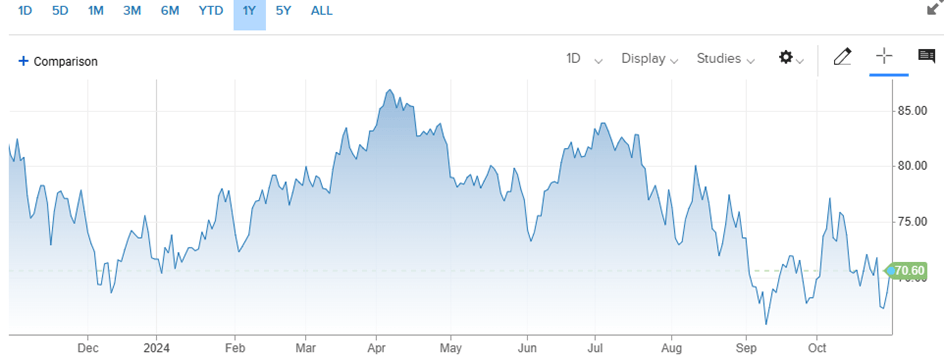
Oil prices spiked higher earlier in the month, but they ended October close to where they were at the end of September. Calmer hurricane activity in the Gulf of Mexico and reduced tensions in the Middle East allowed prices to come down from that spike.
For the month, the price for a barrel of oil settled at $70.60, up from $68.16 at the beginning of October. For the year, the price difference is still slightly negative, down about 1.5%. China’s economy is showing signs of a recovery, which will put upward pressure on prices. Pushing back is the possibility that the Israel/Iran conflict has ended, which would put downward pressure on prices.
Here’s a look at the one-year chart for U.S. oil:
Gasoline prices continued to drop in October. Regular unleaded gasoline is now averaging $3.13 per gallon, down from $3.22 last month. Texas has the cheapest gas currently, checking in at $2.68 a gallon. Hawaii has the most expensive gasoline at $4.59 per gallon. FYI, a year ago, we were paying $3.48.
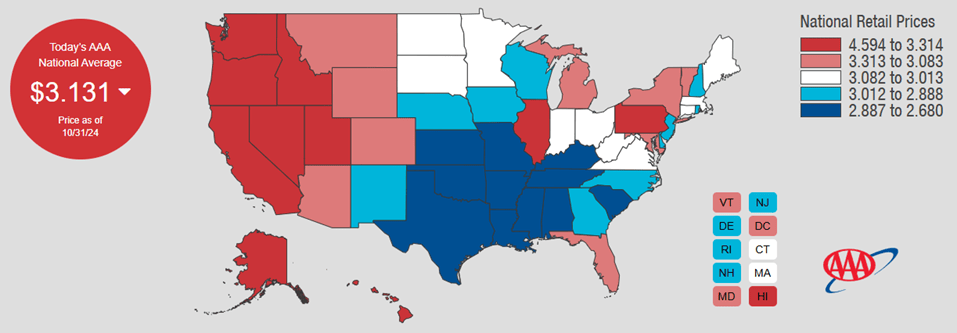
Check out the prices at the pump in your area: AAA Gas Prices.
Outlook
Events on the horizon that could move the markets in the near term:
- Fed & Inflation: Well, it looks like the Fed was able to bring down inflation without causing a recession. Jobs and wage growth are still strong with consumer prices under control. But is the economy humming along too good for the Fed to continue to cut interest rates? This is the big question that will be answered next week when they meet again. How they answer it could dictate how the markets perform through the end of the year.
- Potential Asset Shift: Interest rates have stopped their decline for now as the economy continues to surprise to the upside. That is keeping yields across government bonds, CDs, and money markets attractive enough to not want to make investors shift their money out of these assets, for now. I still believe this great rotation will happen, but it may be more spread out over time if rates continue to stall their move downward.
- Election: Next week is going to be pretty wild, with the election, the Federal Reserve meeting, and more earnings reports. If this election is like the last two, I don’t expect on election night to know what party will occupy the white house or hold a majority in the senate or house of representatives. So, there will certainly be some market volatility due to the elections for at least the month of November.
Joe Baker, CFP®
Baker Asset Management, LLC
joebaker@bakerassetmanagement.com

