
2020 is in the history books now (thank you!) but there is still a quick and easy way to reduce your taxable income for last year:
Make a tax-deductible contribution to your IRA.
If you qualify, an IRA contribution can be a great way to reduce your 2020 taxes. You are allowed to contribute up to $6,000, or even more if you are an old-timer like me: $7,000 for people age 50 and over.
Plus, if you are married, you can double up the amount with a spousal IRA. So, say that you are married and over age 50, you can contribute $14,000 to your IRAs. This would save you $3,500 in federal taxes if you were in the 25% tax bracket. Not too shabby.
If you are not covered by a retirement plan at work, you can deduct the full amount of your contribution, regardless of how much money you make.
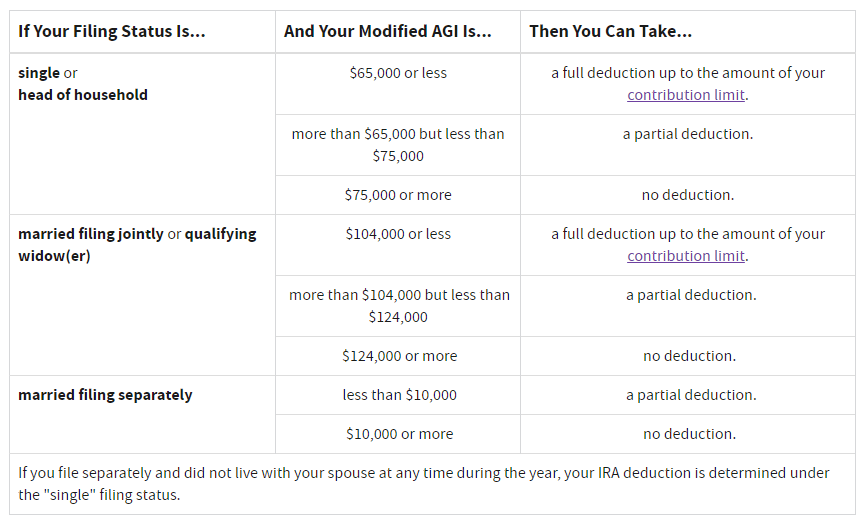
If you do have a retirement plan at work, there are restrictions and limitations to qualify for the full deduction. Here’s a table that summarizes these rules. They are confusing so feel free to shoot me an email with any questions.
2020 Traditional IRA deduction limits
If you’re self-employed, you can sock away a lot more by opening up a Simplified Employee Pension (SEP) plan before filing your taxes. For 2020, you can contribute up to $57,000, depending on your income.
Finally, you have until May 17, 2021 to fund your IRA for 2020 since the IRA extended the 2020 tax filing deadline.
Let me know if you have any questions!
Joe Baker, CFP®
Baker Asset Management, LLC
joebaker@bakerassetmanagement.com

