
Stocks had a pretty decent July, all things considered. Most major indices were able to continue their slow climb upward after stalling in June. The S&P 500 gained about 5% this past month, which enabled it to get slightly above breakeven for the year. For 2020, the resilience of this stock market is incredible.
Covid news is the major market influencer, with the November elections starting to cause some turbulence as well. Progress is being made on the vaccines and treatment fronts for the disease. Realistically, a vaccine wouldn’t be readily available to the general public for at least a year from when it is approved, but the markets will react to the upside way before that.
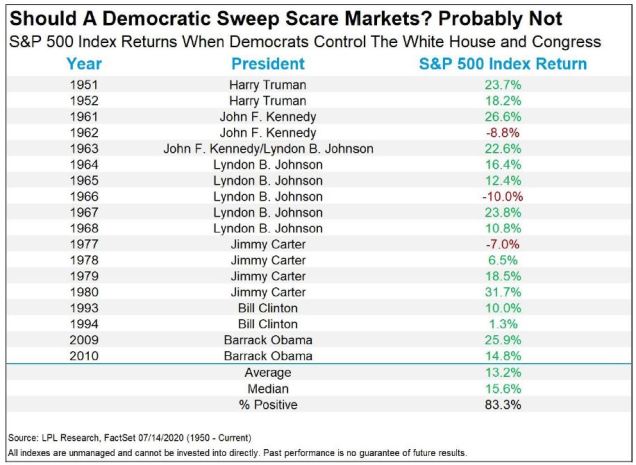
I’m starting to hear a lot of chatter that if the democrats win in November, the markets will tank. Historically, stocks have done much better during democratic administrations than republican so you should not allow this to factor into your investment decisions.
Finally, as I’ve said many times before, interest rates are as low as they have ever been. This puts a nice floor under stock prices because investors want to make money and when rates are so low, they always come back to the stock market.
Having said all that, we still have a very over bought market, so don’t be surprised if we have a correction between now and the elections in November.
Take a look at the Outlook section below to see what events could move the markets over the short term.
Bond prices trended higher across the entire debt spectrum as rates continue to plummet. As long as the Fed is buying bonds, we are not going to see this trend change direction much.
The 10-year US Treasury note is yielding 0.54% and the 30 year is at 1.20%, both lower than last month. These low yields continue to force more money into the stock market because they are just too low to tie up money for such long periods of time.
Interest rates seemed to have stabilized by the end of July. There is no reason for rates to go up at this time. The uncertainty of the pandemic and all the shuttered or semi-open businesses is ensuring rates stay low.
On the savings side, short-term rates, like savings and money market accounts, as well as longer-term rates, like CDs, have levelled off at a very, very low level.
Currently, the average savings account is paying 0.51%, slightly down from a month ago, 0.53%. Nobody is making money in cash, but at least it is safe.
The 1-year CD interest rate is now averaging 0.85%, less than the 0.90% it was yielding a month ago. The 5-year CD rate is tracking lower as well, now at 0.97% from 0.99%. With people saving their income at an unprecedented high rate, these rates will continue to stay historically low. The good news for stock investors is that all this cash is going to have to go somewhere and this usually is a precursor to higher stock prices.
Mortgage rates headed lower yet again in July. Currently, the 30-year rate is at 3.14% down from 3.29% a month ago. The Fed flooding the market with liquidity is helping to keep these rates extremely low, particularly for the variable rate mortgage loans. I wanted to point out that the 15 year fixed mortgage is at 2.75%. That’s cheap money!
Oil prices continued their bounce back after the drop into the abyss in April. The price for a barrel of crude rose about 4% to $40.43. Like stocks, the comeback from all-time lows earlier this year is very impressive. Rising oil prices are reflecting the promise of more demand worldwide as countries begin to open to a more normal operating mode. These prices are good news for all those employed in the fossil fuels industries. I still don’t see demand getting back to where it was 6 months ago so maybe oil prices in the $30 to $40 range will be the new normal. There is so much oil stored already and sitting in ships that it would be tough for prices to continue this uptrend unless there are significant production cuts by the U.S. and OPEC.
Gasoline prices didn’t get as much of a bump as its oil cousin. Prices at the pump are averaging about $2.19 per gallon, 1 penny higher than a month ago. Mississippi has the cheapest fuel again, at $1.84. FYI, a year ago, we were paying $2.74.
Check out the prices at the pump in your area: Gas Buddy.
Outlook
Events on the horizon that could move the markets in the near term:
- Coronavirus: Since last month, the numbers have continued to get worse in the southern and western parts of the country. California’s chart of Covid cases looks like a reflection of New York’s chart. Now, as states prepare for schools to open for the fall semester, there is a deep divide across the country as to what to do. There are valid arguments on both sides. Regardless of whether there is in person or online classes, there are going to be a lot of kids being home schooled this year. This could have a significant effect on the U.S. economy. As I said last month, the markets will rise and fall as news of vaccine rumors swirl around but when the real deal is announced, we will get a huge boost for stocks across the board.
- Interest Rates: Historically, low rates are bad for savers, pension plans, and those on a fixed income. They are great for borrowers and for those that want to invest in riskier assets, such as stocks. According to the Federal Reserve, rates are not going up anytime soon, so this is good for stocks and even bonds.
- Election: For the past decade or so, it seems like every election is the most important election ever. The upcoming November elections are getting the same treatment. I’ve always said that the President doesn’t really affect the stock market (although the current one has certainly tested that theory). The real market movers are the guys and gals in Congress. It’s too early to tell how it’s all going to play out but I’m pretty sure the road there will be as crazy as 2020 can make it. And for anyone that fears a democratic sweep in November will tank the markets, check this out:
- Trade Wars/Tariffs: I don’t expect any progress on these issues until after the election. It is all about Covid right now.
Joe Baker, CFP®
Baker Asset Management, LLC
joebaker@bakerassetmanagement.com

