
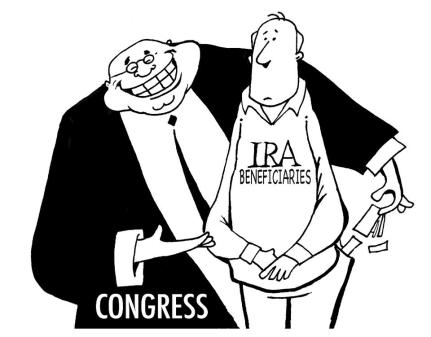
The SECURE Act will be having an immediate impact on beneficiaries of IRAs in 2020 and beyond. Specifically, it will greatly reduce the tax benefits of a strategy known as the Stretch IRA.
Before 2020, heirs of traditional or Roth IRAs could take their required minimum withdrawals (RMDs) over their lifetimes instead of the original account owner’s lifetime. For example, a 20 year old beneficiary of an inherited IRA could “stretch” out the RMDs over her lifetime, which could be another 60 years or more. If the inherited IRA was a Roth IRA, those withdrawals would all be tax free!
Now, many beneficiaries will have to empty the inherited account within 10 years. If it’s a traditional IRA with a balance of a million bucks and you make equal withdrawal payments over the 10 year period, you will have about $100,000 in extra income annually over those years. If it’s a Roth, you will still enjoy tax-free withdrawals, you’ll just have to take it all out within 10 years. In the Roth case, if you don’t need the money, then you should just leave it in there and let it grow for 10 more years before withdrawing it all at once, all tax-free.
There are exceptions to these new rules. Here’s who can still stretch an inherited RIA:
- Surviving spouses
- IRA beneficiaries whose original owners died before 2020
- Chronically ill or disabled heirs
- Heirs within 10 years of age of the original owner
- Minor children up to the age of majority (18 in most states), or age 26 if the child is still in school. At that point, the 10-year payout begins.
This rule really upends any estate planning that was completed before 2020, such as converting a traditional IRA to a Roth IRA, or using a trust to distribute an IRA. You’ll need to revisit your estate plan to address how these new rules will affect it.
As always, please let me know if you have any questions.
Joe Baker, CFP®
Baker Asset Management, LLC
joebaker@bakerassetmanagement.com

